
 I'm LongbridgeAI, I can summarize articles.
UiPath's stock has struggled despite the AI boom, plummeting 49% last year and 62% over three years. The company's growth is slow, and it faces stiff competition from larger firms like Microsoft and Salesforce. UiPath reported a $196.2 million operating loss in the first nine months of 2024, raising concerns about its profitability. Analysts estimate the stock trades at 30 times next year's profits, but uncertainty about its competitive edge and profitability makes it a risky investment.
Artificial intelligence (AI) has been a hot investing theme over the past couple of years. Companies involved with AI have been some of the best investments to own -- for the most part, anyway.
One stock that has been underwhelming despite its focus on AI is UiPath (PATH -4.42%). Last year, the stock plummeted 49%. Over the past three years, it's down a staggering 62%. Those aren't the types of returns you might expect for a business that's focused on automating tasks and which should be the type of stock investors are bullish on these days.
So what's wrong with UiPath, and why isn't it doing better? I'll look at why investors aren't that thrilled with the business and whether it could make for a good contrarian pick this year.
A look at UiPath's fundamentals uncovers multiple issues
A good place to start evaluating a stock is by looking at its earnings report. Its financials can tell you how well the business is growing and if it's doing so profitably.
The good news for UiPath is that the business is expanding, but not at a terribly fast rate. The chart below, which shows UiPath's growth rate, isn't what you'd expect to see, given that companies have been investing more into automation and AI in recent years.
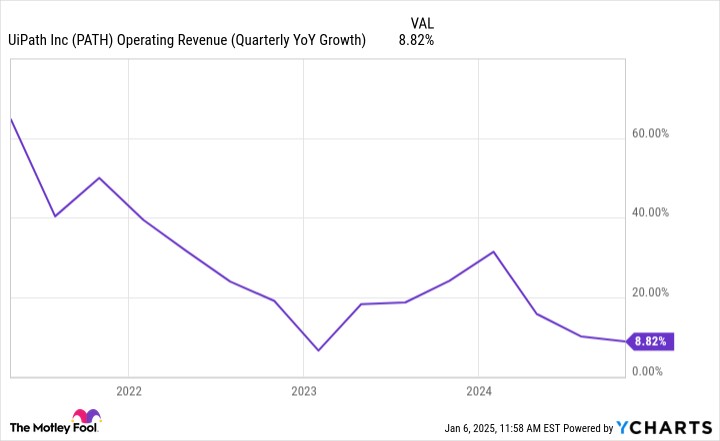
PATH Operating Revenue (Quarterly YoY Growth) data by YCharts
This leads me to believe that before there was ChatGPT and all sorts of AI services helping automate day-to-day processes, UiPath's business stood out more than it does today when there are many similar types of products available. Microsoft's Copilot, for example, offers to help automate processes for Windows users easily. As a result, the demand for UiPath's solutions, which also aim to help automate processes, may not be as strong as it was before.
Another issue is a lack of profitability. Through the nine-month period ending Oct. 31, 2024, UiPath's operating loss totaled $196.2 million and increased by 9% from the same period a year earlier. If the business is expanding but doing so while needing to spend more aggressively, that's not a great sign that its products and services are selling themselves.
2025 may not be a better year for UiPath
UiPath is focusing on many areas that other businesses are already in these days. For example, it sees an opportunity in AI agents and developing apps that can work with agents. Here again, however, there is a potential overlap between Microsoft's offerings and Salesforce, which is also aggressively investing in AI agents.
Without a way to differentiate itself from these other competing products and services, UiPath may find it difficult to win over customers from larger tech companies that can already leverage their existing user bases, not to mention vast resources, to grow their sales.
There simply may not be enough money on AI-related expenditures for businesses to spend on all these different AI solutions, which could make it difficult for UiPath to convince growth investors that it's still a good buy. Research company Gartner has already raised flags by saying that as many as 30% of generative AI projects may be abandoned this year as businesses struggle to justify the expenses. UiPath could be competing against some big companies for a potentially smaller pool of clients this year.
Should you take a chance on UiPath stock today?
UiPath's stock is trading at an estimated 30 times next year's profits, according to analyst expectations. However, I'm doubtful about whether the company will be profitable next year, given its current trajectory. With a slowing growth rate, that would still be a hefty earnings multiple to pay for a business whose solutions may become less competitive as there are more AI-related products available in the future.
With a lot of uncertainty around the business, including whether it can turn a profit and how it will be able to compete against some large tech giants, UiPath isn't a stock I'd invest in today.