
 I'm LongbridgeAI. Here is the key information I extracted
- The number of private charging stations stands at 10.6 million, with a monthly increase of 285,000, while public stations average 1,608 kWh per month, up from 1,461 kWh last year. …
According to the information from Zhitong Finance APP, Cui Dongshu stated that based on the data analysis of the China Charging Alliance organized by the Passenger Car Association, the total number of public charging piles for charging infrastructure reached 4.17 million by June 2025, with an increase of 91,000 public piles compared to the previous month, and an increase of 18,000 compared to June last year, representing a growth rate of 50%. Currently, there are 10.6 million private piles accompanying vehicles, with an increase of 285,000 in June compared to the previous month, representing a growth rate of 9%; in June, the average monthly charging per public pile was 1,608 kWh, which is a good increase compared to 1,461 kWh in June last year.
In recent years, China's charging infrastructure has developed rapidly, establishing the world's largest, most widely serviced, and most diverse charging infrastructure system. If the charging utilization rate of public piles is three times that of private piles, which is a 3:1 ratio, then from January to June 2025, the ratio of charging facilities to pure electric vehicle sales reached 0.77, which is basically a 1:1 relationship. Due to the explosive growth in the installation of public piles, the overall vehicle-to-pile ratio has reached a relatively ample level of 1:1.
Currently, there are still issues with the charging infrastructure, such as inadequate layout, unreasonable structure, outdated technology of old charging piles, uneven service, and insufficient standardization of operations that urgently need improvement. The rate of regret for purchasing electric vehicles in some lower-tier areas has increased. It is believed that as the scale continues to grow, with small adjustment difficulties, the potential for electric vehicles is significant.
Looking to the future, especially with the rapid growth trend of new energy vehicles, particularly electric vehicles, there is a need to further build a high-quality charging infrastructure system, update old low-power AC piles, and increase the upgrade of high-power DC fast charging to better meet the needs of the public for purchasing and using new energy vehicles, and to assist in promoting the green and low-carbon transformation of transportation and the construction of a modern infrastructure system.
1 Overall Status of Charging Piles
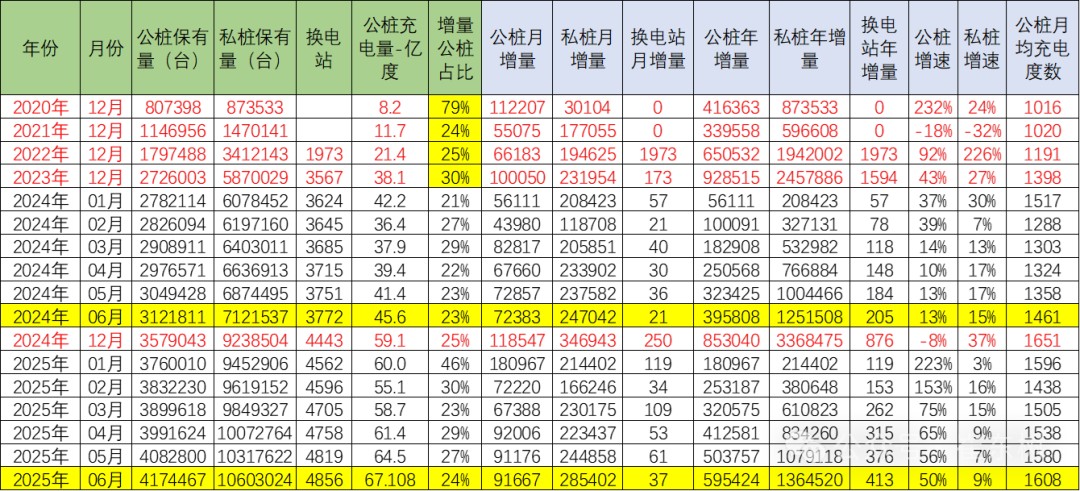
Charging infrastructure provides charging and swapping services for electric vehicles and is an important type of integrated transportation energy infrastructure.
In 2021, the number of public piles increased by 340,000, while private piles accompanying vehicles increased by 600,000. The annual increase in public piles decreased by 18% compared to 2020, and the annual increase in private piles decreased by 32% compared to 2020.
In 2022, the number of public piles increased by 650,000, while private piles accompanying vehicles increased by 1.94 million. The annual increase in public piles grew by 92% compared to 2021, and the annual increase in private piles grew by 226% compared to 2021.
In 2023, the number of public piles increased by 930,000, with the annual increase in public piles growing by 43% compared to 2022. Private piles accompanying vehicles increased by 2.457 million compared to the end of 2022, with the annual increase in private piles growing by 27% compared to 2022.
In 2024, the number of public piles increased by 850,000, with the annual increase in public piles decreasing by 8% compared to 2023. Private piles accompanying vehicles increased by 3.37 million compared to the end of 2023, with the annual increase in private piles growing by 37% compared to 2023 By June 2025, the total number of public charging infrastructure reached 4.17 million, with an increase of 91,000 public charging piles compared to the previous month, and an increase of 18,000 compared to June last year, representing a growth rate of 50%. Currently, there are 10.6 million private charging piles, with an increase of 285,000 in June compared to the previous month, representing a growth rate of 9%; in June, the average monthly charging per public charging pile was 1,608 kWh, which is a good increase compared to 1,461 kWh in June last year.
2. Monthly Growth Status of Charging Piles
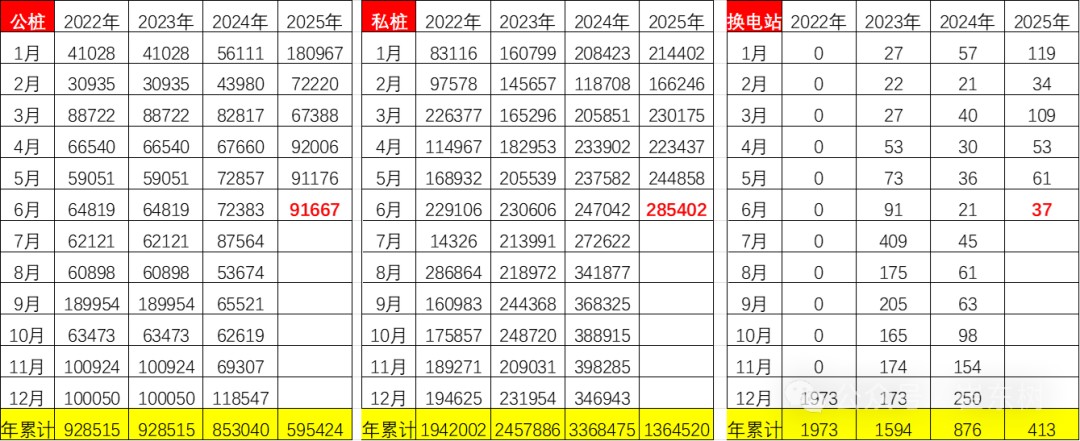
By the end of June 2025, the number of public charging piles increased by 595,000 compared to the end of 2024, showing a rapid growth rate. The number of private charging piles increased by 1.36 million by the end of June 2025 compared to the end of 2024, also showing a rapid growth rate.
By the end of June 2025, the number of battery swapping stations increased by 413 compared to the end of 2024, with a rapid growth rate in recent months.
Charging piles are primarily dominated by private charging. According to surveys, charging is generally done through self-owned charging piles, shared charging piles, and public charging piles within communities or companies, each accounting for 22%-26%, totaling around 75%. A small number of respondents charge at public charging piles on the roadside outside their communities, while some charge at public charging piles located in shopping malls, cinemas, etc.
3. Analysis of Public Charging Pile Characteristics in Various Regions
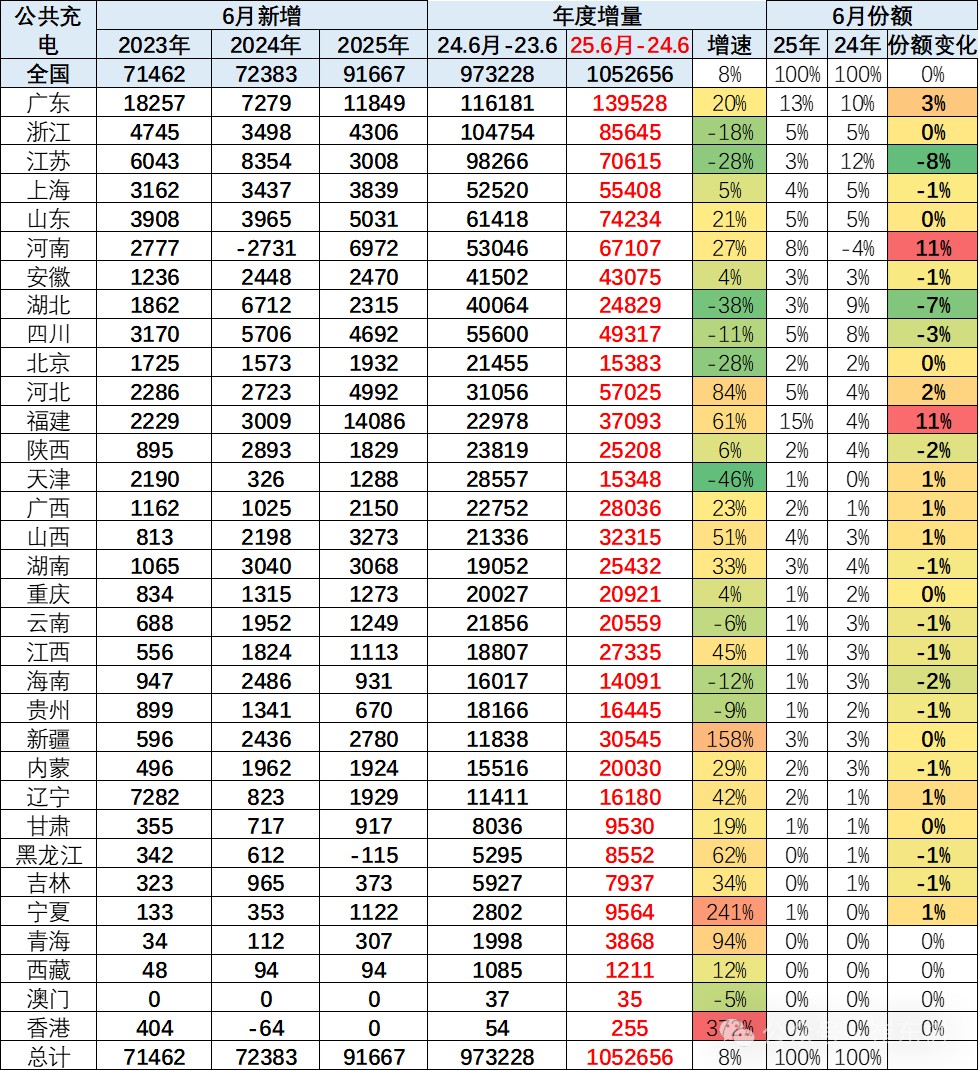
In June 2025, Guangdong saw an increase of 11,849 public charging piles, with a market share reaching 13%. In June last year, the increase was 7,000, with a market share of 10%, showing an upward trend this year.
There are significant differences in the situation of public charging stations across regions, mainly due to the larger scale of charging stations in developed cities. The construction of charging stations is better in Guangdong, Jiangsu, Zhejiang, Shanghai, and Beijing. The status of charging facilities in Beijing has reached a large scale, but growth has slowed down, and the same situation applies to Shanghai.
Currently, the vehicle-to-pile ratio of public charging piles in China is much better than that in Europe and the United States, but there is an issue of underutilization: First, coverage is incomplete. Currently, 10% of service areas on highways are not covered. Second, the structure is unreasonable. 99% of charging facilities are still fast and slow charging, which cannot support the development of high-voltage ultra-fast charging of 800V and above in the next stage. From a micro perspective: First, the operation and maintenance costs are high. The proportion of idle equipment exceeds 30%, and the low level of digitization increases the difficulty and cost of operation and maintenance management; second, the quality of traditional air-cooled equipment is poor. The lifespan of the equipment is only 3-5 years, and operators face replacement before recovering their investment Third, poor service quality. The proportion of "zombie" charging piles reaches 10%, which cannot be charged, exacerbating users' charging anxiety.
4. Analysis of Charging Enterprise Characteristics
Charging pile operators in China can be roughly divided into four types: 1) Integrated enterprises that manufacture charging piles and invest in and operate charging networks, mainly using a heavy asset model, focusing on their own asset operations, and cooperating with other operators and third-party platforms, including Star Charge (affiliated with WanBang Digital), TELD (TGOOD), Wanma Aichong (Wanma Co., Ltd.), Putian New Energy, Shanghai Yiwei Energy, Shenzhen CheDianWang (partially owned by szclou), etc. 2) Self-built charging pile networks by power grids, including State Grid (State Grid Electric Vehicle Service Co., Ltd.) and Southern Power Grid (Southern Power Grid Electric Vehicle Service Co., Ltd.). 3) Large automotive groups that build their own charging networks, including Tesla, Nio, XPeng, SAIC Anyue, GAC Energy, etc., some of which outsource the construction and operation of charging networks to asset-based charging operators and third-party charging service providers. 4) Third-party operators of charging networks, such as YunKuaichong, XiaoJu Charging (affiliated with Didi Chuxing), Shenzhen Huineng, etc., mainly adopting a light asset model, focusing on the vast long-tail market of charging piles, providing SaaS services for regional operators, essentially acting as IT service providers.
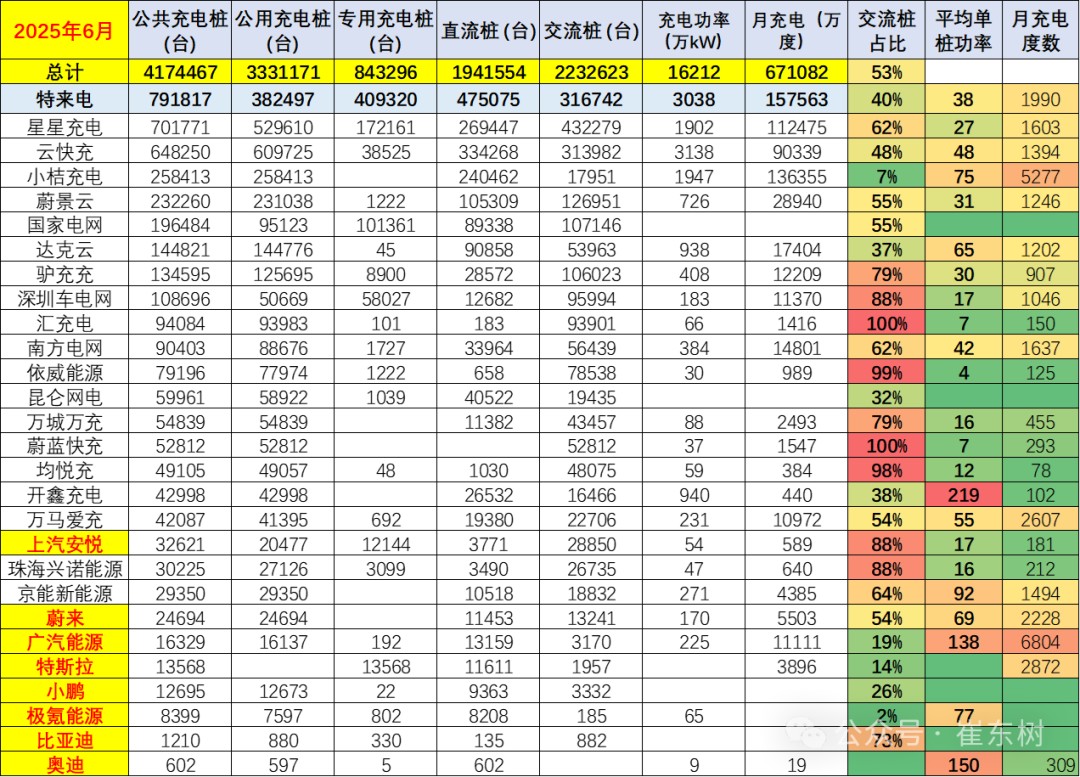
The domestic charging pile operation industry faces four major competitive barriers: capital, site, grid capacity, and data resources, and has currently shown a Matthew effect, with an increase in market concentration among leading enterprises. The current scale of development for DC charging piles is large, with strong performance from leading operators. GAC Energy's charging piles averaged 6,804 kWh in June, performing well every month. Nio's charging piles reached about 2,228 kWh. Tesla reached 2,872 kWh, all performing well. In contrast, some older charging piles average only over 100 kWh per month, while leading charging enterprises average in the thousands of kWh, resulting in a significant efficiency gap of several to dozens of times. Tesla's monthly data remains stable and is quite good.
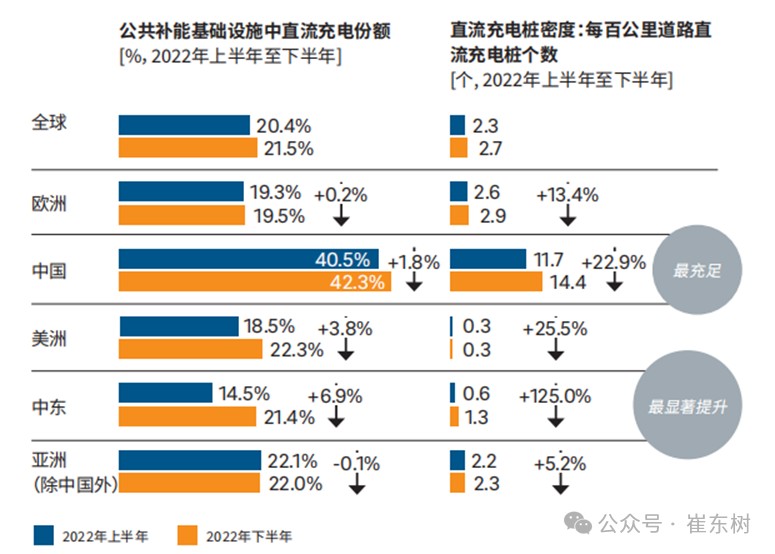
Charging piles are divided into two categories: DC piles (fast charging) and AC piles (slow charging). DC charging piles: larger in size, characterized by high voltage, high power, and fast charging, requiring higher standards from the grid, usually built in highway service areas, bus stations, etc., thus their numbers are fewer, accounting for about 20% Public charging piles: relatively low unit price, easier installation, usually privately owned, thus more numerous and widely distributed, accounting for over 80%. From the perspective of technological development trends, DC piles are gradually moving towards high power development.
In international comparisons, public dedicated charging piles have the best efficiency, and orderly charging for fixed charging demands such as buses is very effective. The number of public DC charging piles and the density of DC charging piles are both showing an upward trend globally. China is in a leading position in promoting DC charging piles: for example, by 2024, the share of DC charging piles in China's public network will exceed 42%. Meanwhile, the Middle East has become a rising "star" in DC charging piles: the share of DC charging piles grew by 7% in 2022, reaching over 21%; the density of DC charging increased by 125%, reaching 1.3 DC charging piles per 100 kilometers of road. The data in these two areas will further grow rapidly.
5 Analysis of Charging Pile Demand Satisfaction Capability
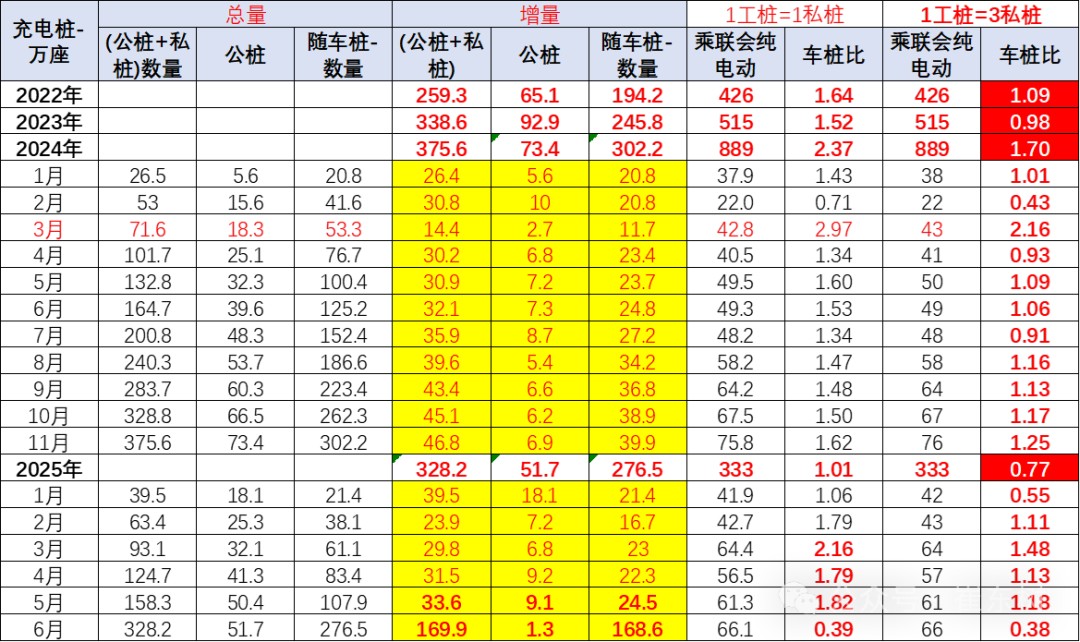
In June 2025, the domestic retail of pure electric passenger vehicles is expected to reach 660,000 units, with the construction of 13,000 public charging piles and 1.686 million private piles. If we consider the public charging piles and private piles as a 1:1 user service comparison, the vehicle-to-pile ratio from January to June 2025 will be 1:1, indicating that charging piles are relatively sufficient. Here, we need to separate the special case of plug-in hybrids with less charging, which is the characteristic demand of the Shanghai model, where only fuel is used without charging.
However, if we look at the charging utilization rate, public piles have a utilization rate three times that of private piles, which means a 3:1 relationship. Therefore, from January to June 2025, the ratio of charging facilities to pure electric vehicle sales will reach 0.77, which is basically a 1:1 relationship. Due to the explosive growth in public pile installations, the overall vehicle-to-pile ratio has reached a relatively ample level of 1:1.
The national new energy development plan clearly states that private slow charging is a development trend and should account for over 90%. Currently, the development of private piles is slightly slow, severely affecting the popularity of electric vehicles.
According to surveys, the satisfaction levels of users with their own charging piles (in terms of charging pile sufficiency, reasonable layout, charging prices, settlement accuracy, etc.) are all higher than those who chose other respondents. Private piles are privately owned by vehicle owners, meeting the demand for home charging, usually built along with the vehicle, and the customer base is large, making them the absolute mainstay of basic charging infrastructure