I'm LongbridgeAI, I can summarize articles.
Sigmaintell forecasts that the average capacity utilization rate of major global wafer fabs will reach approximately 91% in Q4 2026, with foundries operating at high levels. Driven by rising energy and material costs, as well as AI-driven demand, the overall upward trend in wafer foundry prices is confirmed. Performance for mature process manufacturers is optimistic, with SMIC already running at full capacity; prices for 55nm and above are rising due to strong AI peripheral demand, while prices for 28/40nm nodes remain largely flat or see delayed increases
Zhitong Finance APP learned that Sigmaintell stated in a report that the average capacity utilization rate of major global wafer fabs is expected to be around 91% in the fourth quarter of 2026. Foundries are generally operating at high levels, and coupled with factors such as rising energy and material costs, the overall upward trend in wafer foundry prices is certain. Driven by supporting demand for artificial intelligence, the performance of mature process manufacturers is generally optimistic. For instance, United Microelectronics' capacity utilization in Q4 2026 is expected to exceed 91%, a year-on-year increase of more than 10 percentage points; mainland Chinese manufacturers such as SMIC, Hua Hong Grace, and Nexchip have been operating at full capacity since the beginning of the year. In Q4 2026, wafer foundry prices for mature processes will still diverge by node. Visibility for demand in AI peripheral applications for 55nm and above is extremely high, driving continuous price increases; the 28/40nm nodes, situated between advanced computing chips and peripheral chips, have relatively weaker demand drivers in this round of pricing.
Specific analysis of price trends by process node is as follows:
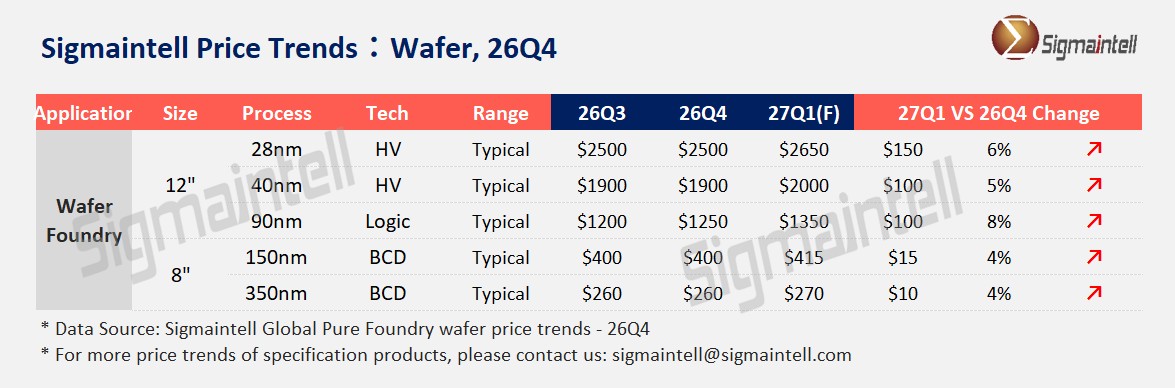
12-inch (28/40nm): "Prices remain flat in Q4 2026, with price hike pressure deferred"
The downstream applications for 28/40nm mainly cover MCUs, Wi-Fi, OLED driver chips, etc. Demand stability has shown resilience during market fluctuations, but growth is relatively moderate during the AI demand boom. The 2026 mature process price hike wave has had a limited impact on the 28/40nm nodes, with quotes remaining generally flat in the first half of the year. Starting from Q4 2026, with the recovery of applications such as communications, DDIC, and ISP, 28nm represented by United Microelectronics shows a good recovery rhythm at the 22/28nm nodes. #Sigmaintell expects its 12-inch mature process (mainly 22/28nm) capacity utilization in Q4 to reach around 93%. However, to accommodate newly finalized customers, the prices agreed upon in 2026 were not adjusted upward. For the 40nm node, represented by SMIC, foundries did not adjust prices at this node due to lower prosperity among mobile phone and automotive customers in 2026. Overall, 28/40nm foundries generally adopted a strategy of accommodating price-sensitive customers in 2026, with no significant price increases in Q4 2026. The price hike pressure caused by costs is expected to be gradually released in 2027.
12-inch (55/90nm): "Continuous price hikes in Q4 2026, with expected expansion of increases in 2027"
The 55/90nm processes cover applications such as high-end power management chips and Nor Flash. In 2026, AI infrastructure drove demand for Nor Flash, high-end MCUs, high-end PMICs, and power devices. Additionally, in consumer electronics, although demand for mobile phones, tablets, and laptops was weak, the repair market saw significant growth, supporting capacity utilization. The 55/90nm processes started a price hike cycle from the beginning of the year. Price increases in Q4 2026 were relatively moderate, mainly because concentrated price hikes are expected in 2027, and manufacturers were not inclined to make major adjustments this quarter. Although a considerable number of second-tier manufacturers entered mass production for 55/90nm processes in the second half of 2026 with aggressive pricing strategies, initial customers were mainly focused on low-end power analog products or refurbished driver chips, temporarily having little impact on the pricing of mainstream manufacturers.
8-inch Wafers: "High order visibility, steady price increases"
Driven by explosive demand for AI-related power management ICs, power devices, and other peripherals, 8-inch processes continue to operate at full capacity with high utilization rates. Order visibility is generally close to six months, especially for 48V high-voltage PMICs used in AI servers, where the process remains predominantly 8-inch, leading to continued supply tightness. Moreover, due to simultaneous contraction on the supply side, Taiwan Semiconductor and Samsung Electronics have both reduced part of their 8-inch capacity. It is estimated that global 8-inch wafer foundry capacity will decrease by about 6% year-on-year in 2026, and continue to decline by about 2% in 2027. Therefore, prices for 8-inch processes show a continuous upward trend. After implementing single or multiple price hikes within 2026, manufacturers will maintain upward price momentum in 2027. For 8-inch processes, manufacturers such as SMIC and Vanguard International still have some room for capacity expansion, but the expansion cycle is long. Thus, the supply-demand imbalance for 8-inch wafer capacity is difficult to reverse in the short term.