
 I'm LongbridgeAI. Here is the key information I extracted
- Bank of America forecasts that NAND average selling prices will decline by low single digits in the first quarter of 2027, contrasting with market expectations of a 10% increase.…
The memory chip market is shifting from "broad-based gains" to "divergence." Bank of America believes that the logic behind DRAM price increases remains intact, while the NAND spot market has shown clear signs of softening, making it the first segment requiring repricing in this current memory upcycle.
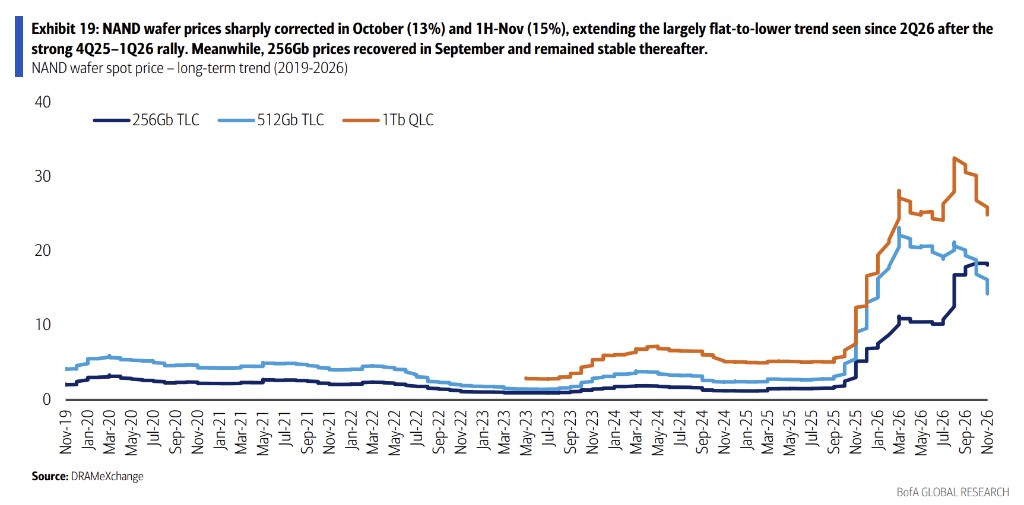
According to Bank of America's report on November 13, NAND spot prices have fallen significantly, with 512Gb wafers dropping over 10% and 1Tb wafers falling by mid-single digits, while 16Gb DDR5 spot prices remained flat. Since late October, NAND spot prices have cumulatively corrected by approximately 20%.
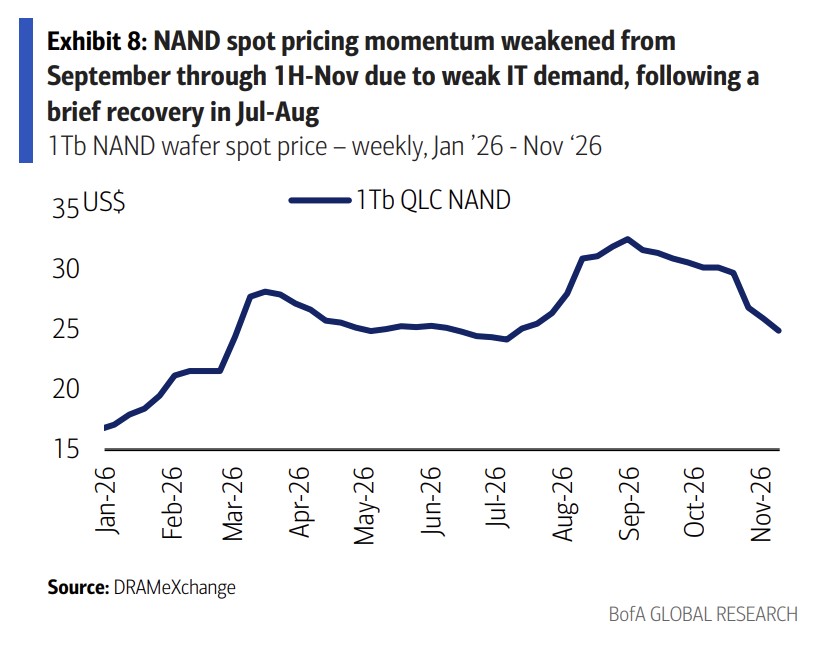
Based on this, Bank of America maintains a cautious assumption for the average selling price (ASP) of NAND in Q1 2027: IT-grade NAND prices are expected to decline quarter-over-quarter by 5% to 10%, enterprise applications will remain largely flat or see slight increases, resulting in an overall low single-digit decline. This view diverges significantly from the market consensus, which still expects NAND ASPs to rise by more than 10%. Meanwhile, Bank of America continues to assume that DRAM price increases will extend into Q4 2026 (an 8% quarter-over-quarter increase) and Q1 2027 (a 5% increase).
Bank of America stated that following discussions with investors this week, sentiment toward memory stocks has improved compared to the previous week, with companies having higher DRAM exposure seen as having limited downside risk. Most DRAM stocks are currently trading at just 3 to 5 times earnings for 2026–2027, significantly lower than their AI semiconductor peers.
Three Signals of Weakening NAND Spot Market
Bank of America attributes its concerns about NAND to three factors: spot prices have corrected by around 20% since late October; orders from PC and smartphone OEMs, as well as Chinese hyperscale cloud providers, have weakened; and negotiations for Q1 2027 contract prices may be delayed, with no rush ordering observed in the market.
The divergence in spot data is quite evident. According to DRAMeXchange, the spot price for 512Gb wafers is $14.3, down 12% week-over-week and 32% quarter-over-quarter, but still up 121% year-over-year. The 1Tb wafer is priced at $24.9, down 4% week-over-week and 19% quarter-over-quarter, but up 194% year-over-year. In contrast, 16Gb DDR5 is quoted at $60.2, flat week-over-week and up 150% year-over-year.
Manufacturers continue to emphasize strong demand for enterprise SSDs, which can partially offset the weakness in IT-grade NAND. However, Bank of America warns that older production lines, accounting for 20% to 30% of global wafer capacity, are not suitable for producing high-end NAND and enterprise SSDs (eSSD) and must continue to be used for IT-grade NAND, creating structural pressure on prices. Per-bit prices for large-capacity NAND (above 2Tb) and eSSDs (above 30TB) have seen slight reductions, but Bank of America views this more as proactive promotions by manufacturers to promote new-generation QLC products—most eSSD NAND prices still show a slight upward trend.
Point of Divergence: Contract Prices Remain High, but Negotiations May Be Delayed
NAND contract prices and spot prices are currently moving in opposite directions.
According to TrendForce, the October contract price for 1Tb TLC wafers remained largely flat month-over-month, continuing the sideways trend seen in Q2 and Q3. The contract price for 512Gb wafers is around $27, near historical highs and approximately ten times the low of $2.5 seen in February 2025.
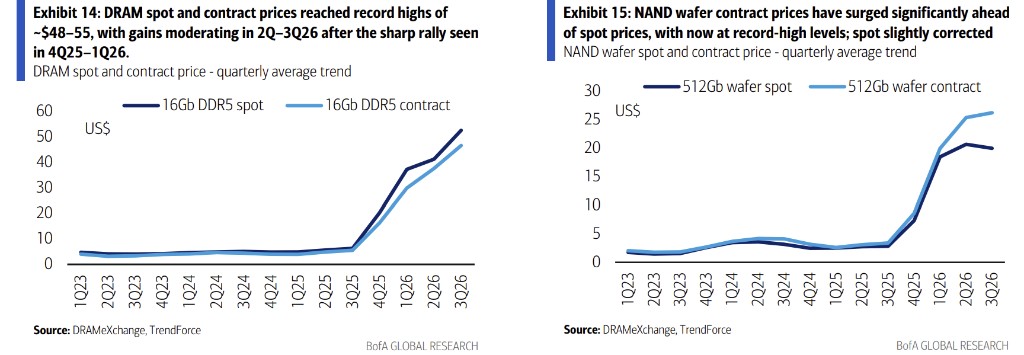
Bank of America's concern lies in the timing: If downstream customers do not place urgent orders, negotiations for Q1 2027 contract prices may be postponed, weakening manufacturers' bargaining power in the new round of negotiations. This judgment directly corresponds to the expectation gap with the market—sell-side analysts generally assume NAND ASPs will still rise by around 10%, while Bank of America forecasts a low single-digit decline.
On the DRAM side, the picture is different. According to TrendForce, the October contract price for 16Gb DDR5 rose another 5% month-over-month, with a year-over-year increase of over 500%. For server-side DDR5 and DDR4, the contract prices for 64GB modules rose by about 15% month-over-month in October, with module prices breaking through the $1,000 mark to reach $1,600 and $1,500 respectively. Based on this, Bank of America maintains its assumption that DRAM prices will rise by 8% quarter-over-quarter in Q4 2026 and by 5% in Q1 2027.
Samsung: Optimistic on HBM, but Not Aggressive
Bank of America held an investor conference call with Samsung Electronics on November 12, highlighting three key points: Strong demand for AI data center chips in the US, with no order cuts despite concerns; a significant improvement in HBM market position compared to a year ago; and strong upward momentum in long-term agreement (LTA) prices for the DRAM business, suggesting that high prices and high margins are sustainable over the long term.
However, management's statements were not aggressive, which is one of the focal points for investors. Samsung's target for HBM market share is around 30% to 40%, rather than over 50%. Even by the end of 2027, LPDDR5 profitability is expected to remain superior to HBM, so HBM capacity expansion is unlikely to be overly aggressive to avoid eroding traditional DRAM market share. Technologically, HBM4e will share the same 1c node and 4nm logic chips with HBM4. Bank of America also noted that the magnitude of contract price increases in 2027 is unlikely to reach the levels expected by TrendForce, as prices have already risen in advance during 2026.
Notably, Samsung's guidance for IT-grade NAND is less optimistic than for eSSD, aligning with Bank of America's price judgments.
Sentiment Improves, Valuation Remains Key Support
Memory stocks rebounded this week, with full-year cumulative gains generally exceeding 100%. SanDisk and Kioxia have returned over 250% year-to-date. Bank of America stated that investors contacted this week generally mentioned limited downside risk, citing the resilience of AIDC chip orders after the US midterm elections, continuing DRAM price increases (in contrast to NAND), and low valuation multiples.
Valuation tables show SK Hynix trading at 3.6 times forward earnings for 2026, Samsung at 4.7 times, Micron Tech at 10.7 times, and Nanya at 5.1 times. In the NAND camp, SanDisk trades at 4.3 times forward earnings for 2027, Western Digital at 13.2 times, Silicon Motion Tech at 16.4 times, and Phison at 7.7 times. Bank of America believes that, compared to AI semiconductor peers, the memory sector's pricing remains moderate.
Bank of America concludes that DRAM supply-demand dynamics and price trends continue to be supported by AI data centers and HBM capacity crowding, while pricing power in the NAND market is shifting toward buyers. The valuation gap and earnings elasticity between the two will depend on whether contract price negotiations for Q1 2027 proceed as scheduled.