
NewUser_CkrdqW

NewUser_CkrdqW

ReturnsTop 13%
5Following60Followers588Likes & Bookmarks
N
NewUser_CkrdqW

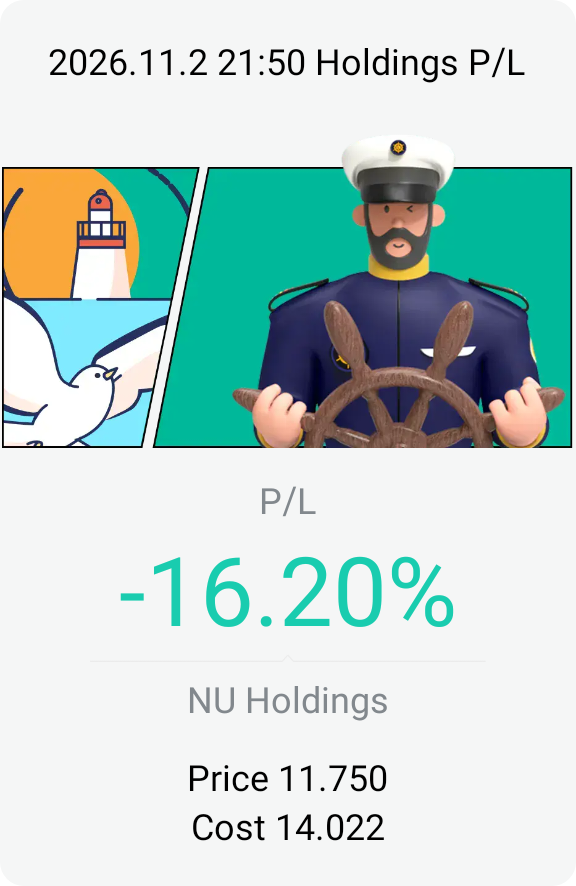
$NU Holdings(NU.US)

Context: Nu Holdings stock dropped sharply after Luiz Inácio Lula da Silva won the closely watched election against Flavio Bolsonaro. The retreat coincided with a broader sell-off in Brazilian companies. Still, despite these challenges, analysts have maintained a bullish outlook for the stock. Benzinga data shows that the average target for the stock is $18.25, up by 57% from the current level. Thiago Batista, a UBS analyst, hiked his target to $20.50 from the previous $18.20, while JPMorgan raised its target from $20 to $23. These analysts have pointed to the company’s user and revenue growth and the fact that its profits are rising. Also, the company is expanding its business in the United States, where it has received a conditional bank charter. The bank plans to have hubs in places like Miami, San Francisco, Northern Virginia, and North Carolina. Nu Holdings’ business has been in a strong growth trajectory as it became the biggest digital bank in Latin America. Its annual revenue has jumped from $1.7 billion in 2021 to $15 billion last year. Analysts expect its annual revenue to hit $22 billion this year and $28.27 billion next year. Its most recent results showed that its revenue jumped to $5.9 billion in Q2 from $3.8 billion in the same period last year. In addition to dominating Brazil, it has now become the biggest neobank in Mexico with over 16 million customers, 16.5% of its adult population. This means that it has more room to grow in the country over time.

My Trade: I think it's a no-brainer to add at these current prices. Nu has proved from time to time that it is one of the more consistent Fintech in the market.

Takeaway: The steep drop was due to a change in political expectations. Nothing changed with the company's fundamentals. The share price is currently undervalued imo. @Captain's Treasure
图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_CkrdqW

Midterms probably the next closest watch for AI and semiconductor stocks. Tough drop to close out Friday, can they turn this around quickly? Or will the drop sustain?

C
Captain's Watch
☕️ [Task Coins Giveaway] Daily Market Talk — Apple Reclaims Top Spot Before Earnings Tonight

Chipmakers crashed on Friday, led by Intel's record drop, but a smaller fall lifted Apple past Nvidia as the world's most valuable company before its results tonight. At home, the STI is sliding this ...

N
NewUser_CkrdqW

If it does drop to $250, I think it makes sense to go in even more for long term. I see the support level to be around $272 but with other chips companies yet to report to another rate hike to come in December, this could go either ways.

FFattycat

Honestly, Google’s pullback offers a rare opportunity for many retail investors. I plan to wait for it to drop closer to US$250 before starting to accumulate. No rush to buy yet just let the dust settle first. The price will come to me. 😁

Gold and Bitcoin are weaker this morning. Bitcoin touched US$76,500 and gold fell below US$4,000 , with no significant news that I am aware of.

Today is Friday and month‑end. Do trade prudently and take your time. Market correction is normal. Don’t rush. Market is always there 😁. Happy weekend to everyone.

N
NewUser_CkrdqW

Earnings season is fully underway, with increasing Capex and earnings misses contributing to steep one day dips even for major companies like Alphabet, Amazon, Intel etc. Ahead of next week's local banks earnings, I think another pullback could be on the cards if earnings don't live up to expectations. Regardless, I don't think we are at an economic slowdown per se, more of reality settling in after enormous rapid growth in the past year

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — Alphabet Suffers Its Worst Day Since 2004

Alphabet had its worst day ever, and Amazon and Intel slid after hours. Eli Lilly and Apple bucked the selloff with records. Let's dig in 👇 💬 Big Tech is paying for AI with cash flow. Buying the Alpha...

N
NewUser_CkrdqW

$Amazon(AMZN.US)

Context: Amazon reported its Q3 2026 financial results. AWS revenue growth accelerated further and beat market expectations, while the group's operating margin reached a record high. However, total revenue fell slightly short of expectations, advertising revenue came in below expectations, and AI infrastructure investments continued to widen the free cash flow gap. In the third quarter, Amazon reported revenue of $201.944 billion, up 12% year-over-year, which was $366 million below the market consensus estimate of $202.310 billion. The company specifically noted that Prime Day events in most major markets were moved to the Q2 this year, whereas last year they occurred entirely in the third quarter. AWS was a key highlight this quarter, with revenue reaching $45.984 billion, up 39.3% year-over-year, accelerating further from approximately 37% in the previous quarter and topping market expectations of 38%. Meanwhile, the advertising business underperformed expectations, posting revenue of $19.637 billion, an 11% year-over-year increase, which fell $1.183 billion short of the market consensus of $20.820 billion. The company stated that advertising growth was affected by Prime Day and other timing factors, and it expects fourth-quarter advertising revenue growth to rebound to nearly 20% YoY. Together, AWS and the retail operations drove consolidated operating income up 61% year-over-year to $28.076 billion, pushing the operating margin to a record high of 13.9%, up from 9.7% in the prior-year period.

My Trade: Looking to accumulate more only if it drops below my cost price. More focused on Google for now.

Takeaway: Q3 Free Cash Flow posts negative $33.456 billion. Cash flow pressure stemmed primarily from expanding capital investments. This reiterates investors' concern following Google's negative FCF - investors want stronger balance sheet and faster ROI. Unfortunately, Capex usually does not translate into profits so quickly. @Captain's Treasure

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_CkrdqW

Honestly, Google is looking very attractive below $300. This negative cash flow and higher Capex is only temporary, though it warrants an understandable sell-off. Despite that, Google's cloud revenue is still surging. Search ad revenue can be improved, but otherwise long term trajectory still looks solid

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — Alphabet Slides After Earnings as Microsoft Gains

Alphabet's cloud revenue doubled, yet its free cash flow turned negative and the stock slid after hours, while Microsoft rose on faster Azure growth. The Fed held, with two votes for a hike. Let's dig...

N
NewUser_CkrdqW

$Microsoft(MSFT.US)

Context: Microsoft reported earnings: Revenue was $92.3bn (+19% YoY), about 2% above consensus. OP reached $45.9bn (+21% YoY), about 5% ahead of consensus.

OPM was 49.8% (+90bps YoY), supported primarily by cost discipline. Azure revenue was $33.17bn (+48% YoY), vs. guidance of 44%–45%. More importantly, 2Q growth is guided to 49%–50% ex-FX, implying continued acceleration. Microsoft showed investors that it's able to grow rapidly while keeping spending in check. Microsoft's stock is rising while Alphabet's is falling, showing how investors are paying more attention to whether AI spending is paying off. This was the first quarter in which Microsoft broke out the revenue contributions of its Azure cloud-computing business in absolute terms.

My Trade: Glad that the stock is rising and Azure is finally paying off. I'm still in the long game for Microsoft so no big changes.

Takeaway: Microsoft's earnings proved that Capex and cash flow remain vital to investors - in contrast Alphabet's second straight quarter of negative cash flow has led to the stock dropping 9% after hours, potentially even more when trading starts later. @Captain's Treasure

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_CkrdqW

$SoFi Tech(SOFI.US)

Context: SoFi reported Q3 GAAP net revenue of $1.385 billion, up 44% YoY, while adjusted net revenue reached $1.371 billion. GAAP net income rose 73% to $241 million, with diluted earnings of $0.18 per share. Adjusted EBITDA increased 70% to approximately $470 million, representing a 34% margin. SoFi added a record 1.2 million members during the quarter, taking its membership base to 17.1 million, up 35% from a year earlier. Total products climbed 44% to 26.7 million. Importantly, 51% of new products were opened by existing members. Total loan originations rose 71% to a record $16.9 billion. Personal loans accounted for approximately $12.6 billion, student loans $2.9 billion, and home loans $1.4 billion. Deposits increased $5.8 billion during the quarter to $51.3 billion. SoFi estimates its deposit-funded model delivers approximately $745 million in annualized interest-expense savings compared with warehouse financing. Net interest margin improved 16 basis points sequentially to 6.14%. Management raised its 2026 adjusted net revenue guidance & introduced targets of $6.4 billion in adjusted net revenue, $2.24 billion in adjusted EBITDA, and $0.90 in adjusted EPS. That implies roughly 27% revenue growth and 48% adjusted EPS growth compared with its 2026 guidance. The difference points to expected operating leverage, meaning profits could grow faster than revenue as the business scales.

My Trade: Trimmed my position yesterday as recent months data showed that the bullish momentum for Sofi is hard to maintain.Inn hindsight, perhaps being patient could have allowed me to sell at a better price now.

Takeaway: The stock's response was decisive. Trading volume exceeded 160 million shares yesterday, more than three times its recent daily average. That level of activity suggests the earnings release prompted a major reassessment, although it can not tell us how much buying came from long-term investors rather than short covering. @Captain's Treasure

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_CkrdqW

Sk Hynix posted record quarter once more with them being sold out till 2029, that is 2+ years from now. The stock is rising after hours as it should, but the long term share price stability remains a question. How long more will AI spending on memory chips continue? Can the customers of Sk Hynix fulfil their orders without solvency/debt issues?

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — SK Hynix Profit Soars Before Tech Earnings and Fed Decision

SK Hynix says its memory chips are sold out until 2029, and every stock in the chip index rose for a second day. Tonight Microsoft and Alphabet report, just before the Fed. Let's dig in 👇💬 SK Hynix is...

N
NewUser_CkrdqW

I pick Sk Hynix. Having just listed in US exchange, it's already seen much volatility over the past months. Nonetheless, Sk hynix continues to post Increasing profits and crucially, citing more demand from AI data centres. Like it or not, the AI spending is not going anywhere soon, at least for the next 2 years. I do believe it still has more room to expand. On the other hand, Seagate & SanDisk have enjoyed their fair share of enormous bullish runs. Despite the recent pullback, I think momentum remains slightly weaker.

C
Captain's Watch
💾 Memory Earnings Challenge — Pick the winner, win cash rewards!

Three memory names report inside three days — Seagate Tuesday, SK Hynix Wednesday, SanDisk Thursday — and they sit on three completely different layers of the storage stack. Pick the one with the highest net gain this week, back it up, and the 3 best takes win 2 SGD each.

1 LONGBRIDGE MEMORY WEEK( CHALLENGE Three memory names, three days, one winner.
N
NewUser_CkrdqW

$Amazon(AMZN.US)

Context: Anthropic's IPO filing reveals approximately $500 billion in compute commitments across major tech firms including Broadcom, Google, Amazon, Microsoft, AMD, and SpaceX. Analyst Nicholas Mugalli highlights that despite a $65 billion annualized revenue run rate, Anthropic has captured only 0.2% of the estimated $30 trillion addressable market. With strong customer growth and substantial cash reserves, Mugalli asserts the company is one of history's fastest growers and has 'barely started' tapping its potential.

My Trade: Looking forward to Amazon's earnings to see if it can push it back above $260. If it drops instead, I'm targeting a price of $230 and lower.

Takeaway: Amazon is set to be one of the benefactors from the IPO of Anthropic as they invested quite heavily into the latter. Investors who were keen to get into Anthropic had already purchased Amazon previously. @Captain's Treasure

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_CkrdqW

Meta stock price continues to be under pressure after launching another share sale for a planned capital raise. This obviously does not sit well with investors as the dilution comes from existing shareholders and not the board

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — Nvidia and Chips Rally as Anthropic Files for Its IPO

Every stock in the Philadelphia chip index rose as Anthropic filed for its IPO, and Tesla jumped on a SpaceX merger bet. At home, the banks slipped. Let's dig in 👇💬 Anthropic's filing lifted every chi...

N
NewUser_CkrdqW

$Alphabet(GOOGL.US)

Context: Alphabet will report its third-quarter 2026 financial results after market close on Wednesday. As demand for AI infrastructure continues to grow, Google Cloud is becoming a new growth engine for the company, but capital expenditures driven by data centers, servers, and custom chips are also climbing rapidly. According to market expectations, Alphabet's third-quarter revenue is expected to reach approximately $127.9 billion, up nearly 25% year-over-year; earnings per share are projected at around $2.94, noticeably lower than the growth momentum reflected by revenue growth. It is worth noting that Alphabet's second-quarter EPS was boosted by large investment gains, so when comparing core earnings performance, operational health cannot be judged simply by year-over-year changes in reported EPS.

My Trade: I think current price range is looking more attractive, but I'm not in the rush. Let's see after the earnings.

Takeaway: One key thing to note is also FED's FOMC meeting on Wednesday as well, as more details on their interest rate target range will be officially revealed. This will give us a better sense of what to expect for the economy and stock market as well. @Captain's Treasure

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_CkrdqW

Tech and AI stocks remain weak ahead of a potentially crunching week with more companies reporting earnings, particularly Microsoft & Alphabet on Wednesday, after FED's announcement.

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — Micron Rebounds as Huang Dismisses Glut Fears

Micron bounced Friday as Jensen Huang played down fears of a memory glut, with the Fed and Big Tech earnings ahead. At home, REITs held their gains. Let's dig in 👇💬 Memory makers report this week. Is ...

N
NewUser_CkrdqW

Thanks for the great insights Options Puppy! You mentioned "A good company can still fall substantially, and a great story can still be a terrible investment if I enter at the wrong price or take too much risk." and I totally agree with you on that. As per your username suggests, I thought you would be more into Options trading but I take that back after reading through your interview. That being said, my questions to you are as follow:

1. How do you use Options strategically to earn some steady profits? (say for example cash secured puts)

2. For laymans who have 0 knowledge on options trading, what advice would you give for us to learn and potentially use options statistics as a better guide for trading/investing without having the need to actually play with options?

3. Do you recommend DCA-ing into ETFs or buy 1 shot at a reasonable size during a crash (recession etc) and hold till the next major dip?

C
Captain Leo
Bridgers' Stories EP03 | How a Singapore Tutor Learned That Being Right Isn’t Enough

ABOUT THIS COLUMNBridgers’ Stories is Longbridge Singapore’s community interview column.Every episode, we sit down with one member of this community — someone whose posts you already scroll past every...

03 LONGBRIDGE BRIDGERS'STORIES EPISODE NAME @optionspuppy FOCUS Stocks & options
N
NewUser_CkrdqW

$Meta Platforms(META.US)

Context: Q3 beat expectations, and the core franchise remains solid. Ads stayed strong, with growth driven mainly by ad pricing (+14%), accelerating for the third straight quarter. Q4 total revenue guide of $73-76bn meets the more bullish buy-side bar of $74-75bn. While Meta’s revenues surged by 26%, its operating income was negatively affected, giving investors an ambiguous perspective on the firm’s financial health. Meta expects more revenue as AI investments keep growing. Meta has made changes to its estimated annual investment, which now stands at $135 billion to $145 billion compared to the previous figure of $130 billion to $145 billion. The analysts had predicted that the spending was around $138.27 billion. The concentration on this part is primarily towards the data centers and other devices used to train the system and AI assistants. Audience growth was slightly disappointing, as daily active users on Meta’s apps reached 3.64 billion, slightly underexpectations.

My Trade: I'm holding Meta for the long term and this current price movement/range doesn't significantly affect my decision. I'm waiting for a lower price, preferably lower than $700 to buy more to give myself more margin to work with.

Takeaway: September’s release of Muse, Meta’s personal AI assistant, helped the stock record its strongest performance in a while. The software can handle tasks such as sorting through emails, searching online and identifying deals on products. None of those abilities are particularly new, but Meta can introduce them to an audience numbering in the billions. @Captain's Treasure

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!