
NewUser_zS0M8w

NewUser_zS0M8w

28Following13Followers

Articles

N
NewUser_zS0M8w

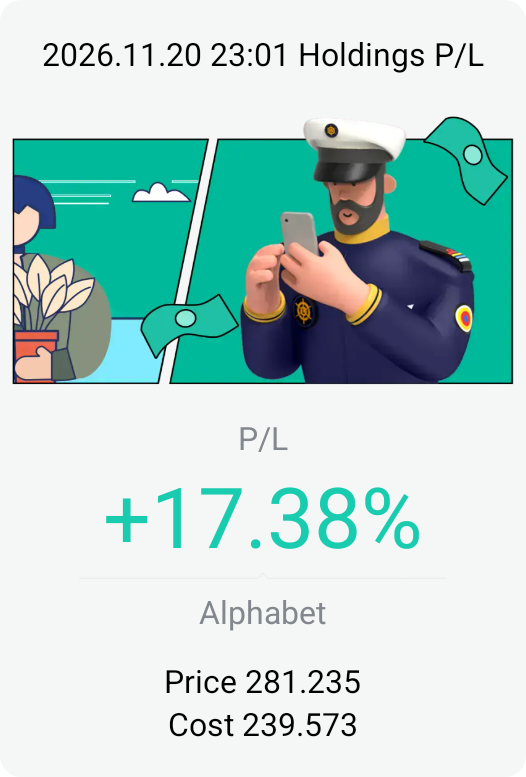
$Alphabet(GOOGL.US)

Context: Google‘s biggest competitive threat to Nvidia may not come from a startup trying to build a cheaper graphics processor. It could come from a company that has spent years developing its own AI chips, already has some of the world’s most demanding AI customers and is now trying to put those chips directly inside customers’ data centers. The Alphabet subsidiary is accelerating its efforts to sell Tensor Processing Units (TPUs) beyond its own cloud infrastructure, potentially turning an internal technology advantage into a much bigger external business. Google had approached customers including Meta about installing its TPUs in their own data centers rather than simply renting computing capacity through Google Cloud. Meta was reportedly discussing spending billions of dollars on Google’s chips for its data centers in 2027, while also considering renting TPUs through Google Cloud. The talks were significant because Meta had historically relied heavily on Nvidia’s processors to train its AI models.

My Trade: Doubled down and added more Google shares. I believe in Google more than Nvidia right now.

Takeaway: Google is also developing software called TPU Command Center to make its chips easier to operate, addressing one of Nvidia’s biggest competitive advantages: its CUDA software ecosystem. The ambition is considerable. Some Google Cloud executives have reportedly discussed capturing as much as 10% of Nvidia’s annual revenue through the TPU business. @Captain's Treasure
图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_zS0M8w

Deep sea of red as shares continue to slide to end the week. Short sells are soaring and the worst part is the entire market is dropping together, not just a simple rebalance of portfolios

N
NewUser_zS0M8w

Feels like the market (especially semiconductor sector) has been down since September/October. While in reality, the S&P is still significantly up for the year despite the slight retrace in the past months. This really calls for diversification of assets to prevent falling trap to a single sector/industry.

N
NewUser_zS0M8w

$NVIDIA(NVDA.US)

Context: Speaking with Andrew Ross Sorkin at The New York Times DealBook Summit on Wednesday, the CEO of Tesla and Space Exploration Technologies Corp. called Huang “an old friend of mine,” and added that he was like “Michael Jordan perhaps at his peak level” to a team. Musk compared Huang’s departure to the Chicago Bulls kicking Jordan off the team during a winning streak.

“Doesn’t seem like a smart decision to me,” he said. “I think it was a mistake and I’ve said so publicly.”

Huang resigned last week amid an independent board investigation and reports of extramarital affairs, including one involving a suspected Chinese spy. Musk called Huang a one-man replacement for several roles. He acknowledged Huang “certainly made some mistakes,” but not that he is “disloyal to the United States.”

My Trade: Well my bet that it will rise after earnings was true for premarket till it wasn't. The share price reversed and even closed down for the day.

Takeaway: Influential tech leaders are calling for Jensen's return, while Nvidia board remains firm on their position. Investors are also torn, with some advocating for and others against the return of Jensen. That's why we are seeing the instability in Nvidia's stock price. @Captain's Treasure

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_zS0M8w

Anthropic IPO remains oversubscribed and valuation continues to rise slightly before the official listing, though the valuation has already slipped a little.

N
NewUser_zS0M8w

$Amazon(AMZN.US)

Context: Anthropic has drawn orders for nearly seven times as many shares as it’s offering in its IPO, but Steve Eisman thinks the bigger question for AI investors is how much state and local governments will slow data center construction. "I think the Anthropic IPO is not important anymore," the "Big Short" investor told CNBC on Tuesday. When the host asked if the IPO mattered less because the expected valuation had fallen from $2 trillion, Eisman replied, "It’ll be whatever it’ll be." He’s also watching whether the financing network former Nvidia CEO Jensen Huang built can hold up. He thinks a 10% to 30% slowdown could actually help the biggest cloud companies. They could pay for more of the work with the cash they bring in, borrow less and keep building for longer.

My Trade: Amazon remains one of the few big tech companies that are still up for the year. My hunch is that it will continue to grow steadily.

Takeaway: Smaller cloud companies like CoreWeave and Nebius could struggle to borrow if the financing deals Huang put together fall apart. @Captain's Treasure

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_zS0M8w

With Nvidia reporting tomorrow morning, semiconductor stocks are mostly sliding as the industry leader dictates the direction of the AI trade. With new interim CEO/former CFO in charge to deliver her first earnings, how would investors take that in? Let's find out soon

N
NewUser_zS0M8w

$NVIDIA(NVDA.US)

Context: Tumult at Nvidia spells the end of easy money for the AI sector and a funding squeeze for smaller, highly leveraged “neocloud” companies that have helped fuel the industry’s rapid expansion. In recent years, Nvidia’s financial support has boosted infrastructure providers and other partners of the giant chip firm. Bond investors say the uncertainty over who might eventually succeed ousted Chief Executive Jensen Huang has raised questions about Nvidia’s willingness to continue support through vendor financing, guarantees and other methods, hitting these firms’ shares and bonds. “It’s fair to say that anyone who takes over is going to have a lower risk threshold than Jensen when it comes to Nvidia’s balance sheet,” said Loren Moran, fixed income portfolio manager, at Wellington Management. “There may just be a lot less credit availability toward weaker players.”

My Trade: Took a bet and bought Nvidia today, with hopes that earnings tomorrow can spur the stock up.

Takeaway: Chief among the firms cast in an uncertain new light are the so-called neocloud firms such as CoreWeave and Nebius, cloud computing companies that acquire graphics processing units (GPUs) or electronic chips, renting out computing capacity to AI developers, startups, and large technology companies. @Captain's Treasure

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_zS0M8w
Featured

$Alphabet(GOOGL.US)

Context: Nvidia's management changes are creating a new window of opportunity for Google to expand its AI chip business. Prominent supply chain analyst Ming-Chi Kuo noted that recent increases in custom chip orders from OpenAI and Anthropic have extended shipment visibility for Google's TPUs through 2029, ahead of most Nvidia GPUs and other AI ASIC suppliers. According to Ming-Chi Kuo's supply chain survey, OpenAI and Anthropic are expected to require a combined total of approximately 26 million TPUs between 2028 and 2029. Of this total, OpenAI's demand is around 12 million units, primarily through direct purchases, while Anthropic's demand is about 14 million units, combining chip procurement and compute leasing. Nvidia's product advantages will not disappear immediately as a result, but Jensen Huang's resignation and the fact that a permanent successor has not yet been determined could prompt customers to place greater emphasis on supply diversification when formulating compute plans for 2028 and beyond.

My Trade: Bought Google previously during the earnings dip and plan to hold.

Takeaway: For Google, this represents a key opportunity to transition its TPUs from internal infrastructure into an external commercial product. @Captain's Treasure

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_zS0M8w

Will Jensen get rehired at Nvidia as employees petition for him to be reinstated? Or will he turn to join Musk at SpaceX? I think neither in the short term. He seemed mentally drained from all that has happened in the past week, and with the hearing with US officials about to take place, I don't think he will have the time nor energy to think of getting another job right now.

N
NewUser_zS0M8w

$Super Micro Computer(SMCI.US)

Context: Super Micro Computer (SMCI) stock rebounded 1.73% in Thursday's after-hours trading, recovering some losses after an 11% plunge during the regular session. The rebound came after the AI server maker denied having any business ties to Megaspeed, following reports of Justice Department investigations involving the companies.The latest concerns came just days after Super Micro delivered a strong fiscal first-quarter report. The company beat Wall Street's revenue and earnings estimates for its fiscal first quarter. Earnings per share came in at $1.81, above the $1.28 estimate. Revenue nearly quadrupled year over year to $19.95 billion, beating the $16.29 billion forecast. It also topped the company's own estimate of $18.5 billion to $19.5 billion. Gross margin rose to 12.8% from 9.5% a year earlier. It also beat Wall Street's estimate of 11%, showing better profits on sales. Super Micro also gave a strong outlook for the current quarter. It expects revenue of $19.5 billion to $21.5 billion, well above the $17.51 billion analyst estimate. Its EPS forecast of $1.66 to $1.90 also topped Wall Street's $1.14 estimate.

My Trade: Was waiting for a further drop to buy more as the steep decline is an overreaction in my opinion.

Takeaway: For the full fiscal year, the company expects revenue of $72 billion to $82 billion. The forecast pointed to continued demand for Super Micro's AI servers as data center spending remains strong. @Captain's Treasure

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_zS0M8w

Breaking news to the AI industry as Jensen steps down immediately, marking an end (for now) to potentially one of the greater Wall Street success stories. Moreover, I am more concerned with Nvidia's earnings next week despite the loss of their key leader.

N
NewUser_zS0M8w

$Nebius(NBIS.US)

Context: Nebius stock fell about 18% in trading. The AI cloud company beat estimates for the third quarter and guided fiscal 2027 revenue above analyst expectations, but said it now expects 2026 revenue at the low end of its $3 billion to $3.4 billion range. The company reported adjusted quarterly earnings of 30 cents per share, beating the analyst consensus estimate of a loss of 69 cents by 144.93%. This represents a 177.5% improvement from the loss of 40 cents per share reported in the same period last year. Nebius Group reported quarterly revenue of $980.8 million, beating the analyst consensus estimate of $907.53 million by 8.07%. This represents a 571.32% increase from revenue of $146.1 million in the same period last year. Adjusted EBITDA, a measure of operating profit before interest, taxes, depreciation and certain other items, was $465.8 million. That compared with an adjusted EBITDA loss of $5.2 million a year earlier.

My Trade: Honestly, with how volatile the market is right now, I am patient on Nebius. Waiting for lower price to accumulate.

Takeaway: The sell off reiterates investors' demands for higher standards and expectations especially for higher risk stocks like Nebius. @Captain's Treasure

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_zS0M8w

Hot CPI data renewed calls for FED interest hikes, though this should not come as a surprise as many have already anticipated it. Economies are still growing, but supply side shocks are the main cause of rising prices and headline inflation.

N
NewUser_zS0M8w

$NVIDIA(NVDA.US)

Context: Amid a concentrated selloff in AI stocks, Nvidia's valuation has fallen to levels not seen in years. The company's 12-month forward P/E ratio is currently about 11.7x, marking its lowest level since October 2011 and falling below 12 times for the first time since 2012. In comparison, the S&P 500 Index's forward P/E ratio remains near 18 times. However, a declining valuation does not necessarily mean the stock is cheap. Even as the stock price falls, Wall Street still maintains high expectations for the company's future earnings; if AI capital expenditures, data center construction, or profit margins fall short of forecasts, the currently seemingly cheap valuation could rise rapidly.The controversy surrounding Jensen Huang has added key-person risk to Nvidia, a factor that was historically rarely priced in by the market. Huang is not only the company's co-founder, but also the core decision-maker behind its product roadmap, customer relationships, industry investments, and AI strategy. Nvidia has long maintained a flat management structure, and the market has yet to see a clear successor capable of immediately stepping in. If the investigation ultimately does not affect his position or ability to perform his duties, the recent selloff is likely more of a short-term sentiment shock. Nvidia's advantages in its CUDA ecosystem, GPU performance, networking products, and customer base will not immediately vanish due to management controversy.

My Trade: I am patiently waiting for the $159 level before buying, although there is currently strong support levels at mid $160s

Takeaway: Nvidia's announced cumulative share repurchase authorizations total approximately $230 billion, providing the company with a capital buffer during periods of stock price weakness.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
N
NewUser_zS0M8w

"Jumpy" markets currently especially with chip stocks trading up and down pretty quickly within the span of hours. Some of them were actually down in pre-market and are now up by 3%. This signals that investors/traders are still divided over the overall market sentiment- you have the buy the dip buyers as well as the short sellers simultaneously.

N
NewUser_zS0M8w
Featured

$Hesai(HSAI.US)

Context: Q4: total revenue of RMB 1.1–1.15 bn which points to mild downstream demand. FY26: SGI revenue maintained at RMB 200–300 mn, with actuator modules contributing the majority. GPM target is close to 40%, while group opex is expected to rise approx. 20% YoY, with the incremental spend mainly on SGI R&D; ex-SGI, lidar opex declines YoY.

2027: SGI revenue targeted at approx. $100 mn (about RMB 700 mn), contributing 10%+ of total and likely breakeven in the same year. Group GPM is expected to be broadly stable, with clearer guidance to come next year. Total revenue of RMB 1.068 bn (+34% YoY), marks the 10th straight YoY gain. GPM was 41%, and GAAP profitability has now been sustained for six consecutive quarters.

My Trade: Bought into this when it was nearer to its peaks. On hindsight, it was probably wiser to wait for the pullback.

Takeaway: I'm still looking to go long for Hesai. I think the growth trajectory is still intact and I'm interested in their LiDAR solutions. Of course, this is a slightly riskier investment so not financial advice. @Captain's Treasure

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!