TWK-SH

TWK-SH

AssetsTop 47%
6Following0Followers3Likes & Bookmarks
T
TWK-SH

I expect Tesla's stock price to face downside pressure of over 7.5%, driven by the following core financial risks:

• Core profitability under pressure: Automotive gross margin slipped from 19.2% in Q1 to 16.3% in Q2, with intensifying industry competition squeezing margins further.

• High-margin regulatory items unsustainable: Sales of Regulatory Credits plummeted to $146 million in Q2; such high-profit revenue is unlikely to see a V-shaped rebound on the books in the short term.

• Cash flow deteriorating: As operating profits thin, massive CapEx remains required for AI computing power, Robotaxi infrastructure, and new factory development. Free cash flow (FCF) will likely remain negative or worsen further.

Conclusion: Unless Elon Musk can work another "miracle" in operations and earnings, the current valuation is hard to justify given near-term fundamentals.

C
Captain's Watch
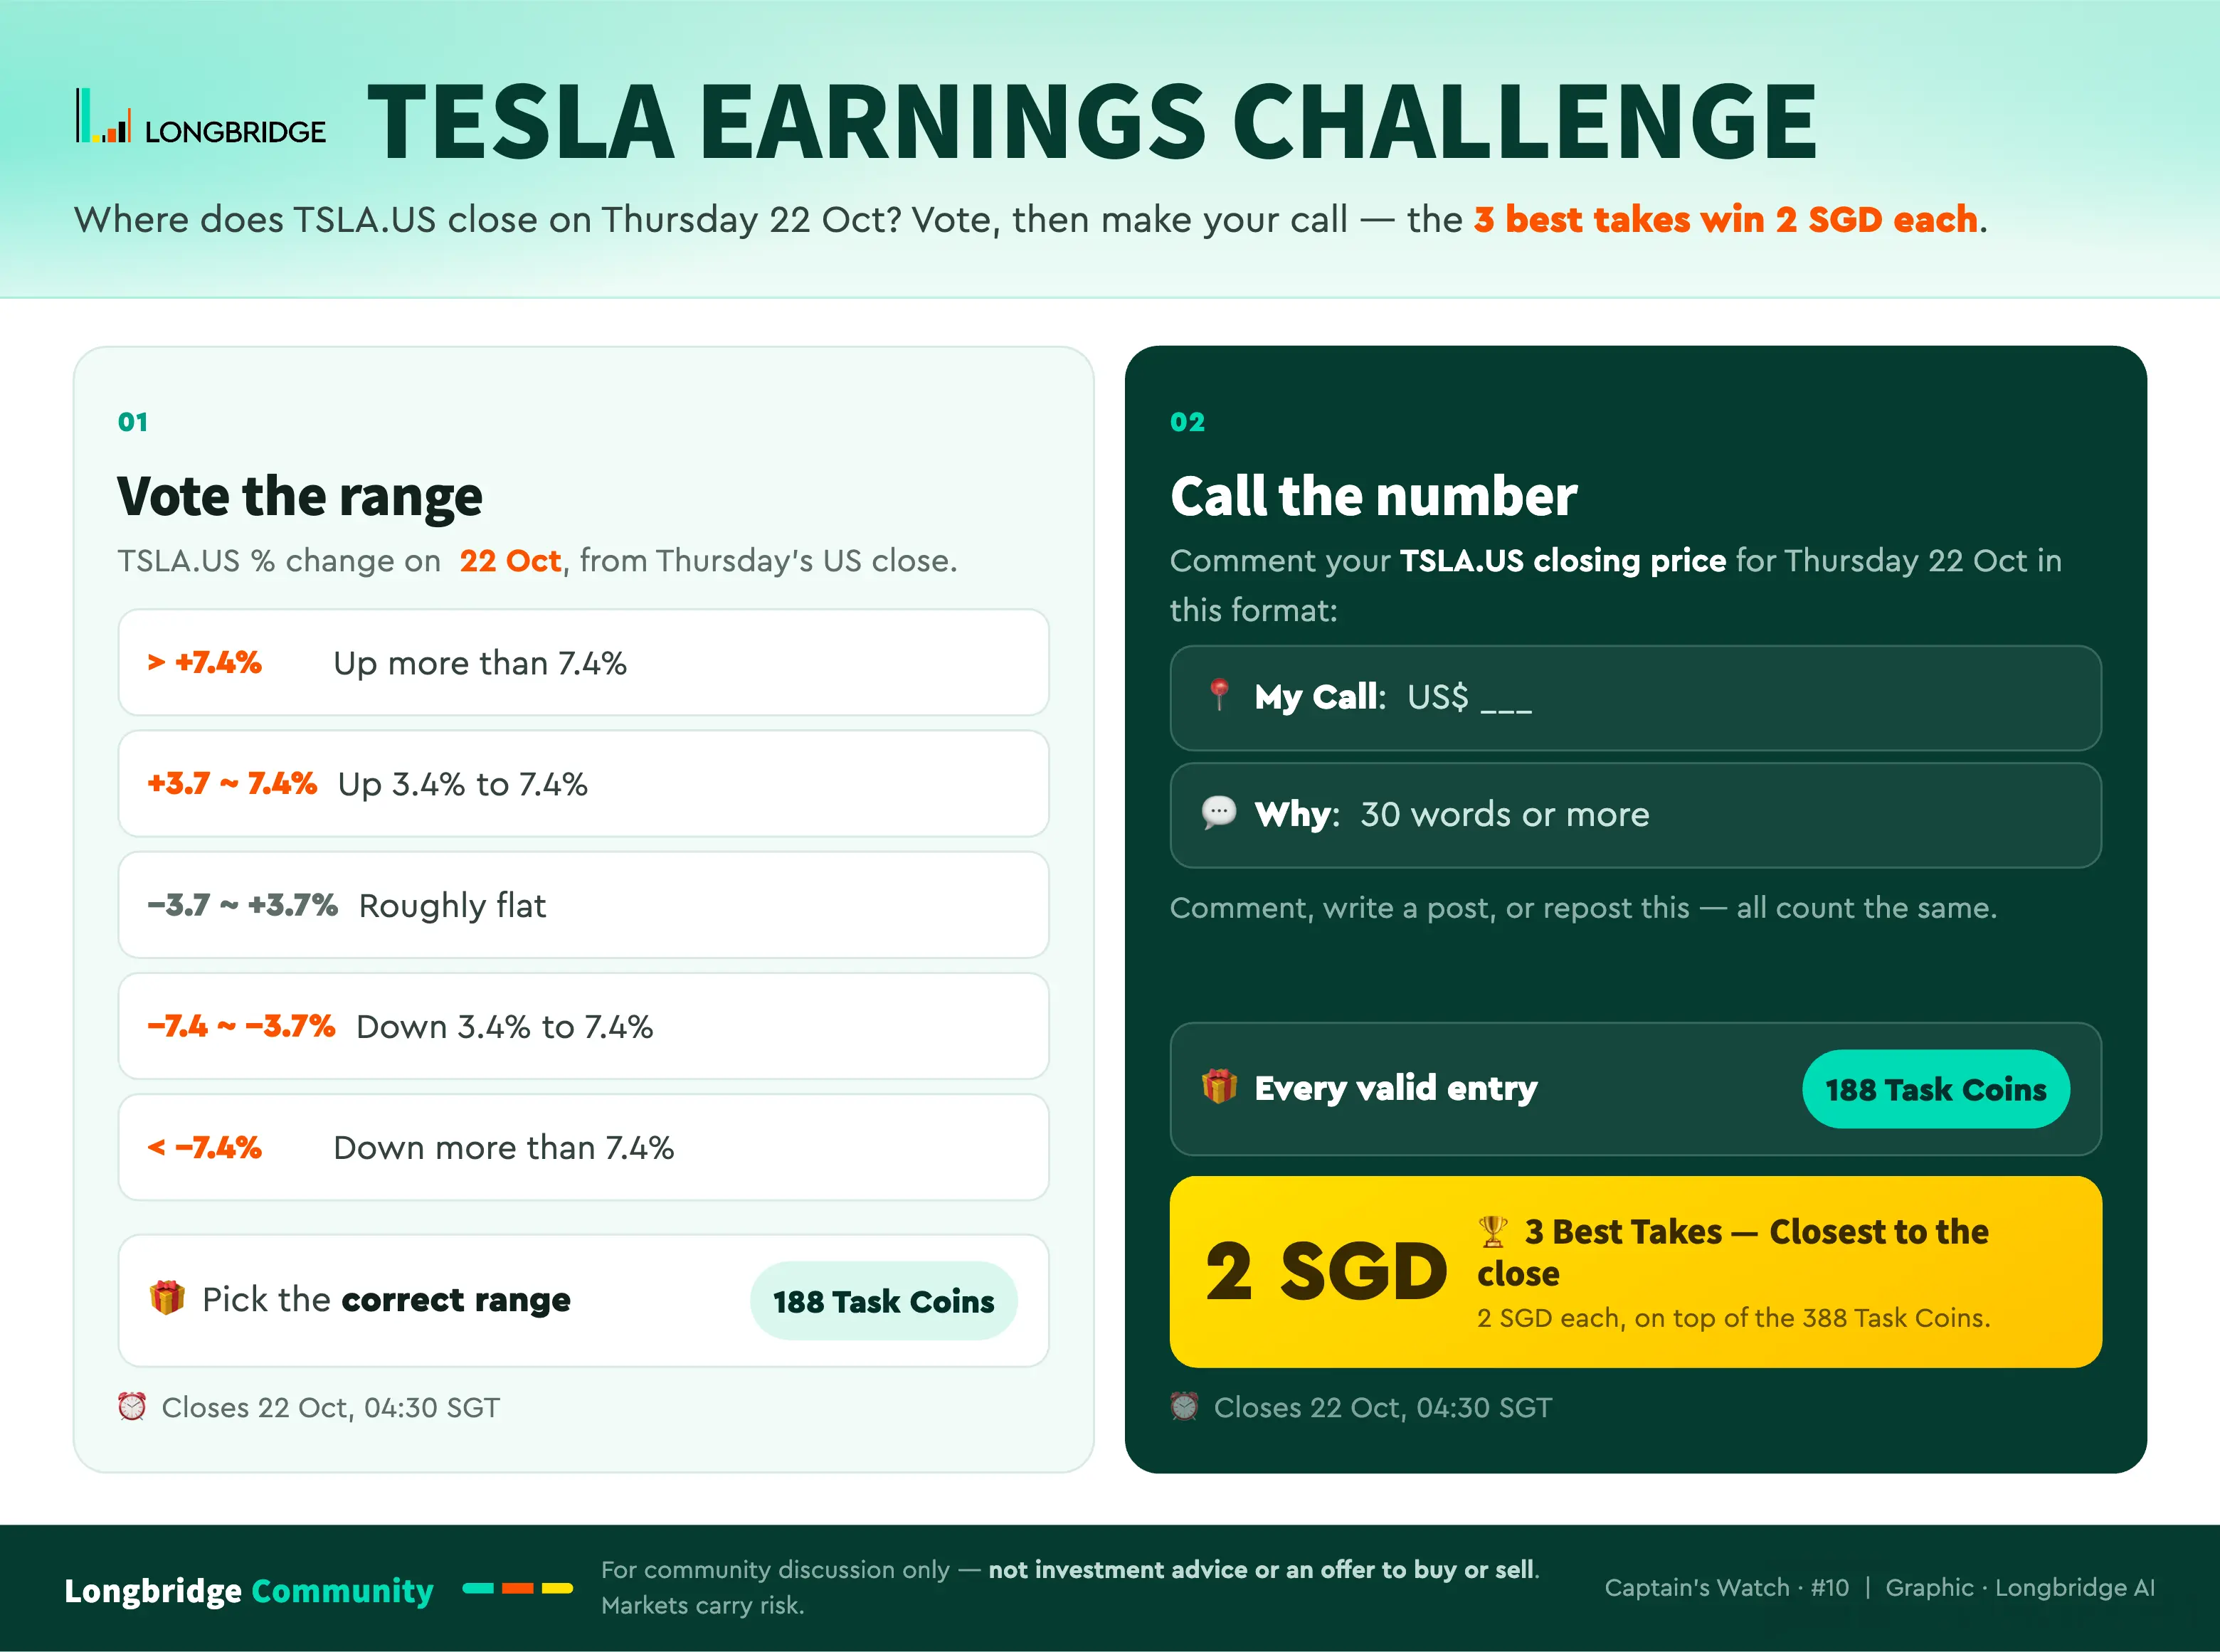
TSLA Earnings Challenge — Guess the close and win cash!

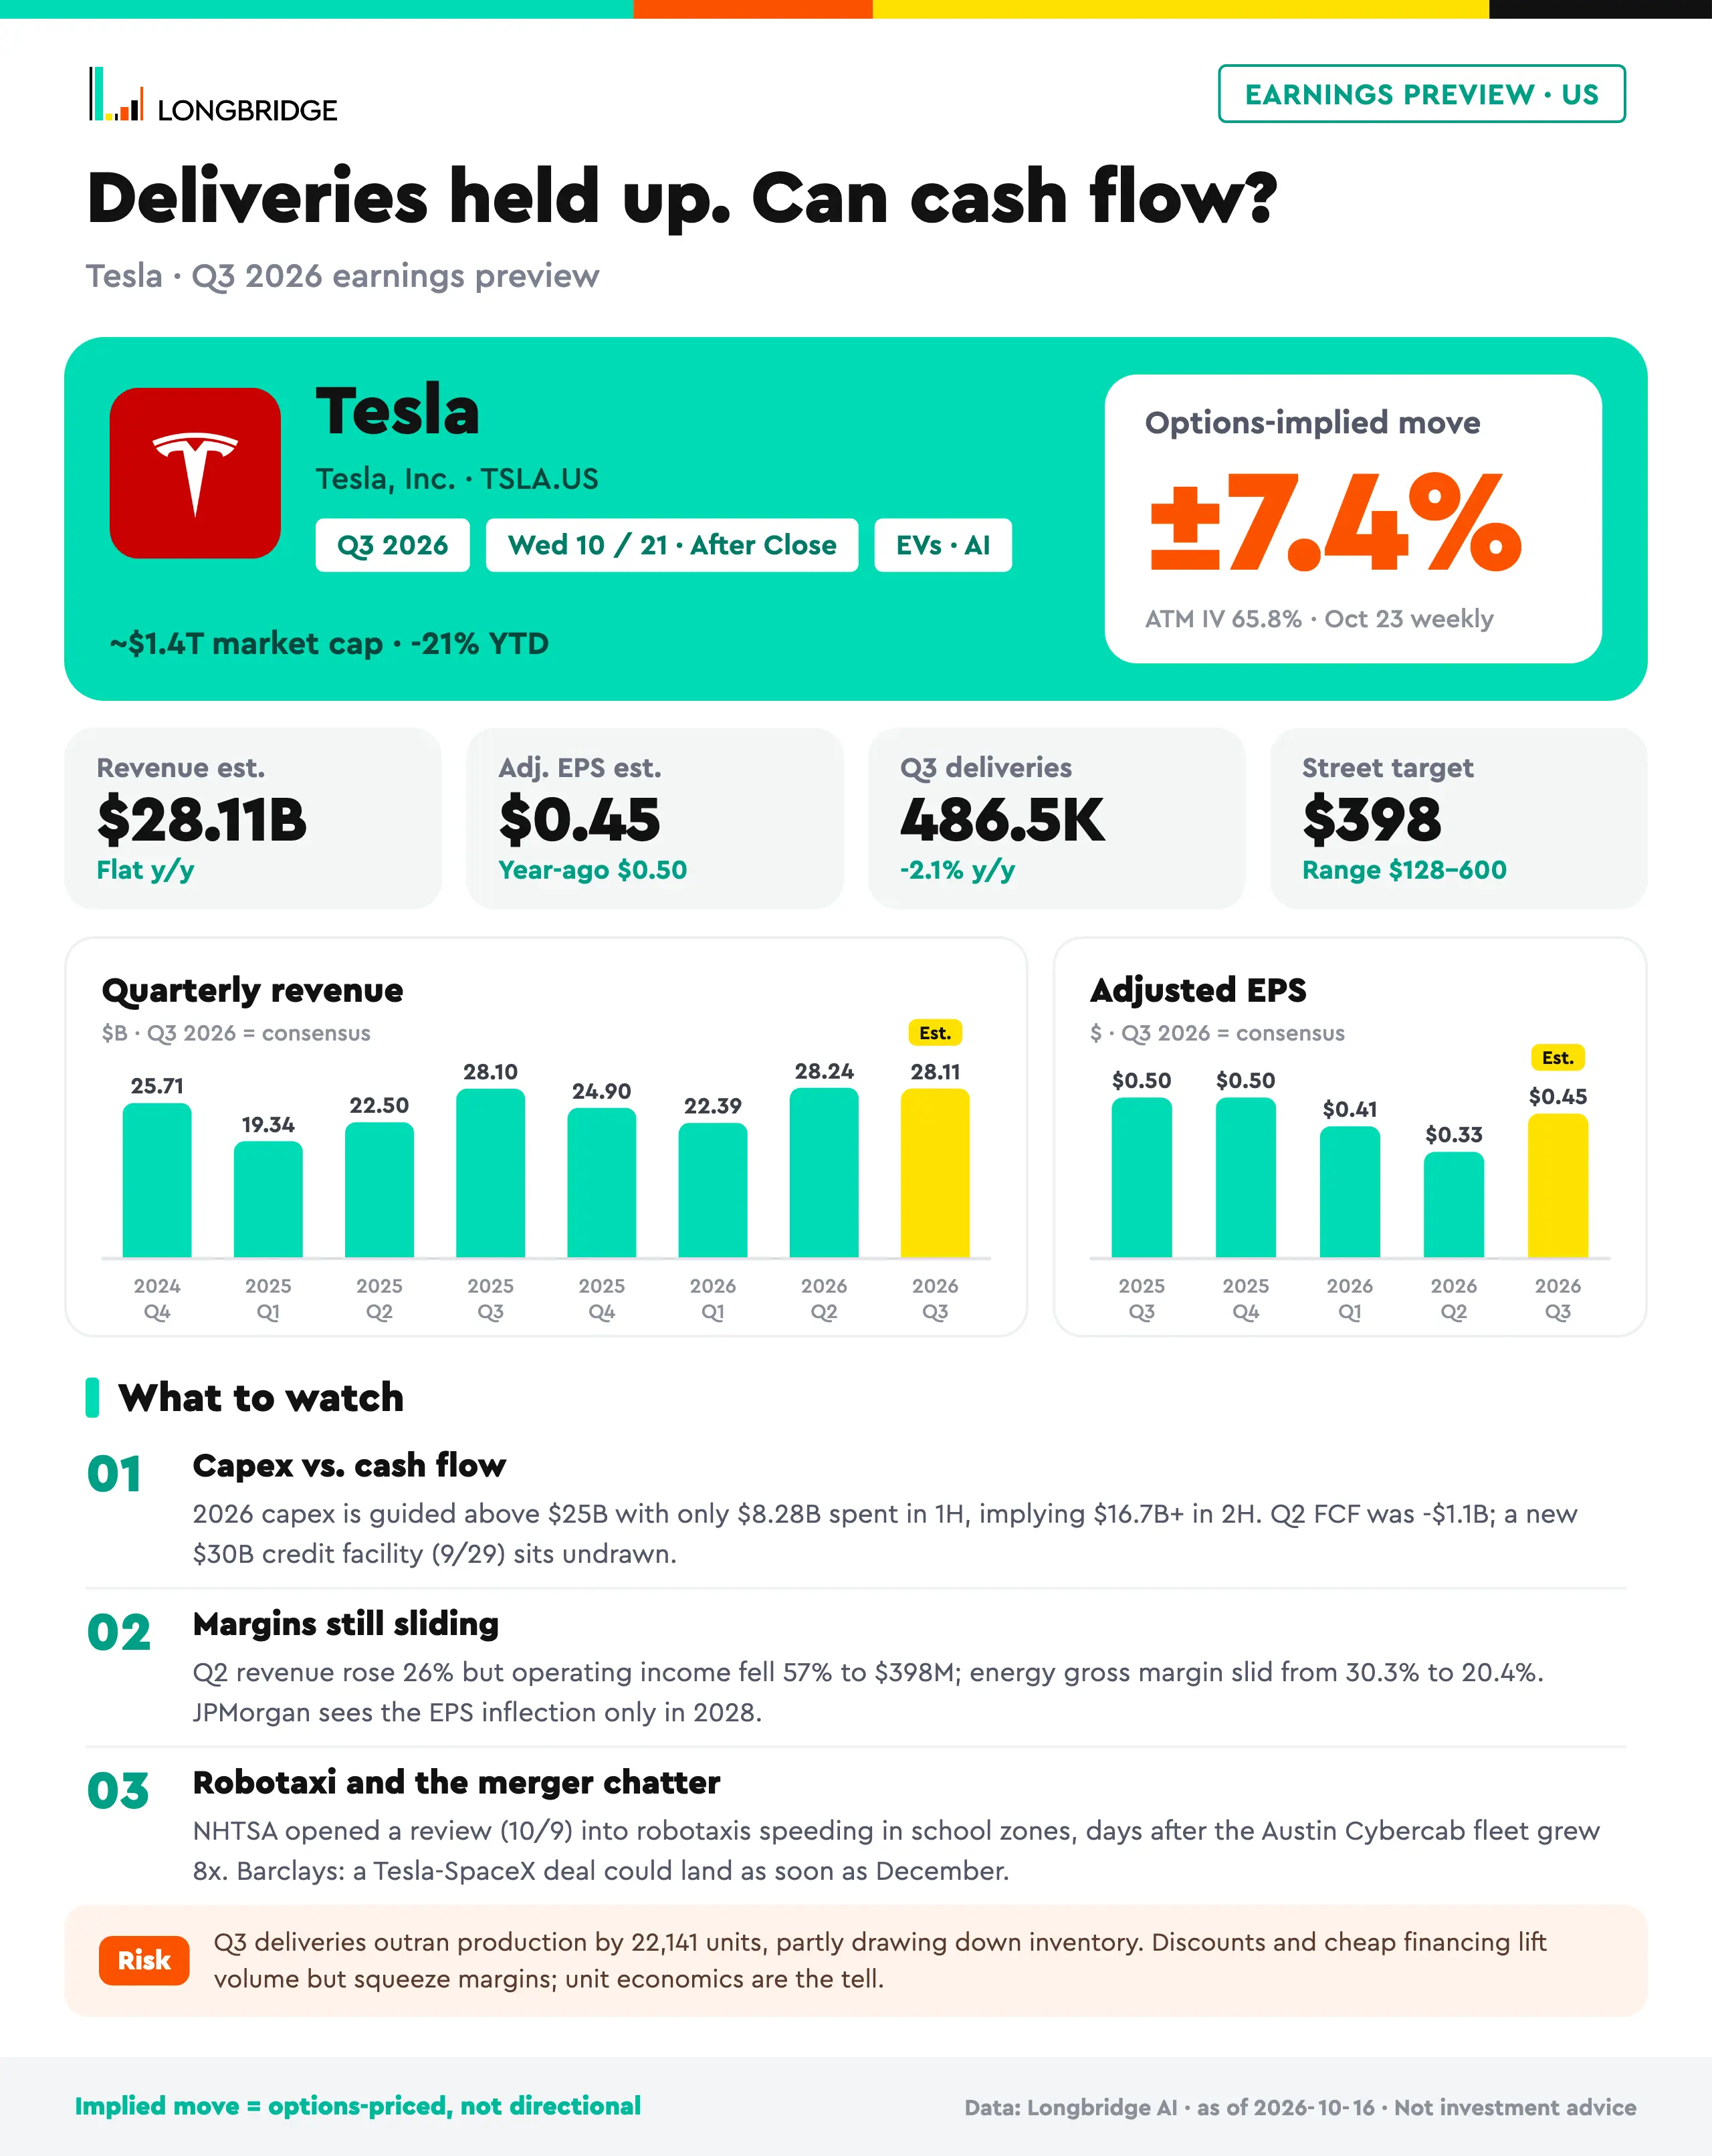
$Tesla(TSLA.US) reports Q3 FY2026 after the US close, Wednesday 21 Oct— the numbers land around 04:30 SGT Thursday morning, with the call at 05:00. ⏰ETFs:$TSLA 2X Long ETF(TSLL.US) $TSLA 2X Short ETF(TSDD.US) 📍 Wh...

EARNINGS PREVIEW·US 1 LONGBRIDGE Deliveries held up. Can cash flow? Tesla ·Q3 20
1 LONGBRIDGE TESLAEARNINGS CHALLENGE Where does TSLA.US close on Thursday 22 Oct
T
TWK-SH

SpaceX delivers a stellar report: $14.6bn in revenue drives $4.4bn in profit! This impressive result not only proves it is scaling up efficiently, but also showcases extremely strong profitability.

SpaceX has long since transcended the scope of traditional rocket companies. Space exploration, the Starlink satellite network, and potential AI opportunities are multi-pronged drivers opening up entirely new long-term growth space. The focus for the next phase will be observing how these high-capital-intensity businesses continue to convert into stable cash flow.

Observing the development of aerospace giants requires looking beyond short-term 舆论 hotspots and anchoring on deep commercial potential. Stay optimistic, stay patient, and look forward to SpaceX continuing to execute its vision powerfully!

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — SpaceX Turns a Profit and Opens Tesla Merger Talks

SpaceX made money for the first time, and immediately put a Tesla merger on the table. At home, the STI is up and the banks are leading. Let's dig in 👇💬 Would a SpaceX-Tesla merger be a good deal for ...

T
TWK-SH

Microchip (MU) @'s forward guidance serves as the definitive barometer for validating the quality of demand in the AI computing power chain. The explosive potential on its numerator side (corporate earnings and order demand) also represents the ultimate defense against valuation suppression driven by the denominator side (US Treasury yields fueled by PCE).

Given that its 2026 HBM capacity is fully locked in, market focus must shift from whether single-quarter revenue beats estimates to forward-looking capacity planning for FY2027, the proportion of long-term agreement prepayments, and customer validation milestones for HBM4/HBM4E. Simultaneously, close attention should be paid to the 'crowding-out effect' of HBM's siphon effect on traditional DRAM. Only when supply tightness successfully transmits to the average selling price (ASP) of general-purpose DDR5/LPDDR5X will the structural rise in gross profit margin provide a long-term margin of safety.

Furthermore, rationally filter out the financial noise caused by the current quarter (14 weeks) impacting next quarter's (13 weeks) QoQ guidance. If the market experiences irrational declines due to next quarter's revenue guidance appearing 'soft' on the surface because of fewer natural weeks, this precisely presents an opportunity to left-side position for long-term fundamental layout while filtering short-term volatility. As long as Microchip's guidance confirms that the memory industry has officially evolved from a 'traditional cycle story' to an 'AI long-term infrastructure story,' its low forward P/E provides a substantial margin of safety, sufficient to hedge against beta risks from tightening macro liquidity.

To apply this core logic more precisely to your actual operations, you can tell me:

• What are one or two other semiconductor stocks with the heaviest positions or highest attention in your current portfolio?

• After Microchip releases its earnings guidance, do you need a multi-scenario (Bull/Bear Case) contingency plan for these holdings?

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — PCE Tests the Fed, Micron Tests the Memory Boom

Fed's Williams saw "no need for urgency" on the next hike, cutting October odds to a coin flip ahead of tonight's PCE. Then Micron reports before dawn Thursday, with Street targets from $1,100 to $2,0...