
Wow. WTF?!
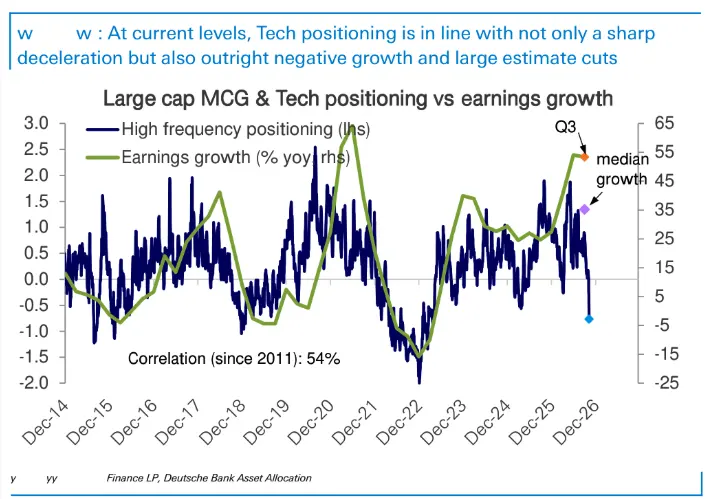
Investors are currently positioned as if Tech companies are reporting NEGATIVE earnings growth for Q3!This compares to Q3 growth for Tech of 53% in aggregate and 35% for the median company!IMO, this is probably a good spot to start re-building some longer-term tech investments.This week's selloff (and current positioning levels) is not a true reflection of Tech's future earnings growth.
Paradi Lab
P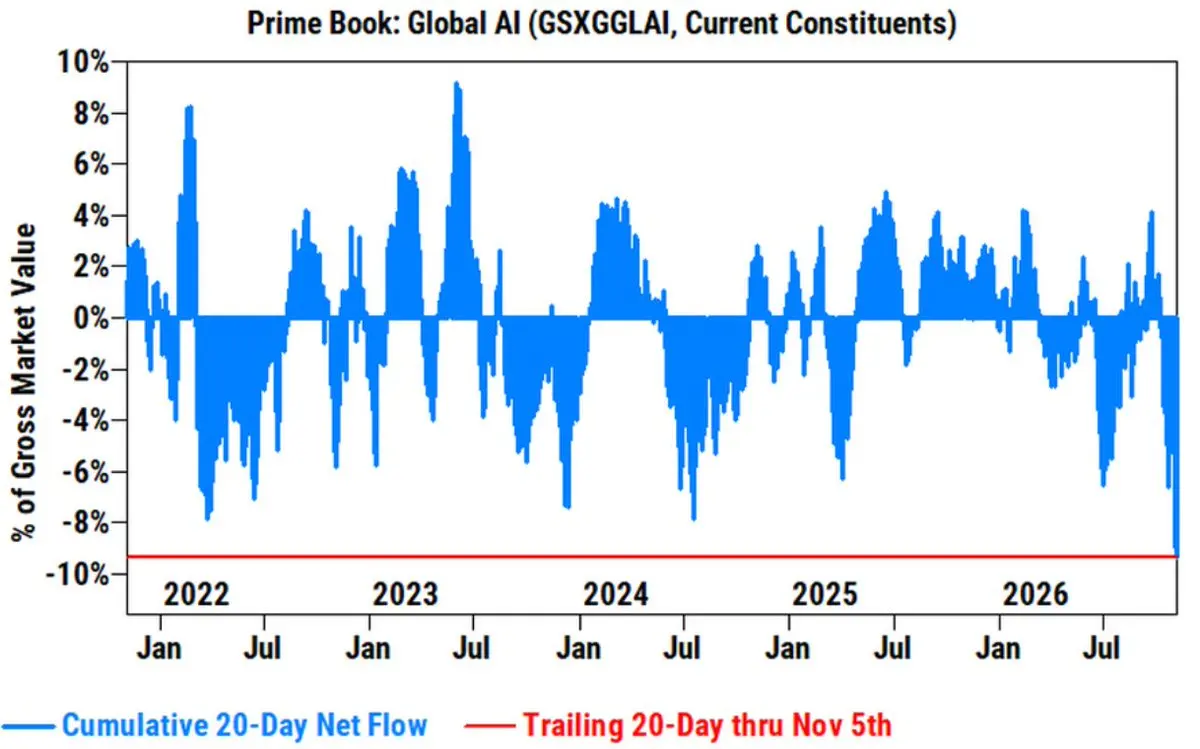
Absolutely staggering.
HFs have been selling AI stocks at their fastest pace on record according to Goldman Sachs.HFs have actively unwound risk in the past month.More specifically, TMT funds are now ~flat YTD, down from roughly +24% generated in H1 before the Leopold sell-off in July.There have been three big semis sell-offs this year:March, July, and now Oct-Nov. A lot of pain endured.I wonder the extent of risk budget cuts at HFs?What incentives remain for HFs to add risk so close to year end?That said, HFs are positioned *even* lighter than a ~month ago, so a rally could force some short covering.Feels like retail (and any buybacks) need to do the heavy lifting short-term.P![图片 1,共 1 张]()
JPM Memory Market Update:
The order visibility is extending as we progress through the year, but we believe the market is anticipating AI funding risk and power bottleneck driven memory downcycle as early as in 1H27E. This puts memory in a tricky spot as investors debate between “too-cheap to ignore” vs. “it is cheap for a reason.” We believe EPS cuts are unlikely to happen in the next 6M as the memory S-D gap is too wide to narrow over a short period of time and memory earnings will have a buffer protected by LTAs and prepayments.On a medium-term basis, we continue to view risk-reward as attractive and remain OW across all our coverage companies and rank our next three months order of preference based on shareholder return policy upside: SKH (OW) > SEC (OW) > Kioxia (OW).P
A Democratic sweep at the Midterms is largely priced in IMO.
During the 2024 Presidential elections, equity positioning was at similar levels to now and was tracking closely to earnings growth. Higher earnings, higher positioning.However there's currently a mis-match where earnings growth is significantly higher large-cap equity positioning per Deutsche.It therefore feels like ongoing geopolitcal tensions and negative tech sentiment are the bigger overhang on stocks right now.Both are dancing together in the eye of the storm which we saw yesterday with an initial "Brent down, S&P up" move that later got reversed as people remembered their lingering AI financing concerns.For the past 5-6 weeks, prediction markets have suggested a Democratic sweep, and as of this morning, Polymarket gives the Democrats a 95% chance of winning the House and a 79% chance of retaking the Senate.However, I would still expect volatility through the day particularly with the AI complex so highly levered toward U.S. government policy combined with back-to-back weeks of downside pressure.Doesn't seem like a tasty cocktail (to me) despite Semis currently trading higher pre-market.P![图片 1,共 1 张]()
$Lumentum(LITE.US) & $Marvell Tech(MRVL.US) Scenario Analysis & Explanations:
TLDR: Lumentum brings ~a third of the combined profit to the Marvell deal and gets ~a third of the company. Why would a business more than doubling its revenue accept that? There's no real premium on what it brings!!!! 🚨* Each cell compares Lumentum holders' share of the combined company's profit vs. what they'd have kept if Lumentum stayed independent.** Red cells = Lumentum holders are worse off in the deal. Green = better off.*** n/m = Lumentum makes a loss on its own, so a % comparison isn't meaningful.Explanations:- If Lumentum keeps growing, shareholders lose in every column: −12.5% if Marvell hits its $20B FY28 outlook, −33% if Marvell stalls, −43% in a downturn.- If Lumentum just holds today's level, holders only win if Marvell hits $20B (+17%).- If Lumentum's margins fall back to last year's 15%, the deal protects them: +46% to +188%.This kind of shape is normal...every all-stock deal looks like this. You swap 100% of your company for a fixed slice of a bigger one, so you give away some upside if your company outperforms and get cushioned if it doesn't. Again, normal.-> What's NOT normal is where *today* sits on the grid!!!! 🚨Usually the target is paid a premium on top of what it brings. That shifts the whole grid green, so holders still win if their company keeps performing.Here, Lumentum holders get ~33%, and Lumentum already earns ~31% of the combined profit (~35% on next quarter's guidance).There's no real premium. The breakeven sits right at today!!!!! 🚨🚨🚨For comparison, here's how the grid changes if they'd got a 40% stake:- Keeps growing + Marvell hits outlook: −12.5% becomes +6%.- Holds today's level + Marvell stays put: −14% becomes +4%.-> Why so little?1. The $1,132 / 23.9% premium announced today was over Lumentum's share price, which already valued Lumentum more cheaply than Marvell for the profit it makes.2. So the premium only got holders to their fair share, not above it.3. And it's paid in Marvell stock at a fixed ratio: with Marvell down ~30% since the leak last week, it's now worth ~$800, below Lumentum's pre-leak price.-> Feels like the trend is against them too.1. Lumentum's share of the combined profit has gone from a loss in mid-2024 to 9%, 27%, 31%, and ~35% next quarter.2. The 33% is fixed, so everything above it goes to Marvell holders.3. Even if Marvell delivers, Lumentum only needs ~26% more profit than today's run-rate to cross into the red, and its own guidance shows ~36% growth in a single quarter.IMO Lumentum management thinks current margins are unsustainable and that CPO hands power to companies like Marvell.If they're wrong, they sold the fastest-growing part of the combined company for roughly what it contributes... while its share was still rising......!!!!!![Non-GAAP operating profit from company filings and guidance. Scenarios use Marvell's own FY28 outlook]P
$Marvell Tech(MRVL.US) to acquire $Lumentum(LITE.US) in an all-stock transaction.
- Implied enterprise value of $115 billion for Lumentum.- Lumentum stockholders will receive 4.5 shares of Marvell common stock for each share of Lumentum common stock.- This represents ~$1,132 per share of Lumentum common stock and a premium of approximately 23.9% based on each company’s price as of October 28, 2026.- Marvell stockholders will own ~67% of the combined company. Lumentum stockholders will own ~33%.- Matt Murphy to remain as CEO of the combined company.- Transaction expected to close in H1 2028, subject to shareholder and regulatory approvals.P![图片 1,共 1 张]()
Insights from GS Prime Brokerage:
1. Info Tech was the most net-bought sector this week, driven mainly by short covers while long buys remain relatively weak.2. Info Tech stocks are still heavily net sold MTD. This week's net-buying through to Thursday represents just ~40% of what HFs had sold in the previous 3 weeks.3. Mag 7 stocks were net sold from Tuesday to Friday last week, highlighting risk-off sentiment.4. Semis & Semi Equip (long buys), Software (short covers), and Tech ETFs (short covers) were the most net-bought Tech subsectors this week.5. Goldman Sachs: "While the directional engine of this market remains intact (token demand + GW/DC build-outs), the market has become much more discerning around the linearity of this story beyond CY27, pressuring multiples across the board until visibility improves, while investors are struggling to find names to rotate into outside of Semis/AI that are less susceptible to daily AI disruption volatility – cue names like IBM, AAPL, SPOT, V/MA, EBAY, LYV all trading well on the week/month."P![图片 1,共 1 张]()
Absolutely insane...
HFs have pulled back gross exposure by ~8% -- the most aggressive de-grossing in at least ten years -- according to Morgan Stanley’s Prime Brokerage data.In addition, TMT-focused HFs lost ~12% in October with losses concentrated in crowded Tech names -- according to Goldman Sachs Prime Brokerage.HFs are cutting both longs and shorts to protect their solid YTD gains (and bonus packages) accrued in H1 2026. That unwind reinforces selloffs in crowded stocks, which is why Amazon, Google and Intel saw violent sell-offs.P
Oh no...
$Amazon(AMZN.US) Q3 EARNINGSRevenue: $201.9B vs $202.31B 🔴EPS: $1.89 vs $1.96 🔴Q4 Revenue Guide: $240B-$247B vs $244.51B 🔴P
Initial notes on $Marvell Tech(MRVL.US)'s rumoured $Lumentum(LITE.US) acquisition:
1. Why?!- $Lumentum(LITE.US)'s CEO has said they're sold out into 2029. So do management think the InP laser shortage is shorter than what their orders suggest? Need more clarity on why Lumentum would green light this.- With lasers sold out into 2029, I think owning the fab might be the only way $Marvell Tech(MRVL.US) can guarantee supply for FY28 growth. So maybe Marvell and Lumentum have different reads on the InP laser shortage?2. This has to be mostly stock.- $Marvell Tech(MRVL.US) has ~$3.9B cash vs. $5.0B debt. Combined run-rate EBITDA is circa $7-7.5B (my numbers), so I think staying investment grade caps new debt at around $15-20B.- At a ~30% premium that leaves $85-90B+ paid in stock, with $Lumentum(LITE.US) holders owning ~30% of the combined company.- I feel that’s a lot of Marvell to hand over.3. I think the strategy is much better than the reaction.- $Marvell Tech(MRVL.US) are essentially buying the part of the optical link that survives the move to CPO which is a pretty smart hedge on their own DSP franchise. - Marvell announced Inphi around 6 years ago (~$10B in cash + stock), and that deal built the core of MRVL's optics business. - This is basically the same move just one layer down, from DSP to laser, stacked on Celestial AI. - Probably a good signal that Marvell are running the same optics playbook again?4. Dilution.- $Marvell Tech(MRVL.US) trades on about 52x run rate EPS. - $Lumentum(LITE.US) is about 60x on its FQ1 guide at tonight's AH price and about 70x with a 30% premium. - That's ~15% dilutive to Marvell's run-rate EPS (my rough napkin math number) assuming a 30% premium, ~$17.5B of new debt at ~5%, and the rest in stock at $228. (Again, very rough numbers).- It only turns accretive if Lumentum keeps outgrowing Marvell at today's guided rates (+24% q/q vs +15%) for another five or six quarters. - I think that's achievable while the laser shortage lasts, but I feel the whole deal ends up being a bet on how long that is.5. Fewer lasers on the open market. - If LITE's output gets prioritised for $NVIDIA(NVDA.US) and Marvell's own modules, everyone else buying LITE EMLs and CW lasers gets tighter allocation. - I think that's bullish for laser pricing at $Coherent Corp.(COHR.US) and for other laser sources like $SIVE (lol).- Feels like the module makers that depend on LITE lasers are the quiet losers.6. Channel conflict. - Marvell is the leading DSP supplier to 800G/1.6T module makers, and LITE already sells its own modules through Cloud Light. - I think Innolight and Eoptolink start shifting DSP share to $Broadcom(AVGO.US) and $Credo Tech(CRDO.US)?- I feel hyperscalers will push harder to second-source lasers from $Coherent Corp.(COHR.US).P
Quick market thoughts:
Today was a dead cat bounce?Background context: Hedge funds still seem heavily underweight tech relative to consensus Q3 earnings growth. The recent unwind has flushed out crowded positioning, cut concentration and brought multiples back towards more "normal" levels across Tech/Semis. So while recent weeks have been painful for many people, I think this ultimately leaves positioning in much healthier spot to rebuild longer-term.Moving onto today specifically: Today's flows still show Tech being sold and overall very low activity levels across the board (GS). This is highly typical for the past ~month where bounces higher are mainly due to less fast/urgent selling (i.e. HFs de-grossing) rather than buyers buying....There's nothing to suggest that risk has been added yet.That said...I do feel like we're getting close to the end of this unwind now especially with hyperscalers sticking to capex plans & Q3 semis earnings likely to be positive.P![图片 1,共 1 张]()
Why do Semiconductor stocks keep falling even though fundamentals remain strong?!
Here's why:TLDR; The Semiconductor industry consumes a massive 20% of the total risk capital in the global equity markets.The current share of risk capital for the Tech sector in the broader Global MSCI ACWI index is 40% vs. its 28% market cap weight. Of this, Semiconductors account for 20% vs. their 13% market cap weight.Semis' market cap weight has risen rapidly in 2026 and because they're more volatile than the broader market, their share of risk runs well ahead of that weight. Therefore, investors are far more exposed to the Semis industry than even the index weights suggest. This concentration then changes how the entire sector trades, where most of these selloffs are positioning events - not fundamental-driven.Steady inflows into equities and thin net equity supply have kept realised vol low. Funds that size positions off VaR or vol-targeted risk budgets respond to low vol by running bigger gross exposure. When vol picks up, the same models force them to cut positions.Then like a snowball rolling down a hill...that selling lifts vol further which forces the next round of cuts. (It works the opposite way too).So with ~20% of the global risk budget sitting in Semis, these stocks are the first thing sold whenever risk models flag any shocks...even if fundamentals remain robust.Data: JPM Global Markets StrategyP
Quite surprised that AI stocks are red considering how strong SpaceX and Meta's earnings were.
Fundamentally, both proved that there's zero issues on the demand-side which is a positive step in helping sentiment.It therefore seems like the current macro hurdles are too significant for investors to re-risk and chase upside based solely on EPS growth.Chop city.P
Quick thoughts ahead of $Meta Platforms(META.US) earnings shortly:
Key question: What does the monetization roadmap look like for Muse?Despite app downloads showing that AI capex is translating into real demand, my gut feeling is that Zuck will give a more hollistic view on AI monetization that lacks any real detail.This ultimately boils down to Meta's strategy of scale first, monetize later.Which then raises the usual capex questions particularly with Meta now positioning themselves as a frontier AI lab with their new Muse Wonder models. They'll need more compute if they're really taking this AI thing seriously.The current FY26 capex guide is $130-145B, so any increase to this without a clear AI monetization roadmap could be detrimental if I take a glass-half-empty view...particularly with consensus FCF deeply in the red at roughly -$9B for Q3.So how do Meta finance this exactly? Is it via their Blackrock agreement, or some combination of debt/equity? Again, something we'll need clarity on, layered on top of their monetization plans.I ultimately think that Zuck needs to really sell the longer-term AI vision today.P
Once again, the GPU depreciation bear thesis is dead.
Elon on the $SpaceX(SPCX.US) call: "The value of compute per watt will increase over time, not decrease... that's why you see things like even old computers like H100s renting for more than they rented when they were new."When supply is this constrained, GPU rental prices are set by the value of the marginal token, not the replacement cost of the chip.Models keep getting better, and better models raise the value of every installed watt faster than new GPUs deflate the old ones.Various datapoints all stack up:-> $SpaceX(SPCX.US) says compute contracts are renewing "at higher dollars per watt, not lower dollars per watt"-> 1-year H100 contract pricing went from ~$1.70/hr to ~$2.35/hr between Oct 2025 and Mar 2026 (a 2022 chip!)-> $Coreweave(CRWV.US) signed an A100 contract running into 2029 (a 2020 chip) and said older-gen pricing is at / above a year ago, and raised list prices ~25% in July.-> $Nebius(NBIS.US)'s first Blackwell auction cleared 15% above its previous high and as a reminder....they told customers H100 on-demand goes up ~17% (from Oct 1).-> Zuckerberg: $Meta Platforms(META.US) is getting offers for its compute "at a significant premium over what we paid for it".-> Lenders are now lending against GPUs out to 2030 e.g. $Nebius(NBIS.US) borrowed against its GPUs at SOFR+250 in July.Feels like the 2-3 year GPU useful life bear thesis keeps getting setback. Ofc, the one thing that ruins the party is the S/D gap closing -- Rental prices fall back toward replacement cost + older GPUs get repriced on perf/W. Which won't happen anytime soon.P
For AI/Semis stocks, it feels like every earnings season becomes signficantly more important than the last.
This time is the same, but for different reasons which has led to market chopiness: - Macro instability (Iran, oil, yields, inflation)- Midterms- $Coreweave(CRWV.US) credit stress- AI ROI concerns via frontier lab ARR's (& pending hyperscaler earnings on top).Today: $SpaceX(SPCX.US) Wed: $Meta Platforms(META.US), $Texas Instruments(TXN.US), $Lam Research(LRCX.US) Thu: $Bloom Energy(BE.US), $Western Digital(WDC.US), $Nokia Oyj(NOK.US) Let's see if good EPS will be enough to turnaround sentiment.P
Feels like shorting Taiwanese AI stocks is probably a good hedge right now.
Positioning remains extremely elevated = highly exposed to short-term downside.Just look at how the market responded to $Taiwan Semiconductor(TSM.US)'s awesome earnings/guidance....-2.5%.P![图片 1,共 1 张]()
Rough.
Hedge funds have net sold Global AI stocks for five consecutive sessions (Oct 8 - Oct 14). From a flow perspective, all of the cumulative net buying in this group since the start of 2025 by HFs has now been unwound.Source: GS FICC & EquitiesP
Memory fundamentals are still very strong (stronger than Q1).
$Micron Tech(MU.US) CEO: - "We expect memory and storage supply demand conditions to be much tighter in fiscal 2027 and 2028 than they were in 2026." - "We do not have line of sight to when supply and demand will return to balance."Back in July, $NVIDIA(NVDA.US) supply commitments rocketed from $119B -> $279B which was "primarily related to the procurement of memory", with ~$175B of commitments for 2028-29...$Micron Tech(MU.US) also said that >75% of FY27 output is already committed + "a majority of discussions with our customers today are already around 2028." So as a reminder....ultra long-term demand visibility in the context of the memory market.Samsung’s Q3 prelim last week was 107.4T Won O.P. on 195T Won revenue:- So that's ~55% margins company-wide. - Micron did 87% GM in their most recent quarter- $Sandisk(SNDK.US) 84.6% GM. All accelerating/stabilizing margins as of their most recent fiscal Q's.Mass production from new capacity (from Micron, Samsung and SKHY) is also not expected to come online for quite some time.In other words, the shortage will intensify next year at least.Then long-term contracts solidify long-term earnings further via price floors + committed volumes:- $Micron Tech(MU.US) with 26 SCAs worth >35% of revenue through to 2030 with some now running into 2031. - $Micron Tech(MU.US) CFO: "even at floor prices, we expect margins meaningfully above any prior cycle peak margins."- $SK Hynix(SKHY.US) has ~10 LTAs of ~5 yrs w/ pricing structures "designed to respond to price fluctuations."- Sammy (as of recent reporting) holds ~70% of memory capacity under LTAs until 2031 with $Microsoft(MSFT.US), $NVIDIA(NVDA.US) and $Alphabet(GOOGL.US), with ~25% of contract value prepaid.- $Sandisk(SNDK.US) also has their "New Business Model" agreements with 8 customers that lock in ~66% of fy28.Then on buybacks, $Micron Tech(MU.US) will step up returns from December - "over time, we expect to return 100% of our excess cash." Just crazy how much cash these companies are bathing in rn.Obviously there are risks, mainly with positioning and sentiment towards the AI trade currently - thanks to macro/ARR fears/pacing talks/other stuff I'm probably forgetting rn.China is ofc another risk with CXMT but I don't see how they'll be a massive problem for HBM / US hyperscaler RDIMM where they'll continue to face US restrictions + massive qualification walls imo.But ultimately, memory fundamentals are in-tact and very strong. Stronger than Q1.P
FYI, U.S. tech was the most net sold sector this week thanks to the OpenAI ARR scare.
This breaks the trend where U.S. tech was the most net bought sector in the 4 weeks before.Investors rotated capital away from Semis into Software...or as I like to say "defensive tech".My prediction from ~6 weeks ago around market choppiness has proven to be correct....but I cannot emphasise enough how crucial the next few weeks are:1. CPI on Wednesday = rates read-through.2. Earnings for big tech and semis.3. Midterms = potential for easing Iran tensions.My position on where we go from here should be known by now I hope -- a rally into 2027 as we jump over the above hurdles. But it makes a lot of sense to keep some cash to ride the incoming volatility.Not financial advice.P
With the Singapore Grand Prix in a few hours, I can't help but draw comparisons to the financial markets and the AI trade.
One slow pitstop or a miscalculated overtake can undo weeks of preparation and cost millions of dollars.So with AI and semiconductor earnings fast approaching, it feels like we need a quick pitstop to get the race back on track.Rates remain high. Oil prices are elevated. Fresh frontier lab ARR concerns. AI capex. Circular financing.....all create some dark clouds which have resulted in de-risked positioning and low sentiment.Similarly, consumer confidence is low. New research from Morgan Stanley finds that net sentiment from Americans towards AI is at +14% compared with -20% for data center construction, with water requirements and environmental concerns among the biggest objections.It therefore seems like AI policy will become an even bigger stumbling block in the years to come...But the positive is that business fundamentals have remained strong highlighted by recent sold-out comments from $Micron Tech(MU.US) and $Lumentum(LITE.US) CEOs. Plus $Taiwan Semiconductor(TSM.US) reporting 55% YoY revenue growth as the de-facto proxy for the wider AI trade.My beloved Chelsea won 5-1 yesterday. But conceding even just 1 goal won't be good enough for the AI trade. With sentiment at fresh lows, I feel like all the key infrastructure companies need to report without any hiccups.P
Hi @sama and @DarioAmodei,
You need to disclose your ARR metrics. Urgently.I don't think it's fair on the CEO's of publicly listed tech companies (NVDA, AMD, MU etc.) to see their share prices nuked by Billions of $ due to incorrect/rumour-filled reporting around your financials.It's the right thing to do. Everyone wants clarity.Thanks,ParadisPS: It's also not fair on my portfolio.P
Winter is coming.
The first three quarters of 2026 have been truly insane for the markets. But it's fair to say that the AI trade has cooled off a bit in recent months.So yes, the days are getting colder and shorter. Winter is coming. But is it coming for the AI trade?Well...other than the Leopold deleveraging in July, macro has acted as a major overhang on what would otherwise be an earnings-driven bull market. Despite September's institutional flows into Tech keeping the market elevated like Wingardium Leviosa (any Harry Potter fans here? 🧙♂️), we're yet to see any huge risk be added even with institutional leverage rebounding close to 2026-average levels.(Slight breakaway - that metric is one I will monitor closely to see if we get to July levels again)I therefore continue to believe that there's substatial headroom for the AI trade to continue as we head into earnings. However, investors are largely waiting for major macro hurdles to pass - specifically oil and rates, with the 10Y at multi-decade highs.All of this matters, and is why I personally choose to ignore investors that say "macro doesn't matter" when it has dictated the course of financial markets since the dawn of time. (Quick rant over)The most recent payrolls data definitely gave some ease to Fed hike odds, but we're not past hiking-territory yet with rates still skyhigh and CPI coming up soon. All of this leaves a ton of lingering uncertainty that wasn't there earlier in the year even at the height of the Iran war just as the AI trade and earnings growth lit the initial fire under the market.However, we're coming into earnings season now with many AI-related stocks (semis, semicaps etc) currently mispriced imo.Since there's clearly underlying demand for tech stocks (see my previous flow posts)...I wonder if we'll start to see some re-ratings occur as a front-run into earnings. Or...if the macro landscape is still a bit too treacherous.I keep my prediction that we'll see an AI bull market heading into 2027.Time will tell.P
Hedge Funds and Asset Managers showed increased demand for Semis this week.
In fact, US Tech stocks were the *only* net bought sector in September as long buys outpaced short sales by over 2:1.This level of buying was driven by some big catalysts this week, specifically $Micron Tech(MU.US)'s earnings and $NVIDIA(NVDA.US) buybacks.However, prime broker data shows that Semis demand isn't absolutely skyrocketing yet and there's significant headroom for institutional positioning.After speaking with many investors over the past week, I would say that there's some anxiety around putting more chips in on the AI trade.I think this is due to a few factors that are currently in-play:1. Macro shitshow - Iran, oil, rates situation.2. Midterms.3. Constant shifts in the AI story (tech is moving faster than investors' brains).That said, we're coming up to Q4 earnings in Tech/Semis Land...all while forward tech/semis valuations are relatively low right now.So I think the issue now centers around whether we can see a re-rating in Semis as we start to see positive Q4 earnings/guidance despite the current macro and midterm hurdles.If we can get past those hurdles unscathed, then I think my prediction of a tech rally into 2027 looks highly likely as institutions size up for 2027+.P![图片 1,共 1 张]()
After the Leopold/SALP deleveraging in July...
Leverage being used by hedge funds and asset managers has rebounded close to 2026-highs.This is quite evident in the AUM ratio of leveraged equity ETFs to the market cap of the underlying stocks -- which has increased in recent weeks.Most notably for Semis (ex. memory) and Hyperscaler single stock leveraged ETFs. The ratio for Memory stocks hasn't increased in the same way, but it's still high.I think this could be a potential headwind for stocks and a source of volatility if leverage levels become excessive once again.Not to be a doomer, but one to keep an eye on...