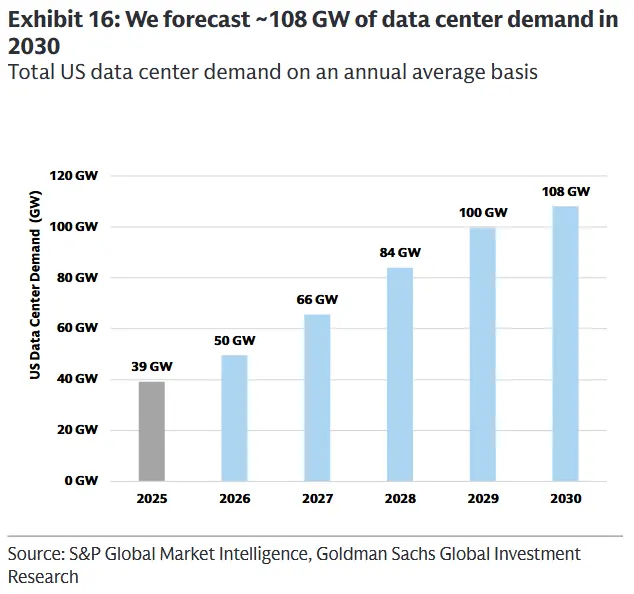
Goldman Sachs forecast ~108GW of data center demand in 2030 (US-only).
Key beneficiaries:- $Firstenergy(FE.US) & $Talen Energy(TLN.US): exposure to PJM and upside from generation/transmission opportunities.- $Xcel Energy(XEL.US): exposure to the growing MISO market.- $Duke Energy(DUK.US): benefits via ~15.4 GW high-confidence large load pipeline + favorable regulatory environment in the Southeast.- $Sempra Energy(SRE.US): capture opportunities in Texas via T&D capital investment.- IPPs like $Talen Energy(TLN.US), $Vistra(VST.US), and $NRG Energy(NRG.US) are best positioned to benefit from rising power prices and incremental data center PPAs across both PJM and ERCOT.
Paradi Lab
P
$Micron Tech(MU.US) Q4 earnings prediction:
Revenue: $51.9B vs. $50.0B guideGross Margin: 86.5% vs. ~86% guideEPS: $32.30 vs. $31.00 guideMaybe my modelling is too bullish? These numbers are significantly above consensus estimates...Regardless, I aim to drop a primer in advance of Micron's earnings.
P
Even if Anthropic of OpenAI come out with better agents than Muse, I doubt they'll have enough impact to overcome people's desire for simplicity.
Do you think people will pause their Instagram doomscrolling to jump into Claude's app? Will people stop a WhatsApp conversation to open up a ChatGPT agent? I genuinely don't see it...(unless Ant/OAI agents are some kind of black magic).Why wouldn't you just simply use Muse which is embedded inside the Meta apps already and can get your job done do a decent/good level? For better or worse, Meta are the absolute kings of this "usability" stuff.Right now, I think what matters most for these companies is to get AI agents into the hands of the masses - it's important to remember that many people haven't even tried using AI yet. So instead of monetization, I fully expect Muse's more important milestones to be around adoption/retention, plus more expansion in third-party commerce/payments integrations. This will then broaden out the workflows consumers entrust Muse with which will keep the Meta flywheel spinning.P![图片 1,共 2 张]()
![图片 2,共 2 张]()
Just got my first payout from the new Original Content Rewards program!
Reminder - 2x of the money I make from X will always be given away to charity instead of funneled into $Nebius(NBIS.US), $Intel(INTC.US) or $Sandisk(SNDK.US) stock.Please donate to Cancer Research UK if you're able to! ❤️I'm grateful that I get to share my thoughts/ideas...and that people take the time to read. It genuinely means a lot to me.-- Not posting this to show off. Rather, illustrating that some good can come from this fun little side hobby. Plus continued accountability to my original pledge when I first started posting on X.
P![图片 1,共 1 张]()
As of right now, it feels like the top three Mag 7's are $NVIDIA(NVDA.US), $Amazon(AMZN.US) and $Meta Platforms(META.US). I've personally been buying more of each every week recently.
It's also quite fascinating how quickly sentiment for Google has fallen with the stock down 15% since May.I wonder if this is a good spot to take another look at Google though. Surely they'll release a Muse competitor soon on top of Gemini 4? At the same time, part of me feels like they've fumbled around with AI for too long now - it doesn't instill too much confidence tbh.
P
You guys need to understand that reaching a resolution with the Iran war is the most important thing in global markets right now. Nothing comes close, not even Muse or DRAM contract hikes! All roads lead back to Iran and gosh do they know it...
The situation is literally like that meme where the backpack is being kept on by a single thread. Roughly 20% of the world's oil supply normally flows through the Strait of Hormuz, along with a massive share of LNG (mainly from Qatar) and current transits are ~5% of the pre-war levels. Let that sink in. Keeping the SOH shut for so long has caused the biggest oil supply shitshow in history. In fact, it's nearly 3x bigger than the 1973 oil embargo...and it's seeped into daily lives now to the point where I think it's absolutely ludicrous that they've not reached some sort of resolution....until now?!It's no surprise to see the markets love it whenever news of a potential ceasefire comes through. It's absolutely crucial to end this quickly!1% chance, 99% faith.P
Kinda crazy how no one cares about frontier pacing now. That was ridiculous from Dario and co.
Markets have since digested the fear from last Monday quite nicely and now seem excited with $Meta Platforms(META.US) Muse which is a massive efficiency unlock + HUGEEE compute multiplier. Every lab will build something similar eventually = CPU and cloud compute trade keeps going nuts.(Wish I had access to Muse in the UK!)Plus there's strong rumours of OpenAI releasing new models soon -- GPT-6 Sol. And new Anthropic models in the pipeline.P![图片 1,共 1 张]()
Semiconductor fwd P/E has been tracking inverse oil prices over the past year. Almost perfectly.
⬜️ $SOXX Fwd P/E Multiple 🟦 Inverse oil priceSince the Hormuz shock in Feb:As oil prices drop, semiconductor valuations rise. As oil prices rise, semiconductor valuations drop.P
AMD, TSMC and OSAT Channel Check:
1. AMD's AI GPU production (MI455/MI450) is expected to remain 100% at TSMC CoWoS in 2027. Production estimates land at a mid-point of 600k units for both SKUs next year per recent MS forecasts.2. While ASE and Amkor still lead OSAT capacity, their capacity ramps are rumoured to be progressing slower than expected. This means that TSMC may be required to support CoWoS-L wafers for AMD's Venice CPU prodction which would further constrain internal capacity for MI455/MI450 production. Per MS, this would equate to TSMC supporting ~80k CoWoS-L for Venice production.$AMD(AMD.US) $Taiwan Semiconductor(TSM.US) $Amkor Tech(AMKR.US) $Advanced Semiconductor Engineering(ASX.US)
P
$Nebius(NBIS.US) INCREASE ON-DEMAND GPU RATES EFFECTIVE OCTOBER 1.
H100: $3.85 per GPU-hour -> $4.50H200: $4.50 per GPU-hour -> $5.40B200: $7.15 per GPU-hour -> $8.50B300: $7.85 per GPU-hour -> $9.50AMD EPYC Genoa CPU and memory rates will also increase.Intel Ice Lake CPU pricing remains unchanged.P
Honestly - the FOMC decision / rate hike means nothing until the Iran war ends.
After all, the Fed can't reopen the Strait of Hormuz...P
Pacing the frontier is ONLY about Anthropic's IPO.
Investors are being buttered up for fewer future model releases. Why? Margins.I don't think margins are "bad" per se, but there are always deeper questions on whether they last/grow longer-term.Ultimately, shipping a new model with better capability at current price points hurts the labs. From a unit economics perspective, that's a price cut per unit of intelligence every time a new model is released. That compounds super fast at the current, highly frequent release cadences.So slowing model releases means Anthropic can slow price cuts per unit of new intelligence. I think that this is their only clean lever left to preserve margins unless they jack up prices to unforeseen levels which no customer will readily entertain.This is why we saw Sam and Elon agree with Dario yesterday. It only works if everyone else slows down too. As a margin lever, pacing has to be done industry-wide, and an industry-wide agreement not to compete on cadence is basically an agreement not to compete on price. Looking at costs: the labs expense training as R&D as they go, so nothing gets amortised in the accounting sense. But the economics are the same. Every frontier model is superseded IMMEDIATELY after the newest one is released. Fewer models being shipped means they each earn more for longer, which means training cost per revenue $ drops without the labs needing to spend anything less than they already are.This is an investor's dream lol. Again, no coincidence that this is all coming out so soon before Anthropic IPOs...With OpenAI, I think it's the same logic but from the opposite direction. They don't have the profitability Anthropic has so it makes more sense for OAI to wait to IPO as pacing takes effect. That's why Sam agreed with Dario. Elon only agreed with Dario because xAI are just so far behind the frontier lol. Also...Elon clearly wants the US to win above all else...so how exactly does pacing the frontier benefit the US in the race against China?P
So many tech valuations hinge on forced customer retention scores. I hope the market wakes up and realises that there's absolutely zero moat in usage streaks, notification loops and decent UI. These just end up with low-quality network effects that tech companies harp on about to save face from a relative lack of innovation.
For this reason, Oura's IPO will be tragic. They'll push subscription prices even higher to satiate shareholders, which will work in the short-term, but eventually customers will fall off the edge of a cliff once they've reached the peak of the price curve. My guess is that that's coming soon based on how they've hiked prices over the years.I genuinely feel like the world needs to wake up to these fads lol. Why do you need a ring or watch to tell you how you feel? I understand tracking steps or calories burnt, but stuff like sleep scores are probably the most useless sales feature that's been fabricated out of thin air over the past decade. Like, do people not know if they had a good nights sleep once they wake up? Who ACTUALLY cares if your sleep score was 87% in March and then 82% in April???The answer: people who PAY for the hardware/subscription.It's all backwards. You pay for this thing which means you're forced to care about what it tells you. Obviously there's a tiny subset of the physical elite who do care, but for most (relatively sedentary) customers, why does this stuff even matter other than sybolizing status / fashion accessory. Whoop are another (probably worse) example with an even worse product because their marketing/hype has been the only thing that's kept them functioning. Them IPO'ing would be genuinely hilarious because the stock would pump when they announce a new sportsperson sponsorship rather than anything to do with product innovation...which would never happen btw.I hope Apple takes the entire health hardware market by just acquiring Oura lol. That'd be huge aura (not Oura) points for John Ternus.P
🚨Leopold/Situational Awareness returns?
Since last Friday, there's been a string of significant Flex calls bought in concentrated AI names: $315M total options premiums / $1.1B of delta / $5.8M of vega.Positions:- $Sandisk(SNDK.US): Jan 2040/2200 calls - $57M prem, $198M delta, $1.04M vega.- $Bloom Energy(BE.US): Jan 250/310 calls - $48M prem, $140M delta, $565k vega.- $Intel(INTC.US): Jan 105/115 calls - $48M prem, $185M delta, $870k vega.- $Coreweave(CRWV.US): Jan 105/115 calls - $43M prem, $160M delta, $770k vega.- $DRAM: Jan 65/70 calls - $43M prem, $173M delta, $855k vega.- $SK Hynix(SKHY.US): Jan 190/210 calls - $39M prem, $148M delta, $710k vega.- $AMD(AMD.US): Jan 540/580 calls - $36M prem, $193M delta, $1.08M vega.It'll be confirmed as Leopold if we start to see some big FLEX calls in $Micron Tech(MU.US) / $Nebius(NBIS.US) / $Taiwan Semiconductor(TSM.US) soon. Data via CBOE. NMR + GS desks aligned on "single mystery buyer" narrative...
P![图片 1,共 3 张]()
![图片 2,共 3 张]()
![图片 3,共 3 张]()
Just some notes from $Nebius(NBIS.US) fireside chat at Goldman Sachs Tech Conference:
TLDR: Yep, it's bullish.1. Order book extends into H1 2028 which is 2 quarters further out than at Q2 ER.Arkady said "people are demanding tens of thousands of vGPUs and GPUs now. So we see demand today as unlimited."Bro...what?!!At Q2, they said that all of 2027 could be sold today. But Nebius having visibility ~1.5 years away massively de-risks their ~5GW contracted power target and their ~$25B of FY26 capex.On demand, Arkady also said that demand visibility now extends to 24+ months (vs. 18 months previously).This is HUGE because demand duration is a huge crux for neocloud bears (kinda makes sense why). Even $Coreweave(CRWV.US) CEO said at the GS Conference that they are "struggling to meet demand everyday."2. "We do not pre-sell much. We are focusing on free capacity, which we will be selling later"I think two things are happening here with NebiusFirst - this is the opposite of $Coreweave(CRWV.US)'s model where their ~$104B backlog is take/pay dynamics. Nebius are instead choosing to sit on uncontracted 2027 capacity so they can sell into rising prices, kinda like how $Micron Tech(MU.US) and co. were doing pre-LTAs. Second - keeping some spare capacity keeps room for longer-term strategic partners arriving into 2027 (which will be extremely supply-constrained). I.e. enterprise names coming via the $Palantir Tech(PLTR.US) partnership. I think both reasons make sense, I'm fairly confident that 2027 pricing will be higher. 3. "We actually have a list of new customers that are looking for any of the older generation chips that come available." This lines up with $Coreweave(CRWV.US) disclosing at Q2 an A100 contract priced out to 2029 and completely guts the residual-value thesis bears like Burry lean on. 4. $Shopify (SHOP.US) "used open-weight models, trained it with their own data repetitively, and they achieved the quality which is higher than they had with GPT-5 and 6."Feels like that's the whole enterprise adoption thesis summarized....narrow domain, pvt data, repeated loop, open weights > fronteir, at a fraction of the cost. Probably also why the token factor and the Tavily acq. matter.So yeah, Nebius' entire infrastructure goes kinda crazy. More than just GPU rental.5. Contract mix Marc: 3-6 month short-term deals go out "at a multiple of the ARR per megawatt" of the core. 1-3 year medium-term deals are "the lion's share" and 5+ year hyperscaler deals were done "with the explicit intent that we are looking for the capitalization benefit."- So the longer duration $Microsoft(MSFT.US) + $Meta Platforms(META.US) contracts are lower risk collateral for financing the build- the opportunistic short-duration surge contracts at materially higher pricing are the top-ups.- and the 1-3 year book with AI natives and enterprises (priced above hyperscaler deals + prepaid) are the core + fastest growing segment.Just for a summary of the points I found most interesting / different from Q2 earnings.Cool to also see the "the vision that Arkady has is us becoming a hyperscaler." I've been sharing the same vision for some time now, and is why Nebius ultimately deserve to trade multiples higher than Coreweave for example.
P![图片 1,共 1 张]()
Someone check-in on Burry!
How can you not love the $Nebius(NBIS.US) partnership with $Palantir Tech(PLTR.US)?!Palantir naming Nebius as their "preferred sovereign AI infrastructure partner" is so cool because it effectively hands Nebius enterprise distribution on a plate.It also diversifies future revenue away from $Microsoft(MSFT.US) and $Meta Platforms(META.US) which forms the basis of many Nebius bear theses.P![图片 1,共 2 张]()
![图片 2,共 2 张]()
Incredible growth expected for $Lumentum(LITE.US), $Coherent Corp.(COHR.US), and $Applied Optoelectronics(AAOI.US) with new GS optical transceiver forecasts.
- Global optical transceiver TAM revised up by 33% / 81% / 115% in 2026-28E.- In 2026/27/28E: optical transceiver market to reach $68B/131B/148B.- Driven by (1) higher rack-level AI server and ASIC AI server shipments and (2) higher estimates on the usage of optical transceivers per Nvidia GPU in rack-level AI servers. - 800G and above segment to increase at a +69% CAGR to reach $45B/108B/130B. - 800G/1.6T shipment volumes at 45M/33M units in 2026E, growing to 49M/71M in 2027E, with 3.2T shipment ramping up to 23M/68M in 2027/28E. - Silicon photonics will account for 60%/80%/80% of 800G/1.6T/3.2T optical transceivers.Just insane growth on top of what most people had forecasted a few months ago.
P
Just a quick macro note.
Feels like the broader market will move sideways for the next 2-4 weeks, but it wouldn't surprise me to see some pressure on high beta names.That said, fundamentally, nothing's changed w/ solid earnings across most sectors especially AI/semis names.Stocks are in a huge bull marke, even factoring in the July dip in semis (useful to zoom out here w/ loads of names up 2-4x YTD). History tells us that this kinda bull market ends with a Fed hike / recession. Recession won't happen imo, but it's currently unclear if the Fed hikes...and to what extent? I ultimately feel like it needs to happen at some point - Sep or Dec. Get it done with lol.Seasonality could come into play too w/ midterms usually being bad for equities pre-election, then good for equities post-election. Historically, Sep is a down month before Q4 and pre-Xmas period being positive. Lots of data around this.In terms of catalysts, Iran/US always the hottest topic these days. Oil price impacts and second-derivative equities impacts. For AI/Semis, you've also got the GS Communacopia + Technology Conference soon w/ OpenAI etc all doing fireside chats. On top of $Micron Tech(MU.US) and $Broadcom(AVGO.US) earnings this week.Time will tell whether MU earnings can re-rate memory names, or AVGO earnings have the same impact for the broader semis ecosystem. $NVIDIA(NVDA.US) didn't really have that effect, so I kinda doubt AVGO will.P![图片 1,共 1 张]()
Silicon Photonics' optical transceiver market share is estimated to exceed 50% by 2027.
$Taiwan Semiconductor(TSM.US) VP of Advanced Packaging said today that silicon photonics is becoming the mainstream form thanks to the structural transformation of optical transceivers.He also stated that the real bottleneck for large-scale deployment lies in lasers, optical fibers, fiber optic connectors, and product testing.If I was to pick the "main" players instead of just name-dumping:- $Lumentum(LITE.US) / $Coherent Corp.(COHR.US): InP lasers - CW for SiPh, ELS for CPO, 200G EMLs- $Aehr Test(AEHR.US): SiPh WLBI testing- $Corning(GLW.US): PM fibre, fibre arrays & MPO/MTP connectivity- Sumitomo Electric (5802): InP lasers + substratesObviously you've got a ton of other names from: $Applied Optoelectronics(AAOI.US) for InP lasers, $IQE for InP base epi, $BESI for hybrid bonding and $Keysight Tech(KEYS.US) / $Viavi Solutions(VIAV.US) for optical test.Feels like TSMC have been running the same narrative alongside the COUPE roadmap for a while now though.But always good to get some re-confirmations on where everyone's favourite bottlenecks sit / narratives coming from TSMC themselves.P
With $SIVE, you're paying EXTREMELY premium 2027 multiples for a "what if" scenario.
That is: What if Sivers' $1.2B opportunity pipeline converts into *actual* sales by roughly H2 2027.Whereas with $Lumentum(LITE.US), $Coherent Corp.(COHR.US) and $Applied Optoelectronics(AAOI.US): you've already got revenue that's sold out, LTAs to 2028-30, shipping today, on 30-50% GMs. No "what if" needed.So either:1. $Lumentum(LITE.US), $Coherent Corp.(COHR.US) and even $Applied Optoelectronics(AAOI.US) are VERY cheap right now [5-14x 2027 sales].2. Or Sivers is VERY expensive right now [~35x 2027 sales based on my current modelling].I'll share a post later/this weekend for more detailed comments.
P
$NVIDIA(NVDA.US) generating $96.2B of highly profitable revenue, while also growing 106% annually is genuinely insane at their scale. People need to let that sink in.
Combine that with expectations to "grow revenue by approximately 70% in fiscal 2028" under current supply constraints...Makes me think that $NVIDIA(NVDA.US) is perhaps the cheapest and highest quality growth stock we'll see for a long time.
P![图片 1,共 1 张]()
Thoughts on $NVIDIA(NVDA.US) later today:
Prediction: - I don't see a revenue beat being a catalyst for NVDA.- Everyone knows that revenue will be ~10-15% ahead of estimates thanks to GB300 (and GB200) volume expansion.- Moreover, looking historically, recent beat & raise quarters have not been a positive re-rating catalyst for NVDA's share price... perhaps the quarter's already been priced-in due to a +12% move in the last month.- On the flip side, maybe this time will be different thanks to the stock currently trading at extremely low valuations... I actually think broader institutional sentiment improved as of yesterday too with significant short covering which drove the share price up. Time will tell.For next quarter:- No surprises - guidance will of course increase thanks to additional ramps in rack volumes, plus first Vera Rubin orders filtering through.- I expect gross margins to remain stable thanks to ASP increases offsetting continued memory price surges from $SK Hynix(SKHY.US), $Micron Tech(MU.US), and Samsung.In terms of "qualitative" catalysts, there are a few areas Jensen and co. need to touch on though (common threads across the street):1. HBM: Per JPM/MS/GS (and wider industry comments), NVDA have made changes to HBM content for both Rubin and Rubin Ultra. This is of course due to memory supply being extremely scarce currently - but what does this mean for NVDA exactly? On the flip side...what does this mean for the memory players? Can NVDA keep passing on price increases to customers if memory prices continue soaring? I hope this is all expanded on on the call in some detail.2. Competition such as $AMD(AMD.US), $Cerebras(CBRS.US), OpenAI Jalapeno:Around ~40-50% of NVDA's revenue comes from four hyperscalers that are all deploying their own stuff - $Alphabet(GOOGL.US) TPU, $Amazon(AMZN.US) Trainium, $Meta Platforms(META.US) MTIA, $Microsoft(MSFT.US) Maia. Plus OpenAI / $Broadcom(AVGO.US) revealing benchmark results for their in-house Jalapeno chip which shows 1.5-1.9x more throughput per kilowatt + 1.7-3.6x lower end-to-end latency against NVDA's GB200 and GB300 rack systems. All of these factors have been working against NVDA recently, even just from a sentiment perspective. Jensen's updated views will be appreciated!3. Funding partnerships: A few weeks ago, NVDA announced a partnership with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR "to establish AI compute infrastructure financing platforms to mobilize over $500 billion of third-party capital." Again, what does this mean for NVDA? They quite clearly have sight over demand longer-term, but "circular financing" is still something that still comes up a lot these days (despite Jensen outlining why it's not in his X article).Big day ahead, expecting some volatility thanks to last minute positioning adjustments.P
Just some of my notes from $Semtech(SMTC.US) Q2 earnings:
TLDR: Like $Applied Optoelectronics(AAOI.US), it's all about Semtech expanding capacity - CEO said the capacity they've secured "may not be enough" for FY28...1. Q2 upside is from 1.6T qualifying early- Pretty shocking (in a good way) how compressed the qualification timelines have become. - Hyperscalers and everyone upstream are pulling timelines forward so quickly rn.- We saw with $Lumentum(LITE.US), $Coherent Corp.(COHR.US), $Applied Optoelectronics(AAOI.US) especially that demand is just bulldozing any qualification barriers. Now seeing the same with Semtech.2. FiberEdge is quite underappreciated- I agree w/ mgmt that people are "overindexing on CopperEdge" - the better business is probably TIA/driver.- 800G TIA share has gone from ~18% two years ago to well over 50%, and they expect >50% share at 1.6T by January.- Impressive...- Industry 800G units: they entered the year on a ~50M forecast and are now hearing 80-90M vs. ~20M two years ago. - Impressive again...3. Content per transceiver - goes from high single digits to $80-90 at 3.2T.- Quite funny - one analyst assumed that "high double digit" content meant teens. CEO corrected him with $80-90 lol. That's ~10x!- Photonics fab capacity goes 3-4x by year-end (they picked up a fully facilitated fab next to the existing one).- I don't think the market has modelled any of this. Even at half the claimed content, DC revenue stops scaling w/ transceiver units + starts scaling w/ units times content. - And every merchant InP line being tripled is another pointer that InP demand is way ahead of supply.- Which is the same signal $Applied Optoelectronics(AAOI.US) sent by clearing its HQ building for InP wafer expansion.4. More capacity needed (obviously)- Secured capacity "may not be enough" especially 2H FY28.- Semtech are negotiating prepayments + joint capex with front/back-end partners, and qualifying additional OSATs to spread geopolitical risk.- Pricing: no erosion expected near term and none in the booked backlog. Cost increases are being passed through. Just what you wanna see :)5. Gross margins are pretty insane- 54.5% in Q2 -> 58.3% guided -> 63.9% excl. the cellular module business being divested (closes Q4).- CFO framed ~64% as the post-close starting point. - I actually think 64% is the margin floor, not the target. Pretty sure they know they can do more lol. No reason to send out such a high target to the market otherwise.CEO also said that "we have the financial capability" to fund the FY28 capacity push":Looks like that's the case based on quick napkin maths:- FCF was $61M in Q2- Q3 EBITDA guided to $134M - I'd say roughly $300M+ annualized FCF exiting the yr- Add $204M cash + $62M coming from Compal for the cellular module unit closing in Q4So would be surprised to see any more dilution on top of what they already did a year ago. Overall though - pretty good earnings.P![图片 1,共 2 张]()
![图片 2,共 2 张]()
Today seems to be a red day for semis and memory.
I will be pleasantly surprised if we end up green - that'll be a huge/positive sentiment shift towards semis.Traditional defensive stocks are all showing some strength, as well as SaaS which I personally class as "defensive tech". That's the < long SaaS, short SaaS > trade. Moreover, if $Apple(AAPL.US) is up in the pre-market, then high beta semis tend to see a negative hit.Yields for 30Y treasury is at the highest point since pre-GFC at 5.32%. Similarly, the 10Y is at 4.74% - also at pre-GFC highs.Seems like it's due to a few reasons: rising oil prices (new highs for Aug) and renewed fears of rate hikes from the Fed. I don't think a hike makes sense right now, but time will tell what happens with Iran. The Fed drops their meeting minutes from the July meeting this week - will be an indication of where rates head.I don't see this as a long-term issue though. Just feels like traders are unlevering positions after a strong few weeks of momentum across semis and memory. Many institutions are now overweight high beta tech and are sitting on (relatively) huge gains MTD. Would make sense for them to unwind some of their positions / rebalance amid an uncertain macro environment.Fundamentally, I wanted to emphasise that the AI trade is stronger than ever after Q2 earnings. Semis and memory stocks get thrashed around from pillar to post when macro is so volatile.Like I mentioned the other day, if names like $Nebius(NBIS.US) or $Sandisk(SNDK.US) can have 10% green days, they can certainly have 10% red days.Overall, I am very bullish long term - just good to be aware of macro overhangs which drive short-term prices.Just need to ride into Jackson Hole next week.$SOXX $SPY $QQQ $SMHP
GPU fleet unit economics.
TLDR: Tough to be bearish on $Nebius(NBIS.US) or $Coreweave(CRWV.US) right now.Some maths, but it's important to understand.Using $Nebius(NBIS.US) 1-3yr contract economics:- $20-25M ACV per MW at a payback of 1 year 10 months.- Take $22.5M midpoint ACV/MW at a ~55% cash margin ( $Nebius(NBIS.US) core AI cloud runs ~50%, $Coreweave(CRWV.US) 59%) and you get ~$12.4M/MW of annual cash flow. (Payback runs against cash flow, not revenue)- 1.83 years of that implies "all-in" capex of ~$20-23M per MW (GPUs included). - Which ties to Nebius' $20-25B capex guide for 2026 against ~1GW.- Over a 4-5 year life that's roughly $50-62M/MW of cumulative cash flow against ~$22M of capex. - NPV is +$20-25M per MW even discounting at 12-15% and IRR near 50%.Then years 1-2 of DCF nearly cover the entire capex on their own. Meaning that the GPU could go to $0 residual after year 2 and the deal basically breaks even. That is insane.So really, the bear case doesn't need slow decay to be wrong. Rather, it needs the contracted years themselves to fail.And those years are effectively walled off rn. - Around 70% of $Nebius(NBIS.US) deals carry prepayments covering 50-60% of the capex, on take/pay terms. - $Coreweave(CRWV.US)'s $104B backlog is take/pay with ~21% of it recognized more than four years out. As we now know, $Coreweave(CRWV.US) signed an A100 contract running into 2029 (a SKU introduced in 2020) "at or above where it was years ago", and CEO told CNBC a batch of H100s coming off an expired contract was re-booked immediately at 95% of the original rate. $NVIDIA(NVDA.US)'s CFO also said that A100s shipped 6 years ago are still running at full utilization.And $NVIDIA(NVDA.US) is now willing to underwrite residual value itself, up to 25% per project in the new financing platforms. I don't think they'd be willing to backstop if they expect GPUs to be worthless in around 3 years or so.For the neoclouds themselves though, depreciation is the biggest cost driver e.g. Nebius D&A was larger than their adj EBITDA last Q. If economic life actually extends to a new base case scenario of 5-6 years rather than the old 3-4 years...Earnings power re-rates higher across $Coreweave(CRWV.US), $Nebius(NBIS.US) and even the hyperscalers as ultimate beneficiaries.