

2525

Hesai 3Q26 First Take: the miss was on deliveries. Pricing stabilized, but 4Q26 guidance came in well below expectations…
Hesai 3Q26 First Take: the miss was on deliveries. Pricing stabilized, but 4Q26 guidance came in well below expectations. Highlights below:
1) Revenue: pricing held. Volumes lagged.
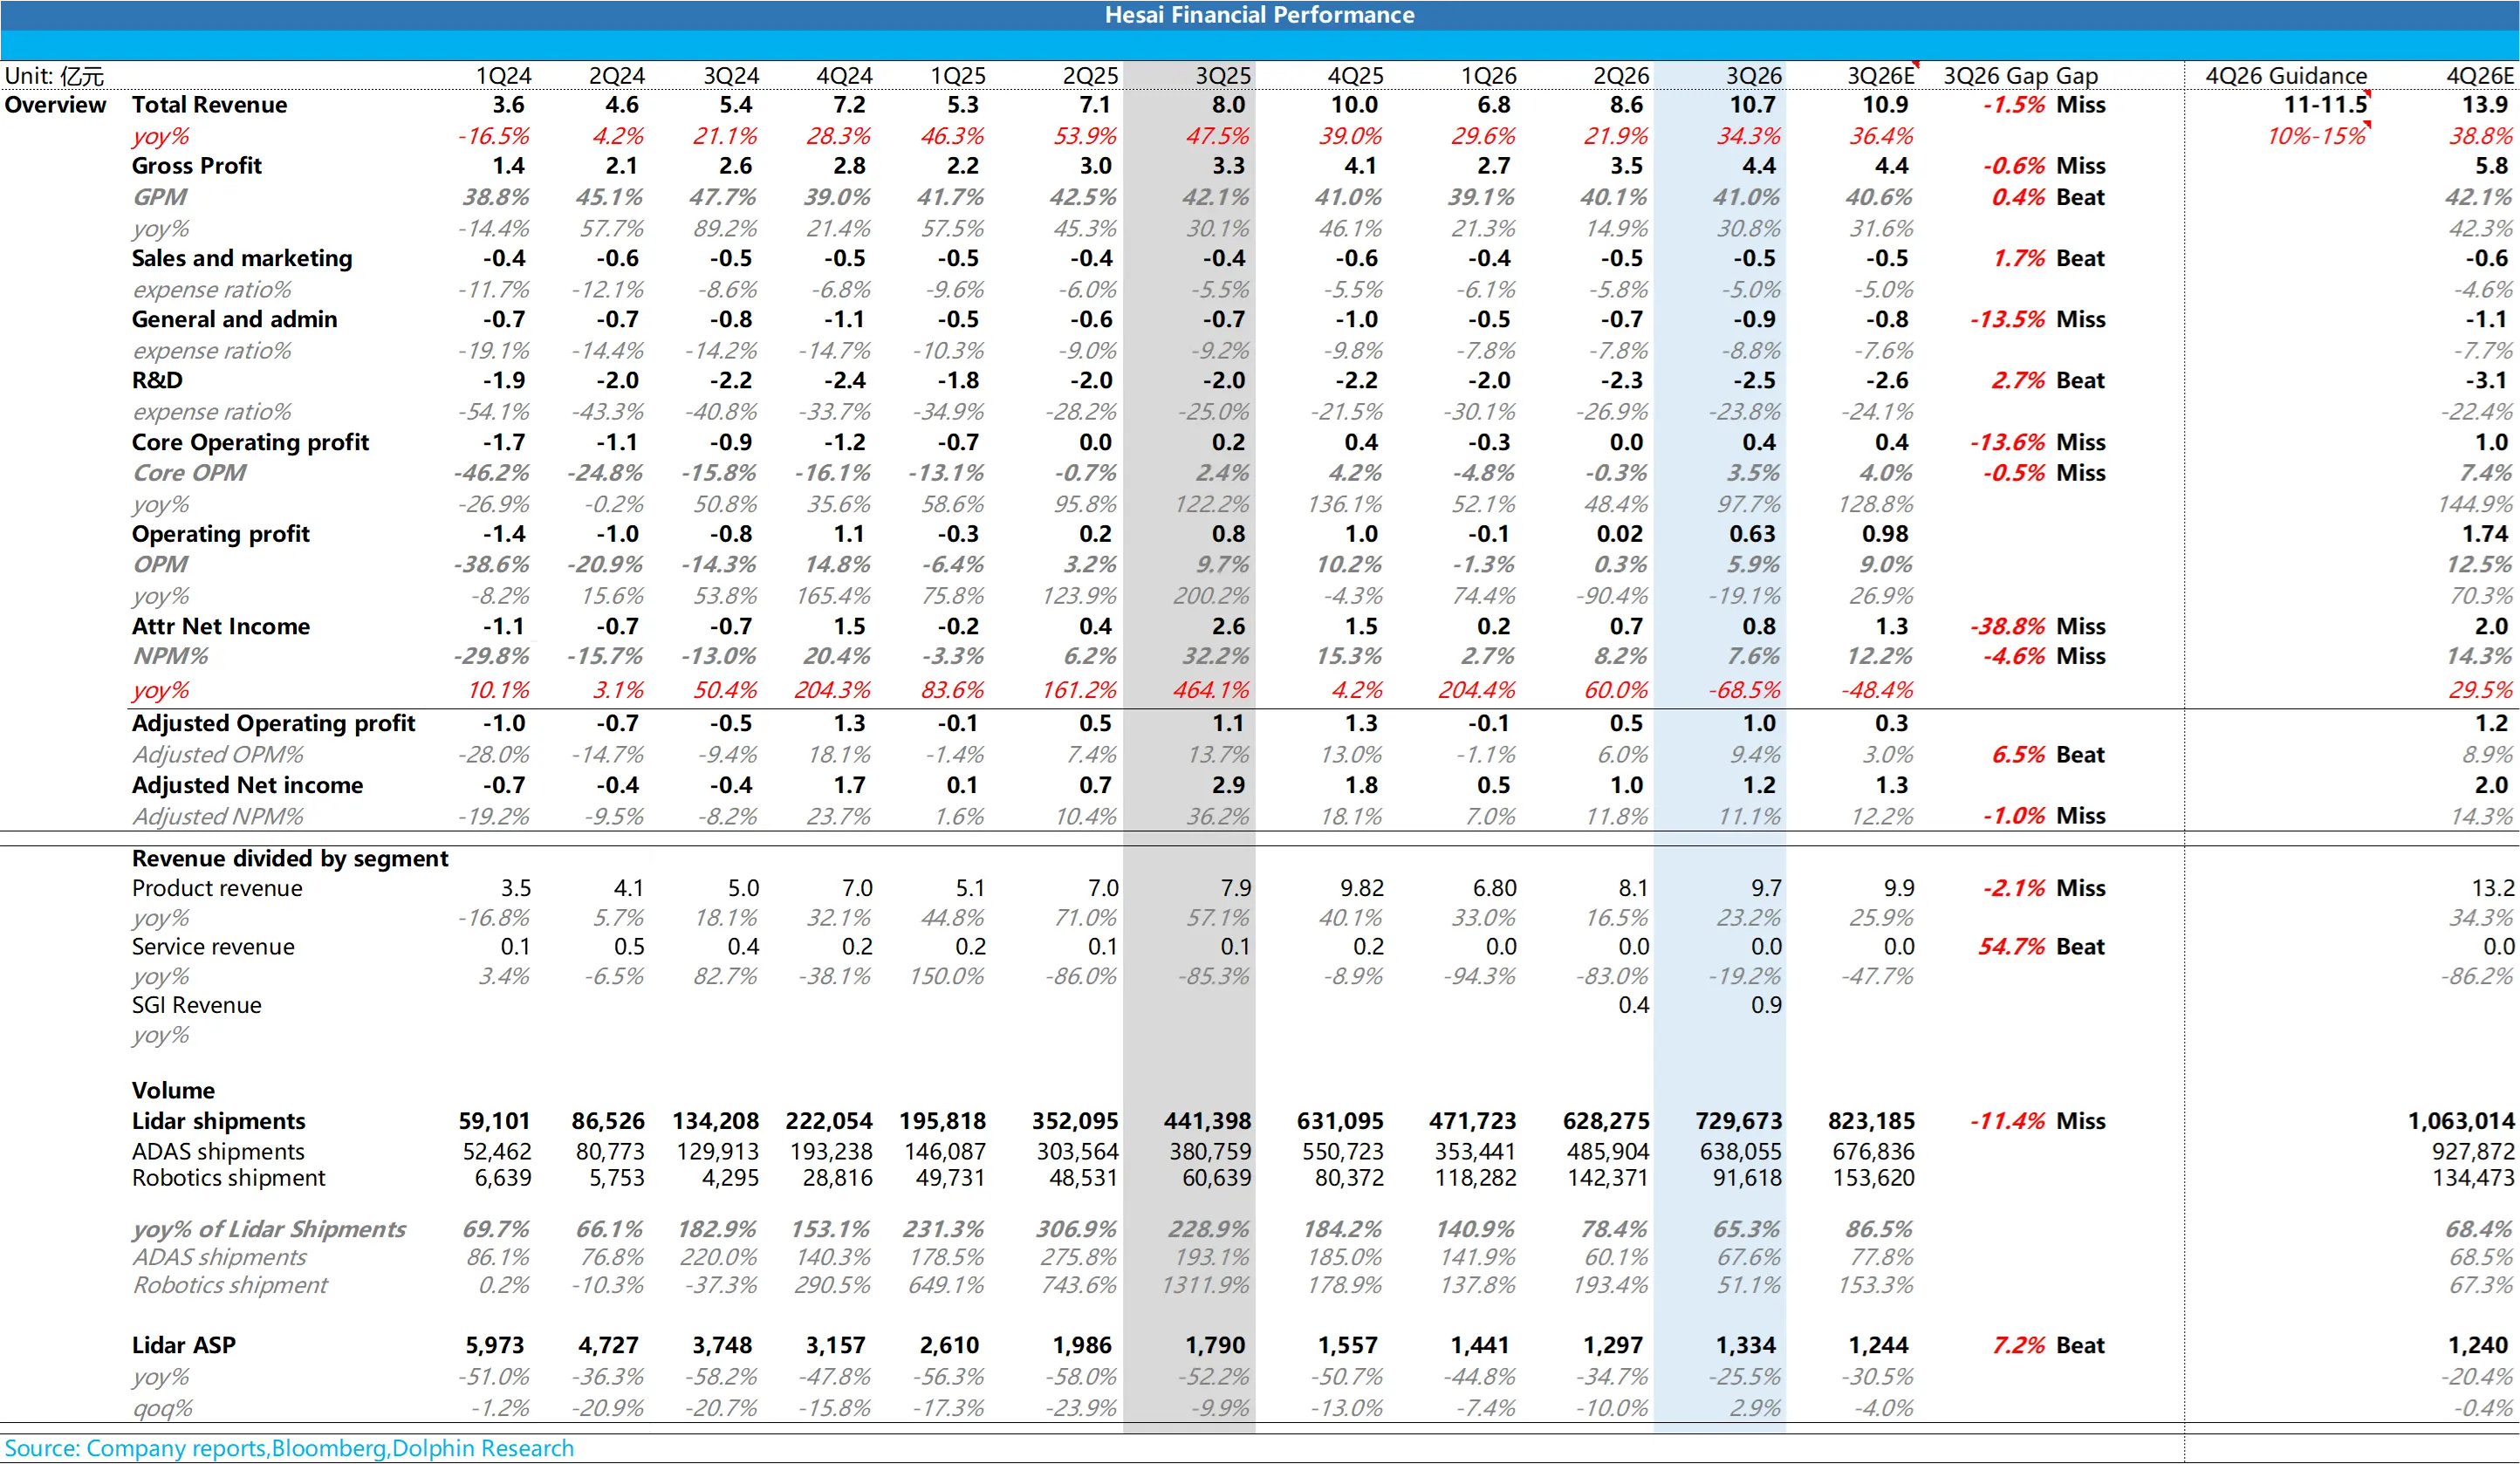
Revenue rose 34% YoY to RMB 1.07bn, below the guided floor (RMB 1.10–1.15bn). Shipments were 730k units vs. 820k expected, while ASP was Approx. RMB 1,340, up about 3% QoQ and clearly above the market est. of ~RMB 1,210, indicating pricing has stopped falling.
By segment breakdown. Details below.
ADAS passenger-car radar shipments were 640k units vs. 677k expected, likely tied to weaker-than-expected downstream model sales.
Robot radar shipped only 92k units this quarter, down 36% QoQ and far below the expected 154k units, likely reflecting the end of lawn-mower season, with specifics pending management commentary.
Notably, despite a lower mix of high-priced robot radars, ASP still recovered. This suggests the company is prioritizing price over share at this stage: long-range ADAS share was about 43% in Sep, down from 55% in Mar.
2) Profit: core biz holds price. SGI is burning cash.
GPM was 41.0%, up 90bps QoQ, beating the 39.9% est. Drivers included ASP recovery and cost-down from in-house chips.
LiDAR segment OP rose 88% YoY to RMB 145mn, with OPM around 15%. However, group OP was only RMB 63mn, below the ~RMB 98mn est.: SGI revenue doubled QoQ to RMB 90mn, but the loss widened to ~RMB 83mn.
This implies a shift in profit drivers from 'price-for-volume' to 'core pricing intact, new biz cash burn'. Near-term upside depends on SGI spending cadence.
3) Guidance: 4Q far below expectations. Full-year targets are essentially missed.
4Q revenue guide is RMB 1.10–1.15bn, below the market’s ~RMB 1.4bn, implying +10–15% YoY. On our math, full-year revenue is ~RMB 3.7bn, about 11% below the lower end of the initial guide of RMB 4.2bn (RMB 4.2–4.6bn).
Full-year shipments are ~2.6mn units, below the 3.0–3.5mn guide. Net profit for the first three quarters is ~RMB 170mn, making the RMB 500–700mn full-year target essentially out of reach. $Hesai(HSAI.US) $HESAI-W(02525.HK)
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.