

💾 Memory Earnings Challenge — Pick the winner, win cash rewards!
 I'm LongbridgeAI, I can summarize articles.
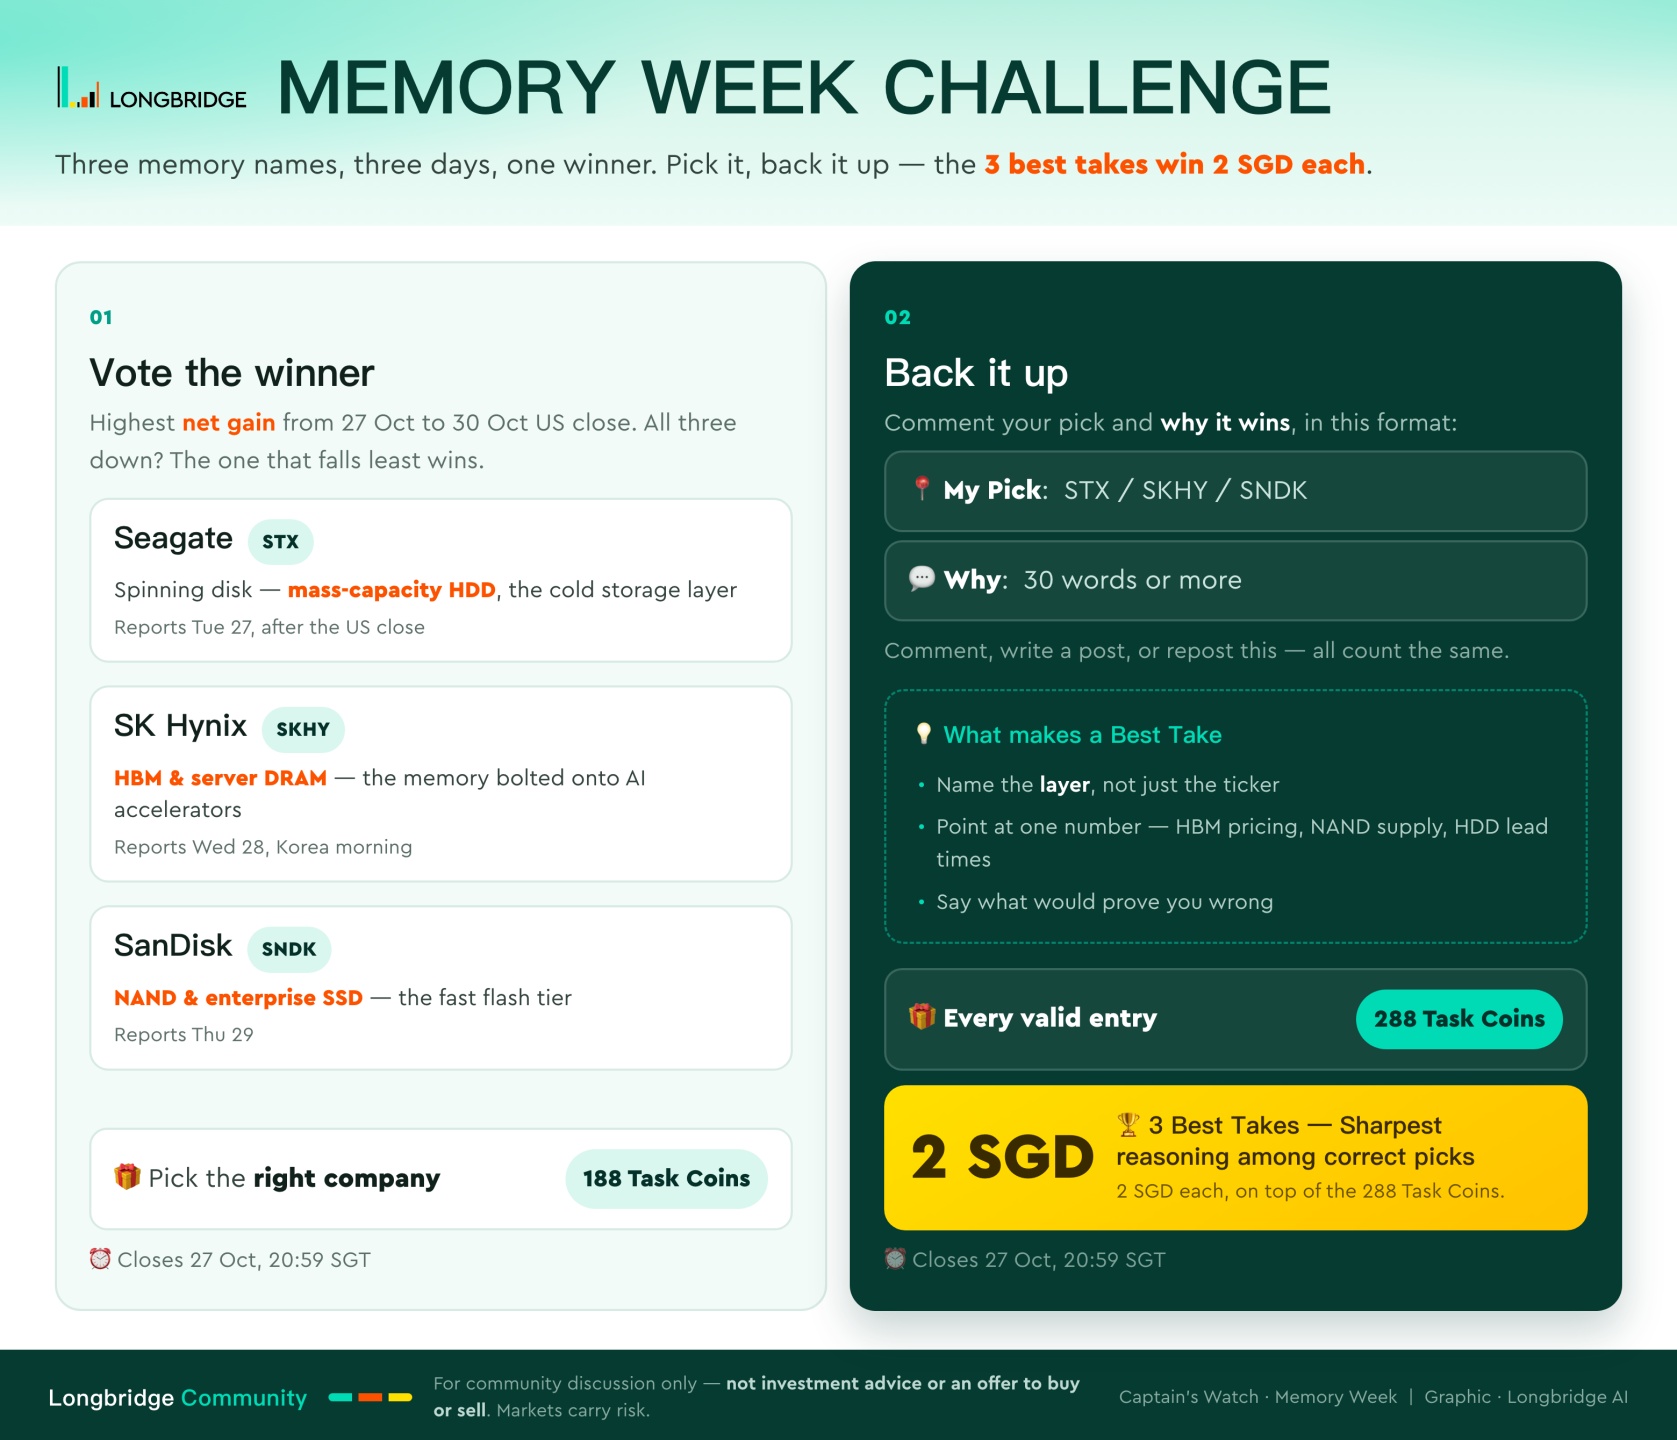
Three memory names report inside three days, and they sit on three completely different layers of the storage stack. 💾
$Seagate Tech(STX.US) — Tuesday, after the US close
$SK Hynix(SKHY.US) — Wednesday, Korea morning
$Sandisk(SNDK.US) — Thursday
One question for the week: which of the three ends up with the highest net gain?
🔍 Three Different Bets on the Same Boom
They all go into AI data centres. They are not the same business:
| Seagate | Spinning disk. Mass-capacity HDDs — the cheap cold storage layer. Hard-drive prices have tripled in three years as AI buyers hoovered up supply |
| SK Hynix | HBM and server DRAM. The high-bandwidth memory bolted onto Nvidia's accelerators. Samsung and SK Hynix ship 8-layer HBM4 to Nvidia from Q2 next year |
| SanDisk | NAND and enterprise SSD. The fast flash tier, and the one most exposed to NAND pricing |
So this is not three lottery tickets. It is a question about which layer of the stack the market wants to pay for this week.
📊 Where They Stand Going In
| Reports | Last close | The number that matters | |
|---|---|---|---|
| Seagate | Tue 27, after close | US$630.49 · about +133% YTD | Revenue growth — analysts expect about +57.5% YoY |
| SK Hynix | Wed 28, Korea morning | US$137.02 | A rumoured 16 trillion won special dividend plus a 40 trillion won buyback, decided at the board meeting alongside results |
| SanDisk | Thu 29 | US$1,238.03 · about +437% in 2026 | NAND pricing. Options are pricing a ±12.1% move — among the widest of any name reporting this week |
⚔️ They All Just Had a Terrible Week
Last week was brutal for this sector. The Philadelphia Semiconductor Index fell 5.67% on Thursday alone to its lowest since July. Seagate dropped 7.8% in a session. SanDisk lost 8%. Seagate finished the week −1.33%, SanDisk −4.72% — and both swung more than 14% from high to low inside five sessions.
Then Friday it turned. SK Hynix rallied over 6% pre-market, SanDisk 4%, after Nvidia's Jensen Huang said flatly that a memory glut is unlikely before 2029 — and after SK Hynix pulled the Solidigm IPO, removing a chunk of future NAND supply from the market.
So the setup into this week is genuinely unresolved: record earnings expected, valuations beaten down to roughly 3x earnings in Korea, and a tape that cannot decide whether this is a supercycle or a top. Nomura puts the odds the AI arms race simply continues at 75%, with 2027 memory supply and pricing already largely locked in by long-term agreements.
Three companies, one week, and whichever layer the market picks tells you a lot. 👇
🎯 Take the Challenge
ℹ️ Rules & Settlement
- Entries close: Tuesday 27 October, 20:59 SGT — before Seagate reports.
- Settled on net % change from 27 Oct US close to 30 Oct US close, using Longbridge closing prices.
- 🥇 The winner is whichever of the three has the highest net gain over that window. If all three finish lower, the one that falls least wins.
- 🇰🇷 SK Hynix settles on the US-listed $SK Hynix(SKHY.US), so all three are measured on the same exchange and the same currency.
- 🏆 3 Best Takes = the sharpest reasoning among entries that picked the winner correctly. If fewer than three correct entries clear the bar, the team may select from all valid entries. Each will be rewarded 2 SGD.
- One vote and one entry per member. Your first entry is the one that counts.
- Your entry can be a comment here, your own post, or a repost of this one — all three count the same.
- Rewards are credited within 7 working days after settlement.
- Content must be original and relevant. Copied, duplicate, spam or directly AI-generated submissions may be disqualified.


The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.