

Defensive stocks HAS MAT Disney
 I'm LongbridgeAI, I can summarize articles.
🐱 Hasbro, Mattel & LEGO: Why I Like the Toy Industry as a Value Investment
🎮 1️⃣ Why am I making this trade now?
I like Hasbro $Hasbro(HAS.US) because I see it as more than just a traditional toy company. It owns some of the world’s most recognisable brands, including Monopoly, Transformers, Nerf, Play-Doh and Magic: The Gathering. These are intellectual properties that can generate revenue for many years.
My Hasbro position is currently showing an unrealised profit of US$52.73, with a cost price of US$71.94 and a displayed market price of US$117.57. I like the business because its brands have long-term recognition and customers continue buying products across different generations.
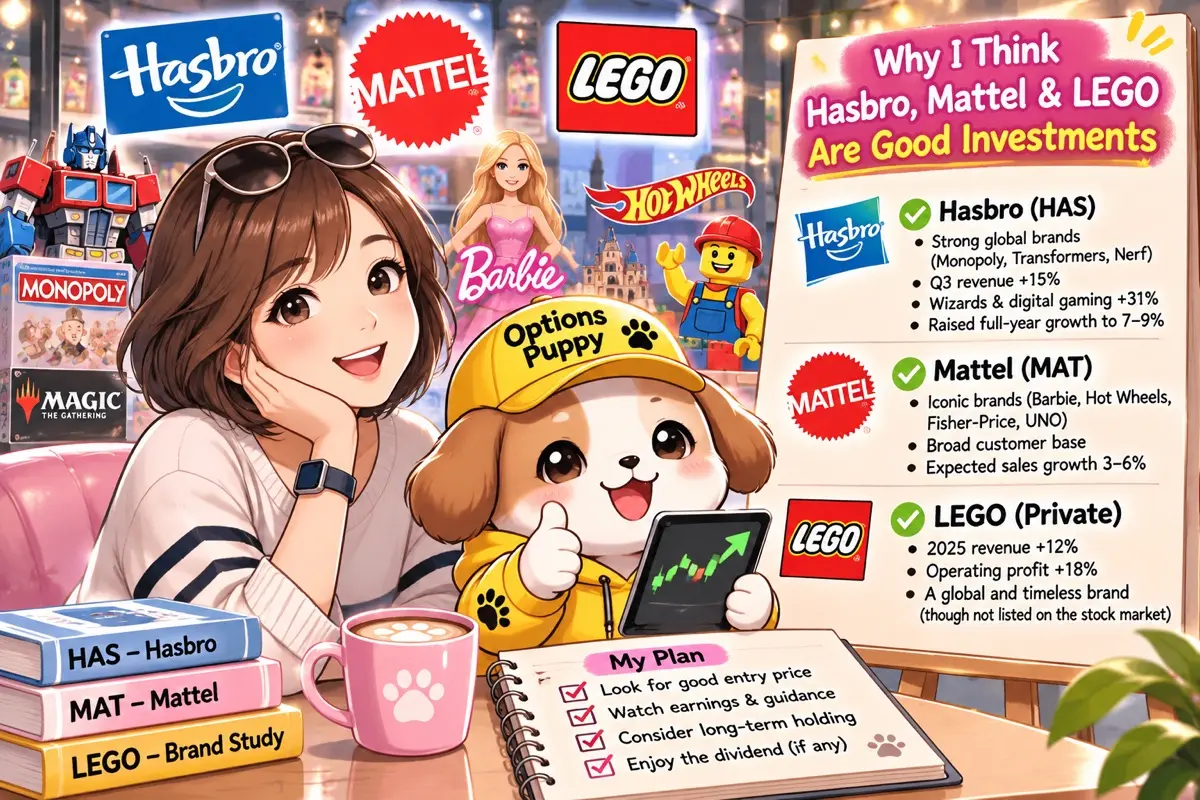
📈 The latest business performance is encouraging. Hasbro reported 15% revenue growth in Q3 2026, while its Wizards and Digital Gaming segment grew 31%. Magic: The Gathering generated more than US$600 million in quarterly revenue. Hasbro also raised its full-year revenue growth forecast to 7–9%.
🧸 2️⃣ Why I also like Mattel
Mattel $Mattel(MAT.US) is another company worth watching. Its brands include Barbie, Hot Wheels, Fisher-Price and UNO. I particularly like Hot Wheels because it has a strong collector market, while Barbie has demonstrated the ability to expand beyond traditional dolls into entertainment and licensing.
Mattel gives me exposure to another portfolio of established consumer brands, although its 2026 guidance is more modest, with expected sales growth of 3–6%.
🧱 3️⃣ What about LEGO?
LEGO is another excellent example of a powerful toy brand. Its 2025 revenue increased 12% to DKK83.5 billion, with operating profit growing 18%. Unfortunately, LEGO is privately owned, so I cannot buy its shares directly on the stock market.
🏰 4️⃣ Why I Also Like Disney (DIS)
Disney is another company I would put on my watchlist. I like Disney because it owns some of the strongest entertainment intellectual properties in the world, including Mickey Mouse, Marvel, Star Wars, Pixar and Frozen.
What makes Disney interesting is that it is not just a movie company. It has several sources of revenue: theme parks, streaming through Disney+, films, merchandise and licensing. This gives Disney multiple ways to monetise the same popular characters and franchises.
🎬 I particularly like its ability to turn successful movies into long-term businesses through merchandise, theme park attractions and streaming subscriptions.
📈 My investment thesis is that if Disney continues improving streaming profitability, growing its parks business and producing successful entertainment franchises, its earnings potential could improve over time.
🐱 My plan: I would watch its valuation, free cash flow, streaming profitability and theme park performance before adding shares. Disney is not necessarily cheap at every price, but I believe its collection of valuable brands makes it an interesting long-term investment candidate.
🐱 4️⃣ What’s my plan from here?
I prefer established companies with recognisable brands, repeat customers and pricing power. Hasbro and Mattel offer listed investment opportunities, while LEGO demonstrates the strength of the industry.
I will continue watching valuations, earnings growth, cash flow and dividends before adding more shares. A good company is not automatically a good buy at every price.
For me, these are interesting businesses to consider when the market offers attractive entry prices.
Sources: Hasbro Q3 2026 results · Mattel financial results · LEGO 2025 results.
$Disney(DIS.US)
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.