

AMD 3Q26 First Take: The highlight of this print is the above-consensus guidance. Versus the past two quarters, the grow…
AMD 3Q26 First Take: The highlight of this print is the above-consensus guidance. Versus the past two quarters, the growth mix has shifted — client is lagging, Q3 growth was carried by a doubling in server CPUs, and Helios takes the baton from Q4.
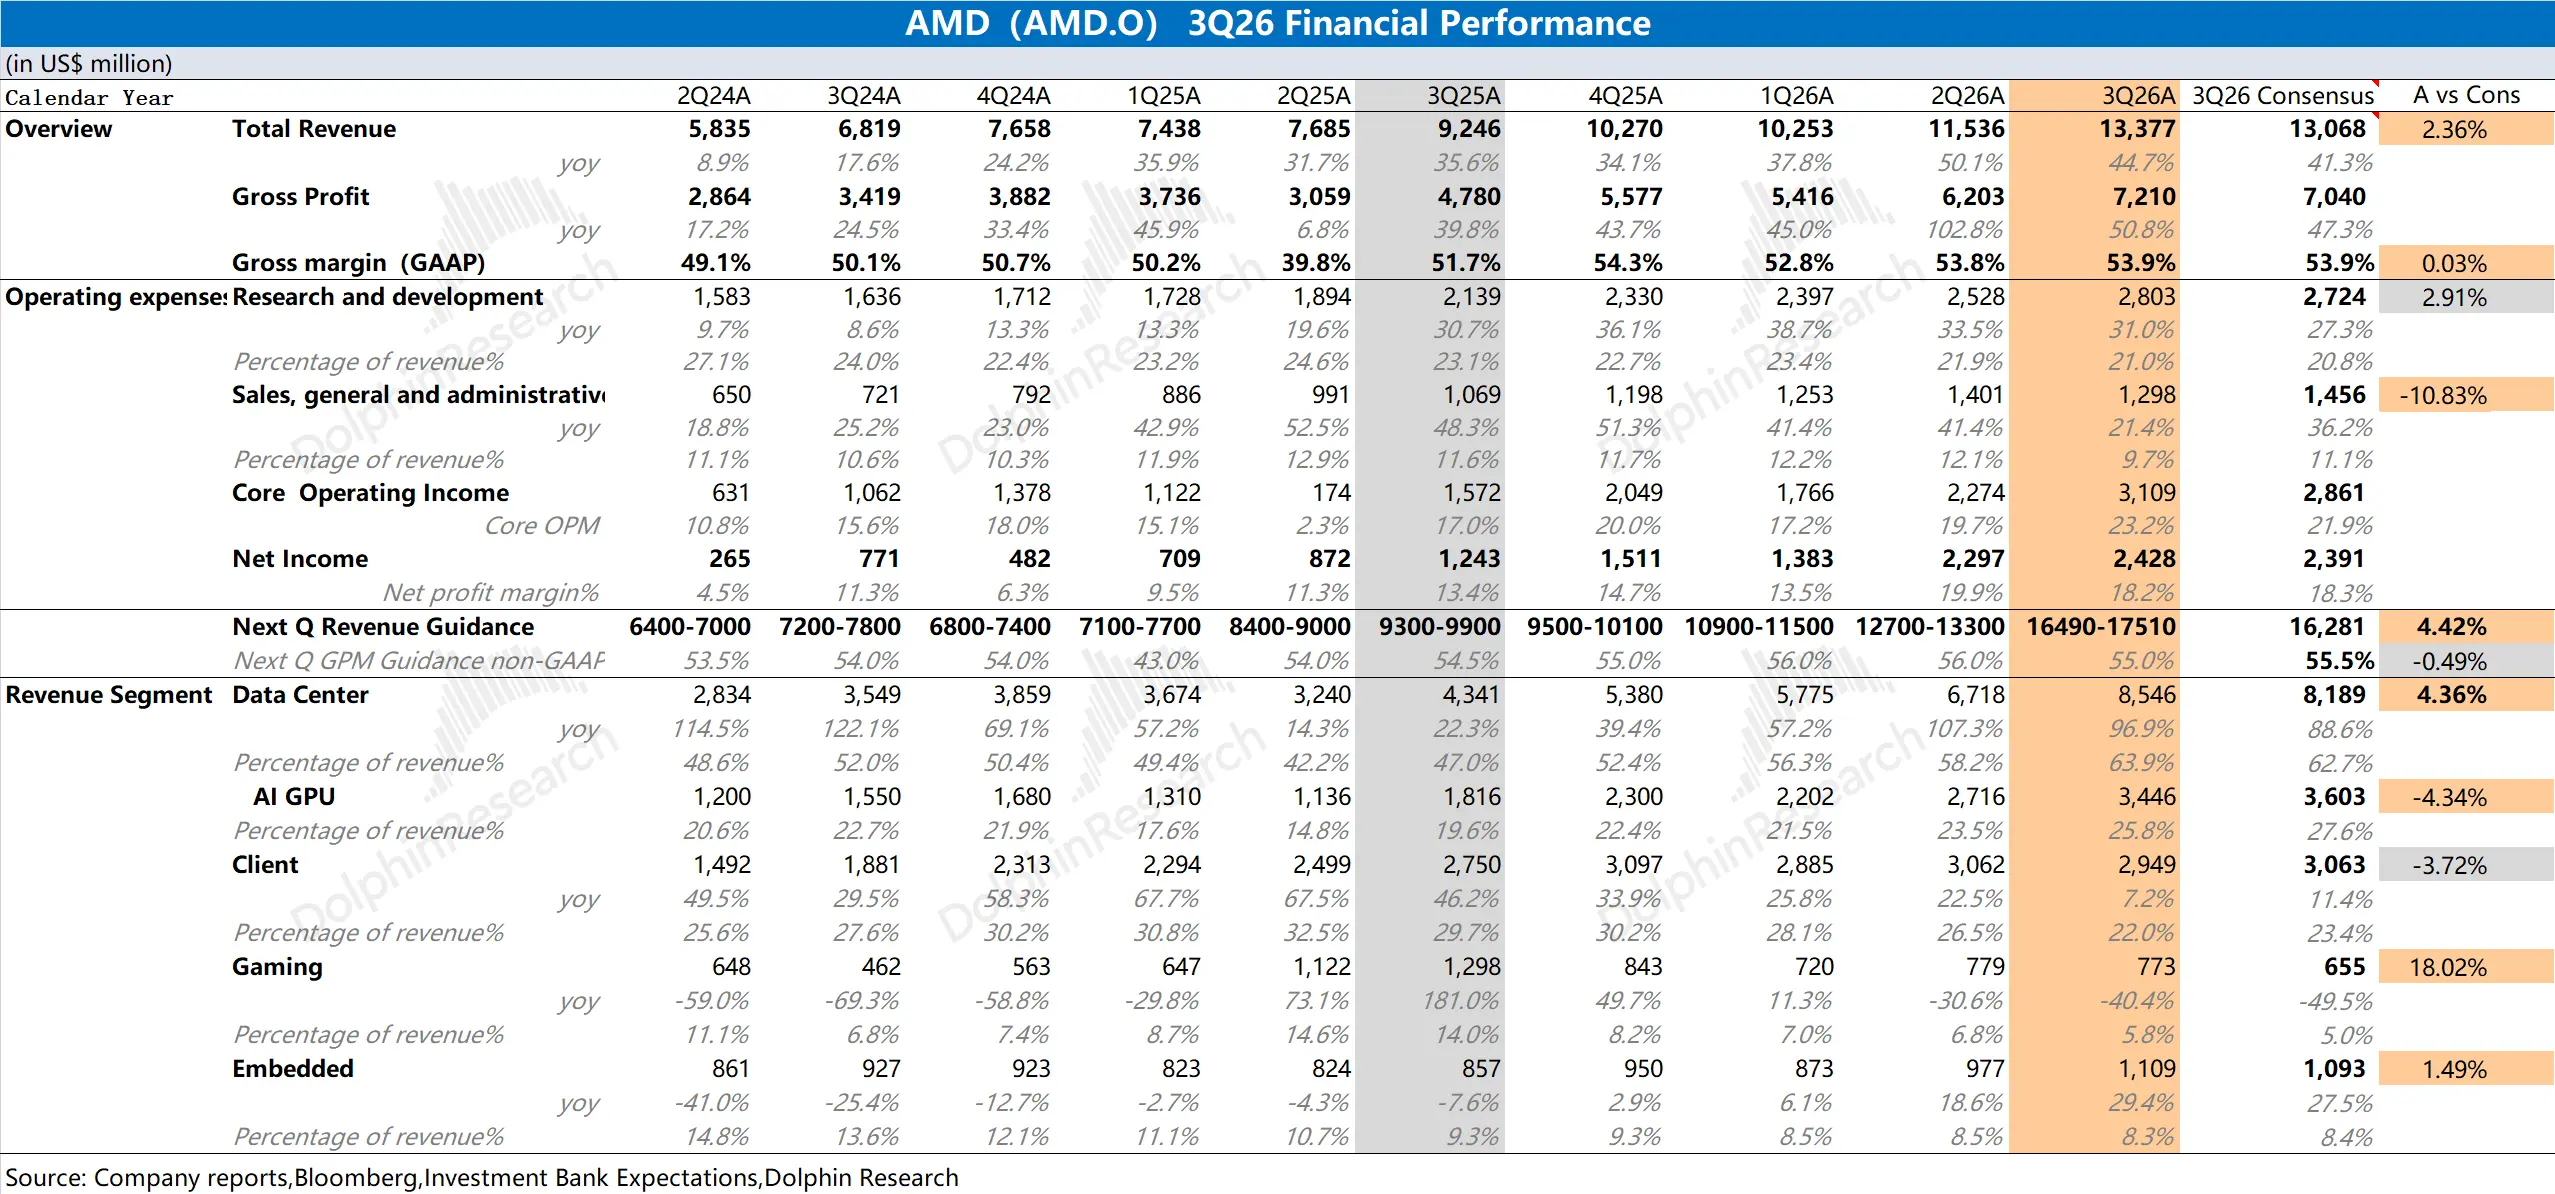
① Revenue: QoQ revenue rose by about $1.8bn, with all the incremental coming from Data Center and Embedded, while Client and Gaming declined QoQ. Dolphin Research estimates that within Data Center, server CPUs contributed more (~$5.1bn, doubled YoY), and AI GPUs were about $3.4bn, up roughly $0.7bn QoQ.
Client grew 7% YoY but turned down QoQ, coming in below expectations.Management said server growth was driven by unit shipments and core counts, with limited ASP contribution. In PCs, memory price hikes late in the quarter pressured sell-through, and the company proactively throttled shipments.
Dolphin Research sees this as reasonable: global PC shipments fell 17% YoY in the same period, Intel's client was -5% YoY, while AMD still grew and gained share, pointing to an industry beta issue. The company is planning for double-digit declines in PC shipments by 2027.
Client is shifting from a share-grab to falling less.② Margins: Non-GAAP GPM was 55.9%, flat QoQ and up ~190bps YoY, driven by a higher mix of server CPUs and Embedded, with limited dilution from small initial MI450 shipments. Opex came in below guidance, pushing OPM up ~500bps YoY to 29.3%.
This implies the profit driver is shifting from 'GPM' to 'operating leverage': in Q4, GPU scale will surpass CPU for the first time, GPM is guided down to 55%, yet Dolphin Research estimates OPM can still rise to around 33%. The prior concern that opex was growing faster than revenue was addressed this quarter.
③ Guidance: Q4 revenue guide mid-point at $17.0bn, about 4% above consensus, with Data Center up ~50% QoQ (~+$4.3bn) and Client and Gaming down more than 20%.
Dolphin Research estimates Q4 AI GPUs at about $7.0bn, doubling QoQ. However, this is the first full-shipment quarter for Helios with a concentrated ramp, and subsequent quarters remain supply-constrained by HBM, substrates, and other components.Longer-term guidance moved more at the margin: 2027 revenue growth is set to exceed 80%, over 2x the Analyst Day long-term model. Server growth was raised from 'over 70%' to 'doubling', and Data Center AI to 'significantly more than doubling'.
On visibility, management said power and data halls for 2027 have been planned with customers, and MI500 is being co-optimized at multi-GW scale with several frontier labs.Framework-wise, the company pegs server CPU TAM at about $220bn by 2030. It also committed that by 2027, opex growth will be less than half the pace of revenue growth.
Dolphin Research believes this quarter does not change AMD's mid-term logic of 'CPU as floor, GPU as baton': the first five Helios customers are live, and Dolphin Research estimates Data Center revenue could reach $80bn in 2027, above the market's roughly $70bn.
Investor focus has shifted from 'is there demand' to 'can Helios ship on time and what margins remain'. After-hours shares rose about 7%–8%, reflecting the above-guide outlook and confidence in the GPU handoff.
More info, follow Dolphin Research. A detailed review will follow. $AMD(AMD.US)
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.