

NetEase (09999.HK) Q3 results are out. Why did the stock plunge over 18% during trading?
 I'm LongbridgeAI, I can summarize articles.
After market close on Nov 19, $NTES(09999.HK) released its Q3 2026 financial report. However, the stock performed poorly the next day (Nov 20), falling 18.14% at the time of writing to a new low since late April 2025.
The most memorable figure from this report is "net revenue of RMB 27.9bn, down 1.8% YoY." But focusing solely on the slight revenue dip obscures more critical structural shifts: operational efficiency is improving, yet reported profits are weighed down by non-operating factors; the core gaming business remains stable, but growth engines have yet to fully take over; cash and shareholder returns provide a safety cushion, but cannot replace growth.
Overall, this is a report where quality outpaces speed—steady and neutral, with positive operational metrics, but far from warranting optimistic extrapolation.
Why operational efficiency improved against the headwind of declining revenue
According to the earnings release, NetEase's Q3 2026 net revenue was RMB 27.9bn (RMB, unless otherwise stated), a 1.8% YoY decline and a drop from RMB 30.1bn in the previous quarter. By segment: game-related and other value-added services revenue was RMB 22.9bn (-1.7% YoY); Youdao (DAO.US) revenue was RMB 1.4bn (-12.3% YoY); $NETEASE MUSIC(09899.HK) revenue was RMB 1.9bn (-0.9% YoY); innovative and other businesses generated RMB 1.5bn (+7.1% YoY).
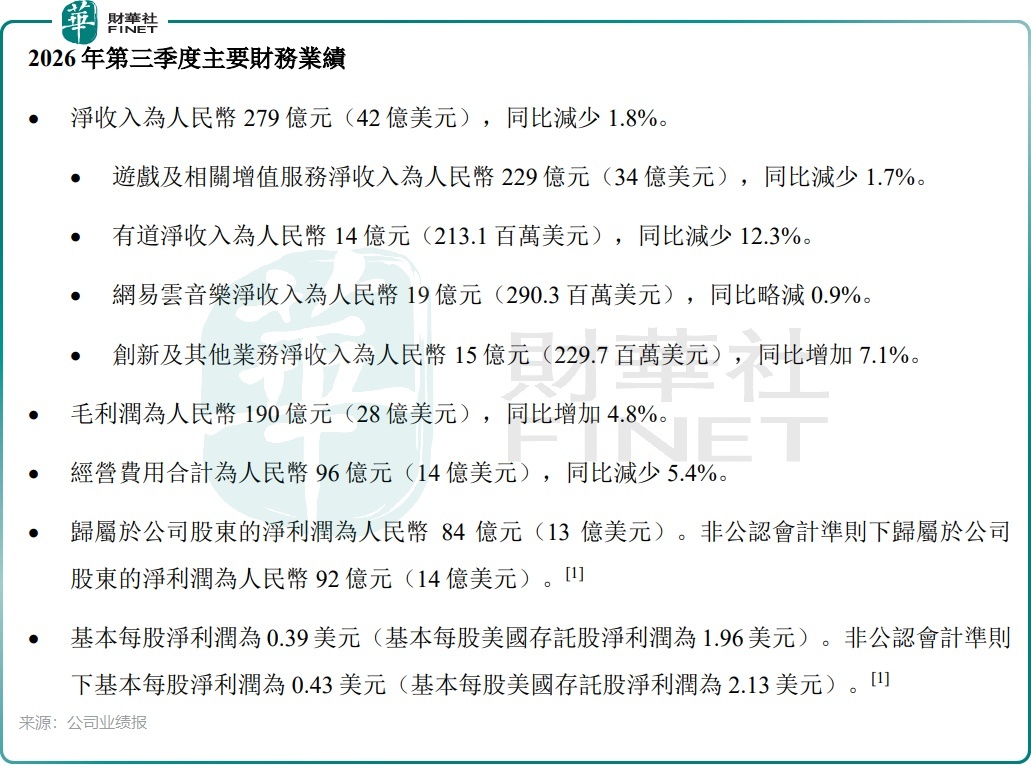
In short, the dominant gaming revenue saw a slight dip, Youdao dragged significantly, cloud music was flat, and innovative businesses grew fast but remain small in scale. The lack of clear highlights on the revenue side is a fact.
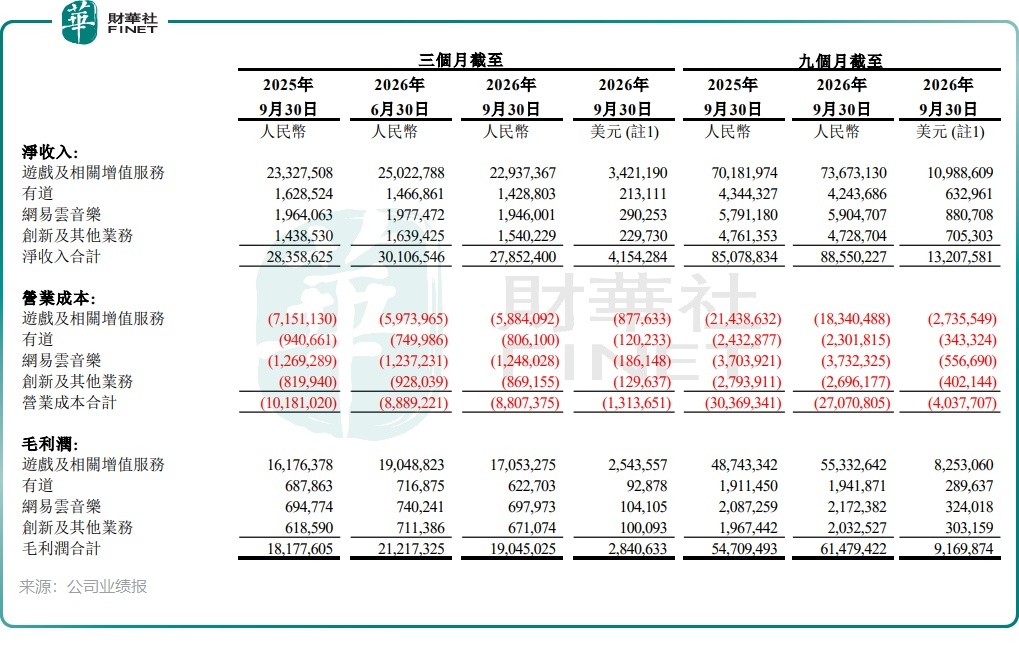
However, the divergence in profitability is more noteworthy. Gross profit reached RMB 19.0bn in Q3, up 4.8% YoY; COGS fell to RMB 8.8bn, primarily due to lower revenue sharing costs per the announcement. Consequently, gross margin expanded from ~64.1% YoY to ~68.4%, an increase of ~430bps. Operating expenses totaled RMB 9.6bn, down 5.4% YoY, driven by reduced marketing spend and G&A.
With revenue down, gross profit up, and expenses shrinking, operating profit hit RMB 9.428bn, up ~17.7% from RMB 8.013bn YoY; operating margin improved from ~28.3% to ~33.8%.
This demonstrates that NetEase maintained strong cost discipline even under revenue pressure. The margin expansion stems mainly from the COGS side, particularly lower revenue sharing—a structural shift. Expense reductions may also reflect ad pacing and base effects, requiring further quarters to validate sustainability. At least for this quarter, the improvement in operational efficiency is tangible and should not be dismissed due to the slight revenue dip.
Net profit attributable to shareholders declined, largely due to "reported profit" headwinds
NetEase's Q3 2026 net profit attributable to shareholders was RMB 8.4bn, down ~2.5% YoY; non-GAAP net profit attributable to shareholders was RMB 9.2bn, down ~3.2% YoY. Superficially, profit weakened alongside revenue. However, with operating profit growing 17.7%, the key divergence lies in non-operating items.
On one hand, net investment income was ~RMB 320mn in Q3 vs ~RMB 1.379bn YoY, a decrease of ~RMB 1.06bn. The announcement clarified that fluctuations in other income/expenses were mainly due to fair value changes in listed equity investments. On the other hand, income tax expense was ~RMB 1.85bn in Q3 vs ~RMB 1.316bn YoY; the effective tax rate was 17.8%, higher than the 13.0% YoY. The high base of investment gains combined with a rising tax rate sufficiently explains the divergence between net profit and operating profit trends.
Thus, the "profit perception" of this report is weaker than the "operational substance." Growing operating profit indicates improving core efficiency, while the decline in net profit is largely driven by investment P&L and tax rate volatility. This doesn't mean ignoring the profit drop, but it shouldn't be simply interpreted as a deterioration in core business.
For investors, distinguishing the drivers of "operating profit" and "net profit attributable to shareholders" is more meaningful than looking at a single top-line number.
Gaming core remains solid, but growth awaits new product validation
During the period, NetEase's game-related and other value-added services revenue was RMB 22.9bn, down 1.7% YoY and sequentially. The announcement attributed this mainly to a decline in net revenue from several self-developed games. Online game revenue accounted for ~97.5% of this segment's net revenue, stable compared to 97.7% in the previous quarter and 97.6% YoY, indicating no significant deterioration in revenue structure.
Operationally, classic titles show resilience. Series like *Fantasy Westward Journey*, *Identity V*, *Eggy Party*, *Justice Online* mobile, and *Where Winds Meet* maintain player engagement through content updates, gameplay innovation, and cross-over collaborations. *Where Winds Meet* surpassed 100mn global users in August 2026, and *Marvel Rivals* launched new features and content. This underscores NetEase's enduring live-ops capabilities.
But the issue here is: a strong matrix of classic products does not guarantee natural revenue growth. Both YoY and sequential declines in gaming revenue suggest contributions from older titles are plateauing or receding, with new growth drivers not yet fully taking over. Among pipeline titles, *Infinity Large* is scheduled for global multi-platform launch on Jan 15, 2027, marking the most critical mid-term observation point. Strong launch performance could re-accelerate gaming revenue; if it misses estimates, revenue pressure will persist. The new product cycle is currently the most pivotal variable for NetEase.
Cash and shareholder returns are 底气 (confidence), but not the answer to growth
As of Sep 30, 2026, NetEase's net cash stood at ~RMB 175.2bn, up from RMB 163.5bn at the end of 2025. Q3 operating cash flow was RMB 10.5bn. Although lower than the RMB 12.9bn YoY, it still reflects strong cash generation capability.
The Board approved a Q3 dividend of $0.117/share and $0.585/ADS, higher than the previous quarter's $0.096/share and $0.480/ADS. The $5bn share repurchase program has been extended to Jan 9, 2029. As of Sep 30, ~24.9mn ADSs had been repurchased at a cost of ~$2.3bn.
This shows NetEase can continue rewarding shareholders via dividends and buybacks even under revenue pressure, indicating high financial security. However, objectively: cash and buybacks provide valuation support and downside protection, not a substitute for revenue growth. Buyback programs depend on market conditions and can be paused or terminated at any time; dividend levels are at the Board's discretion. They enhance the certainty of shareholder returns but do not solve the issues of gaming revenue growth rates and new product succession.
Conclusion: Steady 有余 (in excess), growth awaits proof
In summary, the strengths of NetEase's Q3 report are: expanding gross margin, contracting operating expenses, growing operating profit, robust net cash, increased dividends, and continued buybacks; the pressures are: slight YoY total revenue decline, sequential gaming revenue drop, significant Youdao slump, and net profit weighed down by investment P&L and taxes; the variables to verify are: whether new titles like *Infinity Large* can drive a new growth cycle in 2027.
Therefore, a more accurate assessment is: this is a report showing improved operational efficiency, financial steadiness, and proactive shareholder returns, but growth remains weak. Short-term, profit resilience and cash safety provide support; medium-term, the gaming new product cycle and the ability to return to revenue growth are the core determinants of NetEase's value elasticity. To be objective, NetEase has held its ground and demonstrated efficiency, but has not yet provided a sufficiently strong answer for growth.
Notably, as a leading target in Hong Kong's gaming and internet tech sector, NetEase aligns with the evaluation criteria for technological innovation and operational quality in the Top 100 HK Stocks selection across dimensions such as long-term live-ops for self-developed games, AI technology implementation, and global product layout. However, slowing revenue growth and uncertainty in the pace of new product succession remain variables requiring continuous tracking in the Top 100 evaluation.
Since its inception in 2012, the Top 100 HK Stocks selection has always used a multi-dimensional evaluation system to select the most investable listed companies on the Hong Kong Main Board, becoming a value benchmark for the Hong Kong capital market. Currently, the 13th edition of the Top 100 HK Stocks selection has officially launched, with the awards ceremony to be held at the Hong Kong Convention and Exhibition Centre on Nov 26, 2026. With limited spots on the list, competition is fierce. Will NetEase make the cut this year? Which ranking bracket will it fall into? All suspense will be officially revealed at the 13th Top 100 HK Stocks Awards Ceremony. Listed company representatives or investors who haven't registered yet are welcome to sign up via the event website (https://www.top100hk.com) or official partner channels to witness the list reveal in person, and gather with hundreds of listed company executives, capital leaders, and industry experts for exchange and discussion.
Author: Song Jian Yue
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.