

JEPI

Dolphin Daily | Retail lifts neoclouds; Jensen Huang scandals weigh on NVIDIA again
 I'm LongbridgeAI, I can summarize articles.
It is Beijing time 2026-11-12. Dolphin Research brings you a one-glance take on global markets.

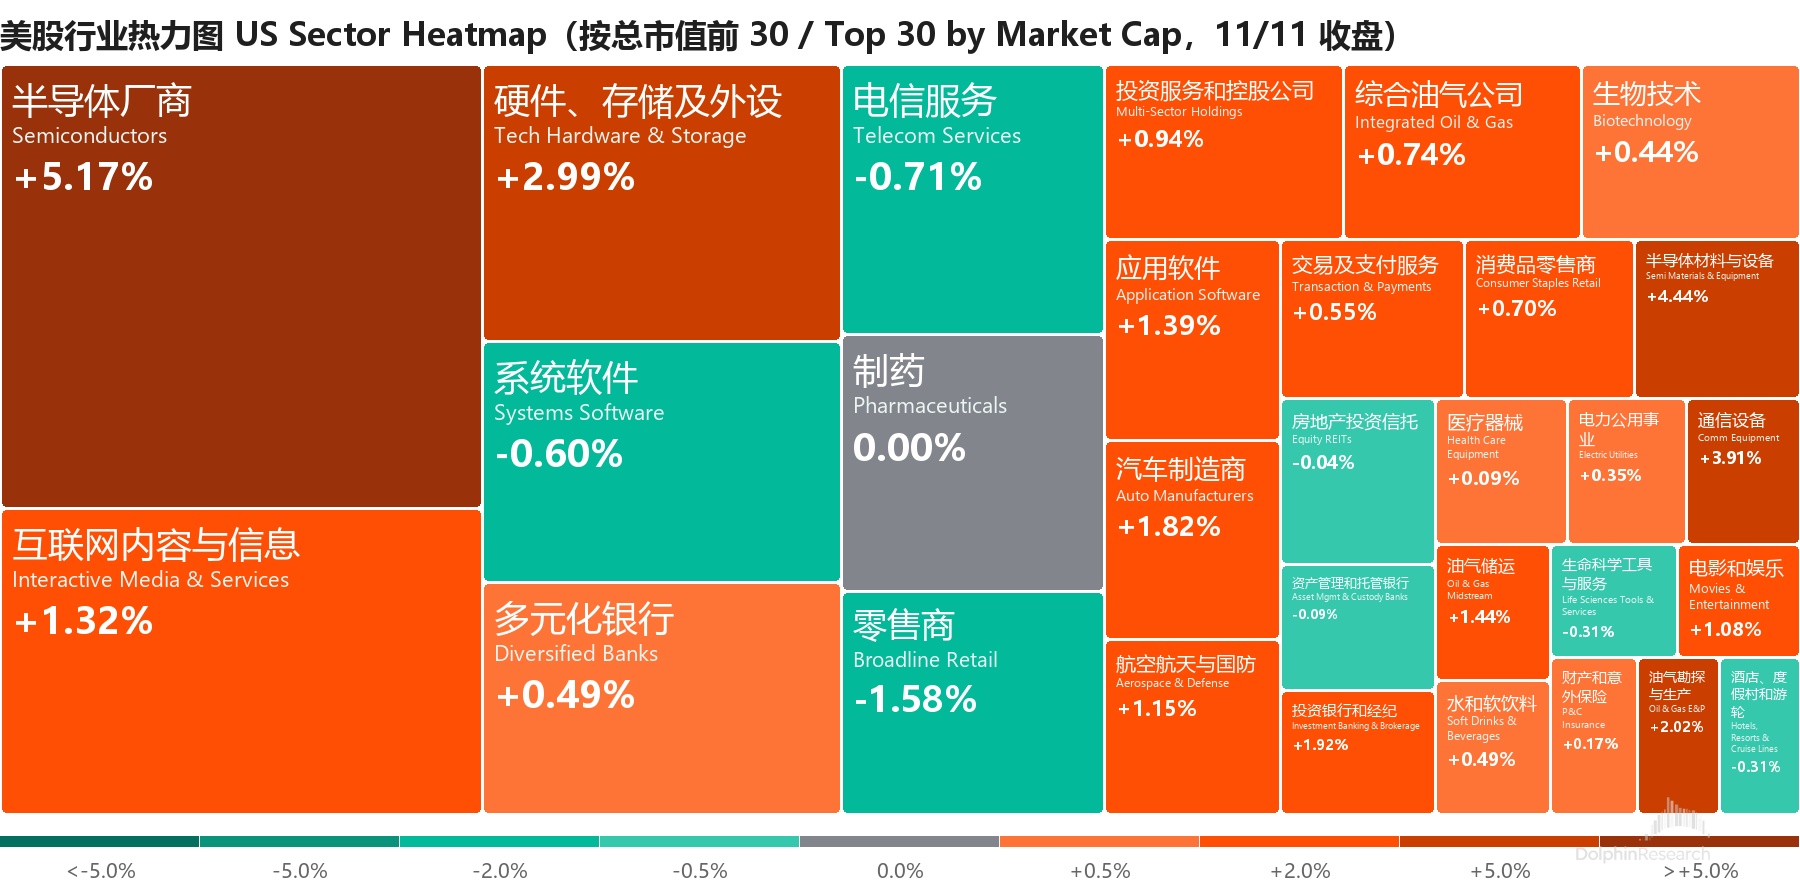
What’s trading: In a low-liquidity Veterans Day tape, upbeat CoreWeave earnings and a hot Anthropic book built momentum, with retail chasing AI and sparking a sharp snapback. SOX +5.7% with components broadly higher. CoreWeave +24.7%, Nebius +15.4%, while Micron and SanDisk each gained more than 11%.
After hours, WSJ said Nvidia’s BOD is preparing to remove Jensen Huang, with a decision as early as Wed; Nvidia did not immediately comment. The NYT also reported a second extramarital affair involving Huang and VP Kimberly Powell, who reports to him, noting they were seen being affectionate at a company event in Mar. Nvidia fell about 8% AH, and CoreWeave gave back ~7%.
Macro: With Veterans Day, UST cash was closed and the 10Y hovered near 5%. VIX fell 10% to 17.49.
Key movers: AMD +7.3%, TSMC +4.3%, Broadcom +4.0%, Oracle +8.8%, Dell +11.8%. Microsoft -2.3%, Meta -2.0%, Amazon -1.7%, as money rotated out of hyperscalers into chips and hardware.
Near-term watch:
Today: SMIC reports. In the U.S., Cisco, Applied Materials, Nebius, and Cerebras report; 30Y UST auction. Fri: U.S. Oct PPI. Next week: 11/17 Nvidia earnings; 11/18 Jensen Huang testifies before House committees and Anthropic prices AH, lists on 11/19.

$NVIDIA(NVDA.US) , $Coreweave(CRWV.US) , $Micron Tech(MU.US) , $Sandisk(SNDK.US) , $AMD(AMD.US) , $Broadcom(AVGO.US) , $Taiwan Semiconductor(TSM.US) , $Nebius(NBIS.US) , $Microsoft(MSFT.US) , $Alphabet(GOOGL.US) , $Amazon(AMZN.US) , $Oracle(ORCL.US) , $Dell Tech(DELL.US) , $ZJ INNOLIGHT(03308.HK) , $Alibaba(BABA.US) , $S&P 500(.SPX.US) , $NASDAQ-100(.NDX.US) , $iShares Semiconductor ETF(SOXX.US)

1. Nvidia board reportedly set to replace CEO: second affair alleged; stock -8% AH
Nvidia +2.9% (about -8% AH)
WSJ reported Nvidia’s BOD is preparing to oust Jensen Huang, with a meeting as soon as Wed to decide his status; Nvidia did not immediately respond. The NYT the same day reported a second affair involving Huang and Kimberly Powell, VP of healthcare who reports to him, saying they were seen acting intimately at a company event in Mar.
Before the headlines, Nvidia closed +2.9% to snap a two-day slide. Post-news, it fell as much as ~8% AH toward $160. CoreWeave -~7% AH, IREN -~6%, Micron -~3%, while Broadcom and AMD rose ~2%–3%.
Prediction markets are pricing the change: on Kalshi, the odds that ‘Jensen Huang steps down by Jan 1, 2027’ jumped from sub-20% on 11/10 to 70%, and ‘by Jul 1, 2027’ rose to 80%. Tae Kim, author of ‘The Nvidia Way’, said his view has shifted since writing the book, noting Nvidia has strong internal successors and there is a well-regarded external candidate. The typical path is to appoint an interim CEO, then choose from internal and external options.
Most institutions still argue Huang ‘is Nvidia’. Without him, they see Nvidia’s value 25%–30% lower.
2. AWS flags years of compute tightness: chips rip in a violent rebound; new clouds lead
CoreWeave +24.7% (about -7% AH) / Nebius +15.4% / SanDisk +13.7% / Micron +11.9% / AMD +7.3% / IREN +5.6%
AWS CEO Matt Garman said on a podcast that even with current capex, AWS will still be short compute for years, with demand far outpacing supply. He views new-cloud debt risks as idiosyncratic, not systemic.
Dolphin Research take: CoreWeave’s biz is improving, with tight demand, rising prices, and higher margins. But debt rose another ~$12bn in a quarter, and interest expense still exceeds adj. OP. The market is really pricing the post-2027 demand path and whether compute rentals roll over. After a big drawdown plus solid results, the stock deserved a reward, but that doesn’t mean bears are capitulating; the long-term story for new clouds remains fragile. (Earnings take)
3. Anthropic book multiple times covered, eyeing a higher IPO price, but first-quarter guide already ‘under-shoots’ run-rate
Google +2.1% / Amazon -1.7% / Microsoft -2.3%
Per the FT, the GS and MS-led syndicate is considering pricing above the $70–78 range, with day-one institutional orders covering the full band. At a higher price, valuation could reach about $1.5tn.
Books are multiple times covered. Watch the unlock cadence: some investors can begin selling from day 27 post-listing.
Dolphin Research take: a sell-side huddle pegs Anthropic’s Q4 annualized at $77.2bn, below the Oct ARR of $81bn, so the first public-quarter guide trails the run-rate. Linear extrapolations on high-frequency ARR effectively compound second derivatives, which is why valuation swung from $0.9tn to $2tn, then $1tn, and now seeks $1.5tn, lacking a terminal, conviction anchor. (Original note)

1. Hike path: Dec hike seen locked; tightening may run into 2027 (11/11)
Fed path: GS, Nomura, and Deutsche Bank all raised their hike-path forecasts on the same day, and the market has fully priced a 25bp hike in Dec. Some foreign dealer desks still see a 50bp chance, with tightening into 2027, and FF futures price two hikes by Mar next year.
USTs: With Veterans Day, UST cash was shut; futures imply the 10Y back above 5%. On Thu, there is a $25bn 30Y auction, and Fri brings PPI (JP Morgan sees headline +0.6%, core +0.4%).
Crude: Iran’s IRGC said two tankers hit mines in the Strait of Hormuz. Iran also refuses to ship out enriched uranium and set seven conditions to reopen the Strait. Brent +1.4% to $92.76. Gold broke below $4,000 as hike expectations pressured the metal.
2. Higher-vol assets (11/11)
VIX -10.1% to 17.49: chips ripped in a sharp rebound, easing fear. DXY +0.66% to 102.908: the highest since Apr 2025 on a higher hike path.
3. Asia open and today’s setup (11/12)
Asia open (11/12): Nikkei 225 +0.4% at the open; KOSPI +0.2% at the open. TWSE opens at 09:00. HSI futures -0.7% overnight; FTSE A50 futures +0.1%.
Memory visibility is improving: S. Korea’s Nov 1–10 semiconductor exports rose +331% YoY to $16.6bn. SK Hynix ADRs listed in the U.S. rose +9.7% on Wed → memory names have LTAs and export data as a backstop, partly hedging Nvidia risk.
YMTC eyes an IPO: Bloomberg says Yangtze Memory could list on STAR as early as Q1 2027, seeking RMB 33bn. By shipments it has surpassed Kioxia and Micron to become the No.3 NAND maker globally, is ramping DRAM, and moving toward HBM.


AMD +7.3% / TSMC TSM +4.3% / Broadcom AVGO +4.0%
After the Nvidia headlines, TSMC ADRs fell 2.6% AH, while AMD and Broadcom rose ~2.7% and ~2.0%, respectively.
TSMC co-COO YP Chao told Nikkei that client demand for cutting-edge nodes is ‘insatiable’, as they aim to grab any compute they can get.
AMD: next-gen Helion racks start shipping in Nov via Foxconn, Quanta, Wiwynn, Inventec and Gigabyte. Anthropic said Claude Mythos took about three days to port to MI355X.
Arm +12.1% / Marvell +9.3% / Cerebras CBRS +7.9% / Intel INTC +7.5%
Followed a broad rebound in semis.

SanDisk SNDK +13.7% / Micron MU +11.9% / Seagate STX +10.0% / Western Digital WDC +8.3%
Majors are locking LTAs: SK Hynix signed five-year deals with 14 key customers covering over half of 2027–28 capacity; Samsung aims to have 60%–70% of mid-to-LT supply under LTAs. Micron has 26 strategic customer agreements with $32bn in total commitments.

Meta META | $1.61tn | -2.0%
Sold alongside Microsoft and Amazon, as flows rotated toward chips and hardware.
Apple AAPL | $5.17tn | +2.0%
Hit an all-time intraday high.

Dell DELL +11.8% / Super Micro SMCI +9.5%
Rallied with the AI hardware complex.

Bloom Energy BE +13.0% / Vertiv VRT +6.3%
CoreWeave’s print eased concerns over data-center build financing. Bloom Energy was up as much as ~16% intraday.

Alibaba BABA
HKEX has approved the Pingtouge spin-off; it still awaits Listing Committee approval and CSRC filing. Per Morgan Stanley, Pingtouge could ship 700k GPUs in 2027, largely for internal use. Alibaba aims to lift Pingtouge’s share of its own compute from 10%+ to 40%–50%; the next-gen PPU V900 delivers 3x M890’s performance and targets commercial rollout in Q1 2027.

Tesla TSLA | $1.54tn | +2.9%
Rose with tech; no stock-specific headlines.
Hesai HSAI | +1.8%
Dolphin Research take: share loss matters too; Hesai’s China long-range ADAS share was 43% in Sep, down from 55% in Mar. But ASP stabilization is the key positive this quarter, and management says with 2025 contracts in hand, ADAS pricing is turning rational, with ATX pricing and GPM to further stabilize in 2027. (Earnings take)


| Date | Event | Focus |
| Thu, 11/12 | SMIC earnings; U.S. earnings: Cisco, Applied Materials, Nebius, Cerebras; $25bn 30Y UST auction | See earnings preview below |
| Fri, 11/13 | U.S. Oct PPI | JP Morgan est. headline +0.6%, core +0.4% |
| 11/16–19 | Earnings: BIDU (11/16), Nvidia (11/17), Tencent (11/18), Alibaba and Lenovo (11/19) | Nvidia BOD’s decision on Jensen Huang and commentary on 2027 orders |
| Wed, 11/18 | Jensen Huang testifies before three House committees; Anthropic prices AH | Whether the IPO prices above the range |
| Thu, 11/19 | Anthropic lists on Nasdaq (ANT) | Can day-one trade keep the AI funding window open |

Applied Materials AMAT | AH on 11/12
Focus: Morgan Stanley ranks equipment third on its buy list, preferring Lam, MKS, and AEI, with AMAT at Equal-weight. As long as 2027 WFE isn’t guided down, capital returns remain the core equipment bull case.
What we watch: DRAM and advanced packaging tools, China revenue mix, and 2027 WFE outlook.
Nebius NBIS | AH on 11/12
Focus: After CoreWeave posted $132.5bn in backlog, Nebius rose 15.4% Wed, then slipped ~5% AH on the Nvidia headlines. It needs to address concerns that Microsoft is trimming new-cloud partnerships, plus updates on bookings, funding costs, and delivery cadence.
What we watch: new bookings and backlog, annualized revenue guide, and capex and financing plans.
<Ends here>
Recent daily recaps
2026-11-11: Daily | Nvidia -5% again; 50bp back on the table; new clouds on trial, again?
2026-11-10: Daily | Big AI rebound day, with only ‘wayward Jensen’ shunned
Risk disclosure and disclaimer: Dolphin Research Disclaimer and General Disclosure
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.