
$Anthropic(ANT.US)Background: Anthropic listed on Nasdaq this week, the most anticipated AI IPO of the year, but it coin…
$Anthropic(ANT.US)
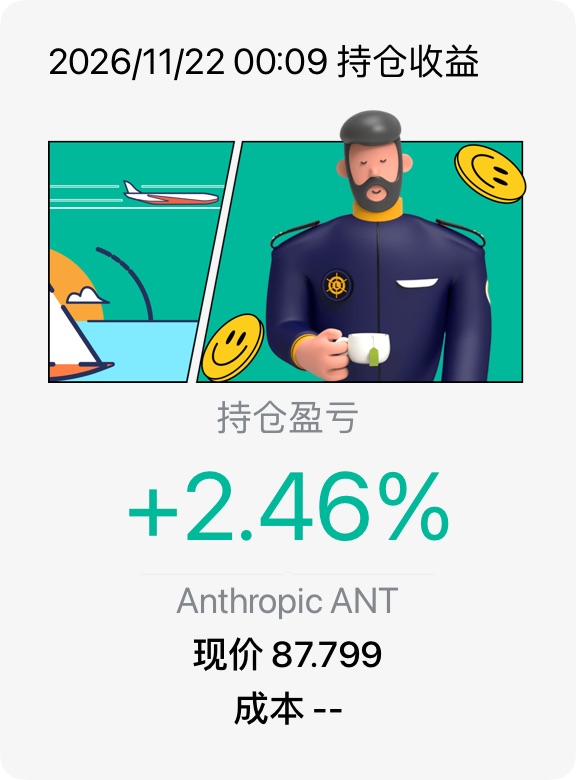
Background: Anthropic listed on Nasdaq this week, the most anticipated AI IPO of the year, but it coincided with the worst week for tech stocks since 2020—NVIDIA plunged due to an SEC investigation into its accounting practices, triggering a sell-off across the entire AI sector. When I took a position in this stock, my focus was on whether the "model capability → enterprise subscription revenue" chain could be validated by earnings reports, rather than 首日 sentiment.
My thinking: In the early stages of an IPO, pricing power lies mainly with sentiment and liquidity, while fundamental information is often the least complete. Anthropic disclosed nine months of revenue growth exceeding 12x YoY, with an annualized scale that is already quite substantial, yet it still reports operating losses—high growth and high burn rate are two sides of the same coin. Therefore, I focused my observation on two things: whether enterprise renewals can sustain the revenue curve, and how long the cash reserves can support compute and R&D spending.
Takeaway: The price in the first week of an IPO resembles a vote on the "narrative" more than a valuation of the company. I remind myself not to reverse-engineer company value based on 首日 gains or losses, nor to dismiss a long-term thesis because of a one-week drop. My approach is to treat it as a security where "information is still filling in," rather than making a one-time bet.
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.