D
 +12
AMD: Not Following INTC; Helios Ramps to Take the Spotlight
Helios ramped up, offsetting the PC drag. It even left room to spare.
+12
Helios ramped up, offsetting the PC drag. It even left room to spare.
+12Q4 revenue guide is approx. $17.0bn, with data center up ~50% QoQ. Demand still outstrips supply.
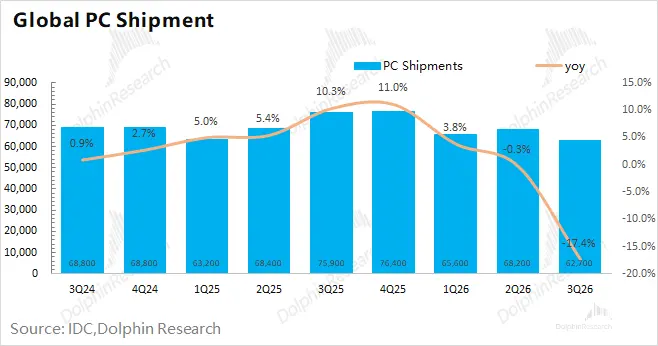
For 2027, revenue is expected to grow >80%, and server revenue to double. The company is planning for a double-digit decline in the PC market next year and stepping up R&D and supply-chain investment, betting on multi-GW deployments of Helios and MI500.
On Muse's impact on CPUs, there is a different take circulating on X: 'In a base case, serving 100 mn DAUs requires ~1 GW of power, and only ~0.1 GW comes from the CPU/VM layer.' Depending on how many inference-equivalent model calls each Muse DAU generates per day, 3–4 GW makes complete sense. ...
Meta launched Muse on Sep. 8. Each Muse runs on a dedicated virtual machine, the Muse Secure VM, which stores both the agent and user data. Long-running jobs keep executing even after the app is closed, then re-engage the user when something changes or an approval is needed.
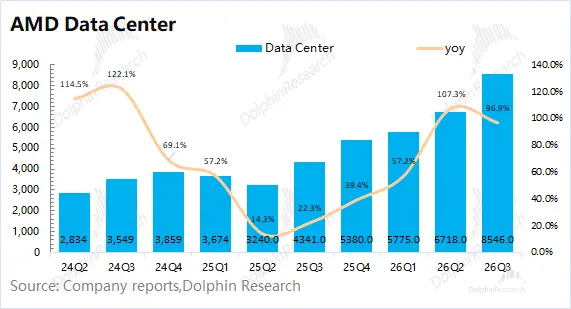
The product went viral, briefly topping the US mobile download charts. For details on Muse and its implications for Meta, see Dolphin Research's take 'Muse goes viral: real inflection or hype peak?'...AMD released its Q2 2026 results (quarter ended Jun 2026) after the U.S. close on Aug 5 (Beijing time). Revenue was $11.54bn, +50% YoY, slightly above consensus ($11.3bn). Growth reaccelerated, driven mainly by a doubling in the Data Center biz.
GAAP GPM was 53.8%. Prior-year comps were affected by an approx $0.8bn impairment related to China restrictions...Revenue of $11.5bn (+50% YoY). Data center revenue doubled to $6.7bn, lifting mix to 58%. 2027 guidance for data center is 'well above a doubling'.
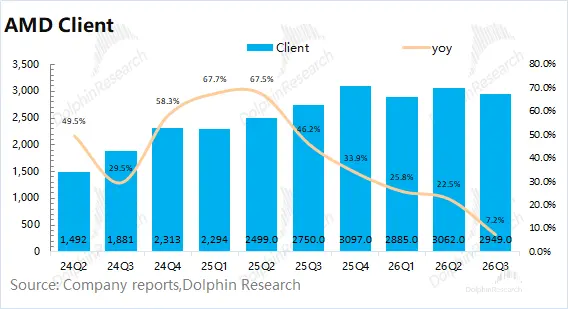
However, gaming revenue fell 31% YoY. Client and Gaming OPM declined to 15% from 21% YoY. The company raised its 2030 AI accelerator TAM to $1.4tn. It said EPS will significantly exceed the $20 target.Below is Dolphin Research's Trans of AMD's FY26 Q1 earnings call. For our analysis, see 'CPU in Overdrive, Helios Near, Is AMD Finally Breaking Through?'.
I. Key highlights from the print. 1) Shareholder returns: repurchased 1.1 mn shares this quarter, returning $221 mn to shareholders. $9.2 bn remained under the buyback authorization at quarter-end.2) Outlook: Q2 FY26 revenue guided to approx. $11.2 bn (+/- $0.3 bn). Implies a range of $10.9–$11.5 bn...AMD reported its Q1 2026 results after the U.S. market close on May 6 (Beijing time). The quarter covered the period ended Mar 2026. Key takeaways:
1) Overall results: $AMD(AMD.US) delivered revenue of $10.25bn (+37.8% YoY), beating market est. of $9.9bn. Growth was led by Data Center and Client.
GAAP GPM was 52.8%. It expanded 260bps YoY...
Below is Dolphin Research's transcript of AMD's Q4 2025 earnings call. For earnings analysis, see 'Another Loud Thunder, Little Rain! When Will AMD Step Up?'
Key call takeaways: 1) Next quarter guidance: revenue of $9.8BN (±$300mn), incl. ~$100mn from MI308 sales in China; non-GAAP GPM ~55%. Data center biz grew QoQ, while other segments saw seasonal declines. 2) Data center outlook: Server CPU won't see typical seasonal weakness...AMD released Q4 2025 results (quarter ended Dec 2025) after hours on Feb 4, 2026 Beijing time. Revenue was $10.27bn (+34.1% YoY), beating the raised consensus of $10.0bn.
Amid a recent rebound in server CPUs, the Street has lifted its forecasts. This quarter's topline growth was driven mainly by data center CPUs and the Client segment...