D
 +3
Finally put numbers to guidance — why isn't AMAT moving?
Short-term slowdown won't derail a strong year; mgmt more confident.
+3
Short-term slowdown won't derail a strong year; mgmt more confident.
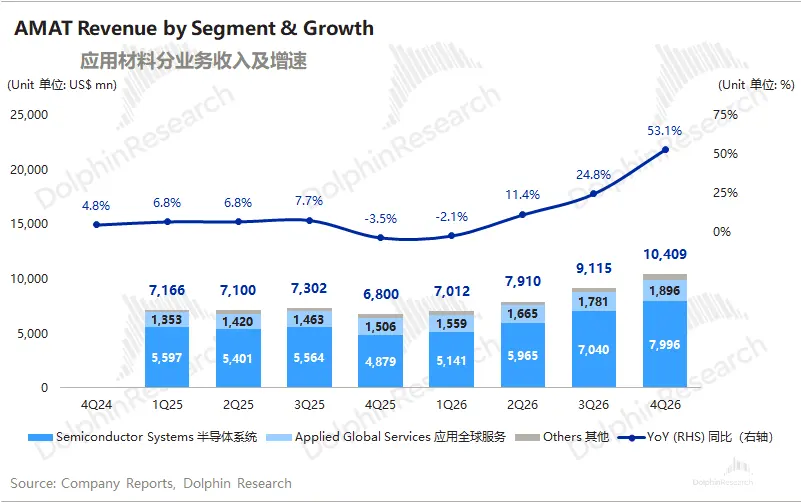
+3FQ4 revenue hit a record $10.4bn, and FQ1 revenue guidance implies a midpoint of $11.1bn (+58% YoY).
Management expects WFE to grow over 30% by 2027, with the company continuing to outperform.
However, cleanroom and supply-chain bottlenecks are still constraining shipments, and FQ1 could have been slightly higher.Meanwhile, the company is investing to double system output capacity vs. FQ4 by 2028.
Below is Dolphin Research's Trans from AMAT's 2026 SEMICON West investor tech session.
Key takeaways: AI is concentrating incremental WFE on the company's leading positions in advanced logic, DRAM, and advanced packaging. By 2030, management targets GPM of 54%, OPM of 40%, and 200bps+ share gains. However, it gave no WFE outlook and flagged that cleanroom and supply-chain constraints could make growth uneven, while betting on EPIC and AIx services to drive yield innovation...Applied Materials (AMAT) reported its FY26 Q3 results post-market on Aug 14, 2026 Beijing time, covering the quarter ended Jul 2026. Key takeaways follow: 1) Core metrics:
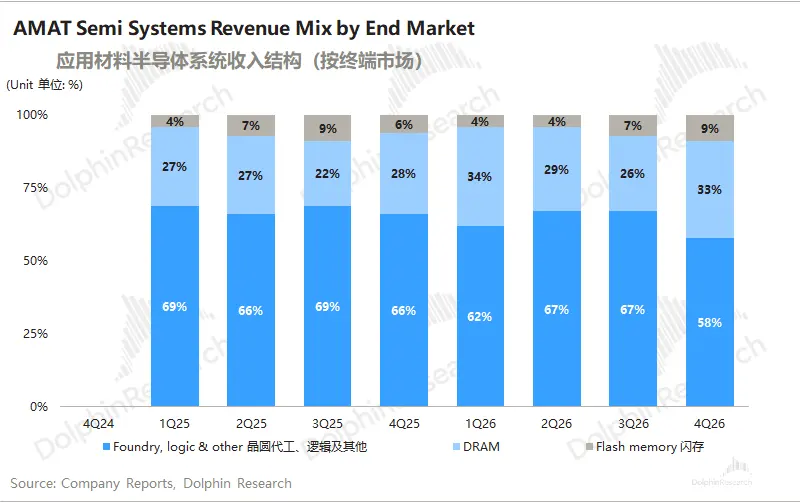
Revenue was $9.12bn (+25% YoY), slightly above the Street’s $9.02bn. Growth was fueled by the build-out of AI compute infrastructure, which boosted demand for advanced logic, DRAM, and advanced packaging equipment.
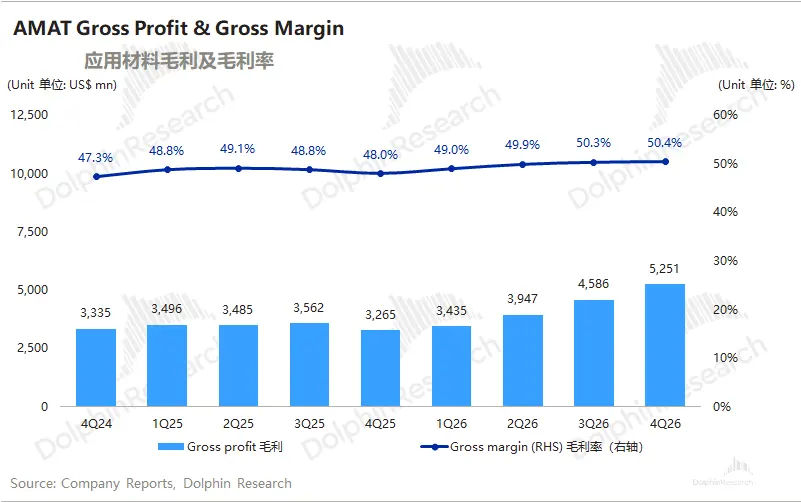
GPM was 50.3%. It improved by 40bps QoQ...
Q4 revenue guidance is $10.25bn (+51% YoY), and calendar-year growth in semiconductor systems has been raised again from '30%+'.
Q4 GPM is guided to be roughly flat at about 50.4%, as ramp costs from capacity expansion and hiring offset volume and pricing benefits, with the company pre-building capacity to double quarterly system shipments by 2028.The following is Dolphin Research's transcript of AMAT FY26 Q2 earnings call. For our takeaways, see 'Capex Boom Underway: Can AMAT Capture the Windfall?'.
I. Key highlights from $Applied Materials(AMAT.US) results.1) Capital returns: Returned $765 mn to shareholders this quarter, incl. $365 mn in dividends and $400 mn in buybacks. In Mar, the company raised its quarterly dividend by 15%, meeting its prior target of doubling the dividend per share...Applied Materials (AMAT) posted its FY26 Q2 results (quarter ended Apr 2026) after hours early May 15 (Beijing time), with the following highlights: 1) Core metrics: revenue of $7.9bn (+11% YoY), beating the Street at $7.7bn, driven by AI compute infrastructure build-out that lifted demand for advanced logic, DRAM, and advanced packaging tools. $Applied Materials(AMAT.US) GPM was 49.9%, up 90bps QoQ...
Below is Dolphin Research's AMAT FY26 Q1 earnings call Trans. For our earnings take, see 'AMAT: Capex super-cycle is here; it's springtime for WFE'.
Key takeaways: 1) 2026 outlook: the semi equipment (WFE) biz is expected to grow over 20% this calendar year, with demand weighted to 2H. NAND and ICAPS will grow more slowly, with ICAPS roughly flat. Services to grow at a low-teens pace (11–15%).Customer cleanroom space availability remains the key gating factor for capex cadence. It is driving adjustments to the pace of investments...Applied Materials (AMAT.O) posted FY2026 Q1 results (quarter ended Jan 2026) after hours on Feb 13 Beijing time; highlights as follows: 1) Core metrics: $Applied Materials(AMAT.US) reported revenue of $7.0bn, down 2% YoY and in line with consensus (~$7.0bn), reflecting a tough comp in the semi equipment biz last year.
Positively, DRAM and Services delivered double-digit growth this quarter. GPM was 49%, up 100bps QoQ and ahead of the Street (48.4%)...Dolphin Research’s prior deep dive on AMAT outlined the company’s core product lines and its positioning across key equipment sub-sectors.
This note links AMAT’s outlook and valuation to wafer fab capex trends.As $Applied Materials(AMAT.US) operates in semiconductor equipment at the top of the value chain, its demand is highly sensitive to upstream investment cycles.
Its customers are wafer fabs across logic (TSMC, Intel) and memory (Samsung, SK hynix).Hence, our forecasts for AMAT’s performance...