D
 +21
Anthropic: Can't escape 'intelligence deflation' — endgame: AI Google or AT&T?
IPO pricing looks reasonable. But 'cognitive deflation' is compressing the future profit pool.
+21
IPO pricing looks reasonable. But 'cognitive deflation' is compressing the future profit pool.
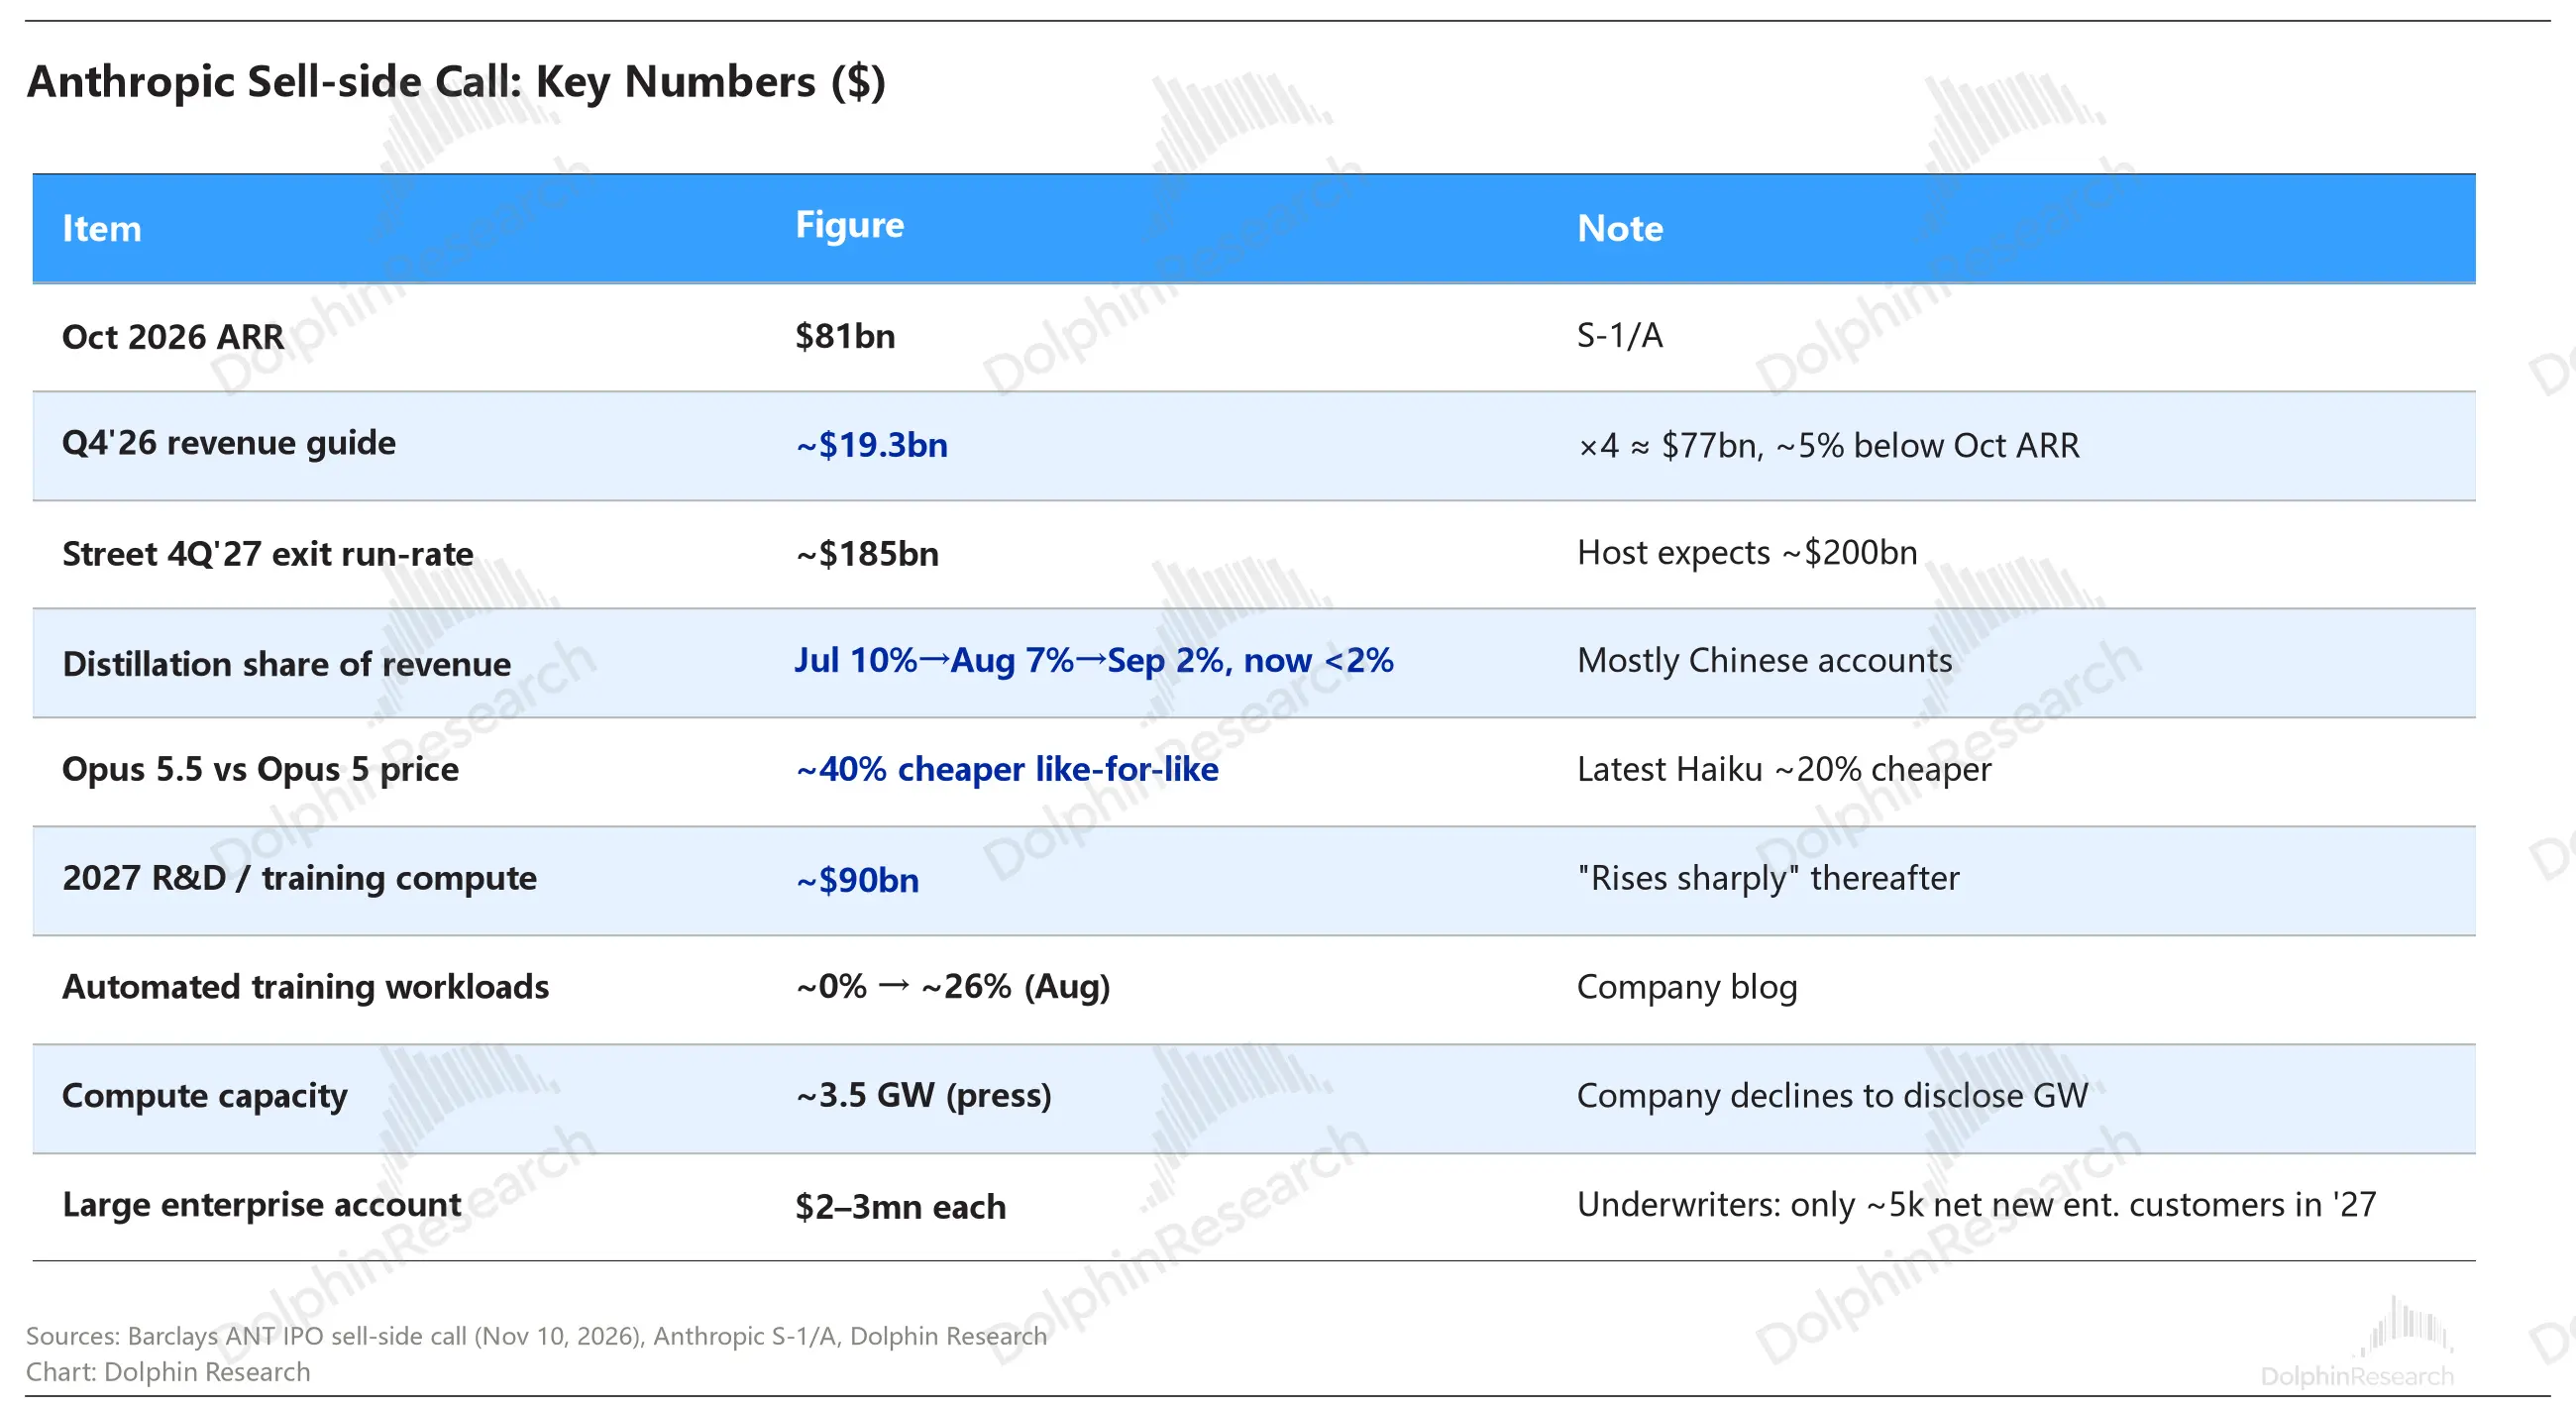
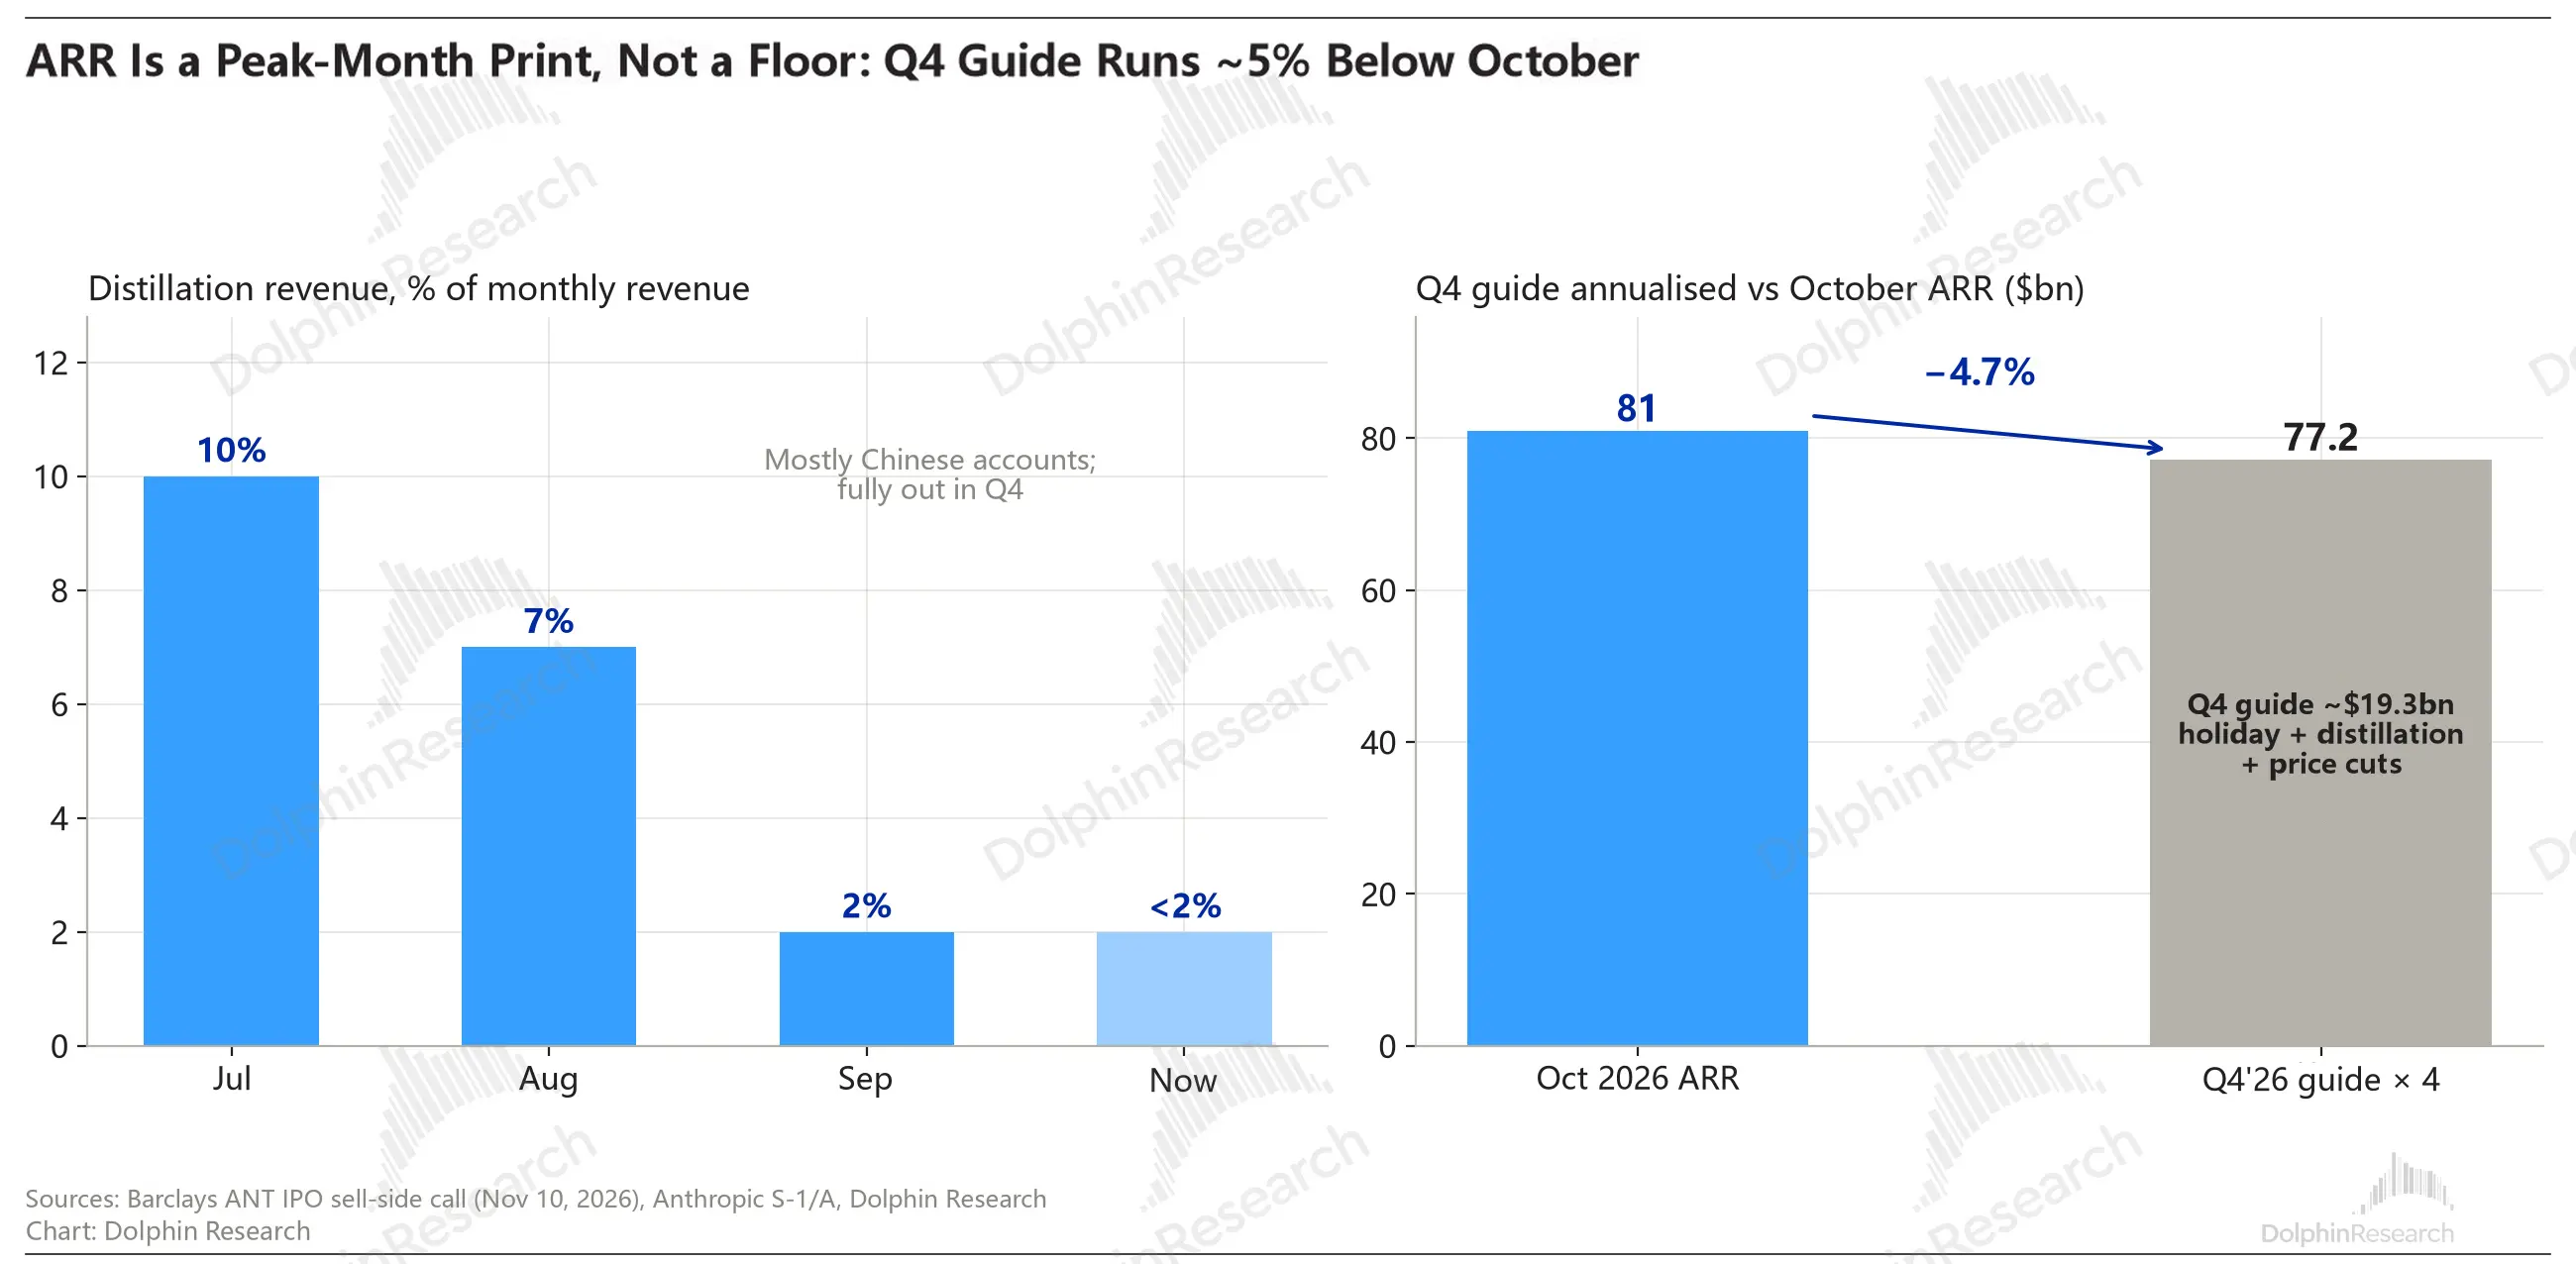
+21On Nov 10, two sell-side analysts from $Anthropic(ANT.US)'s IPO syndicate (one covering software, one internet) hosted a Q&A. Although some key figures were their own estimates, the timing suggests a degree of management endorsement, making it a useful read-through for Anthropic's near- to mid-term growth outlook. Dolphin Research's takeaway: soft near term but more upbeat over the medium to long run (vs. already-trimmed expectations), underscoring a company with bold monetization ambitions.
 +2
On Oct 26, $Anthropic.US finally filed its prospectus. The opening page reads like a study in contrasts. Dolphin Research wrote in Jan in 'Deep Dive on Minimax and Zhipu: Large Models...'
On one hand, Q2 revenue was $11.56 bn (+14x YoY). It posted GAAP operating profit for the first time.
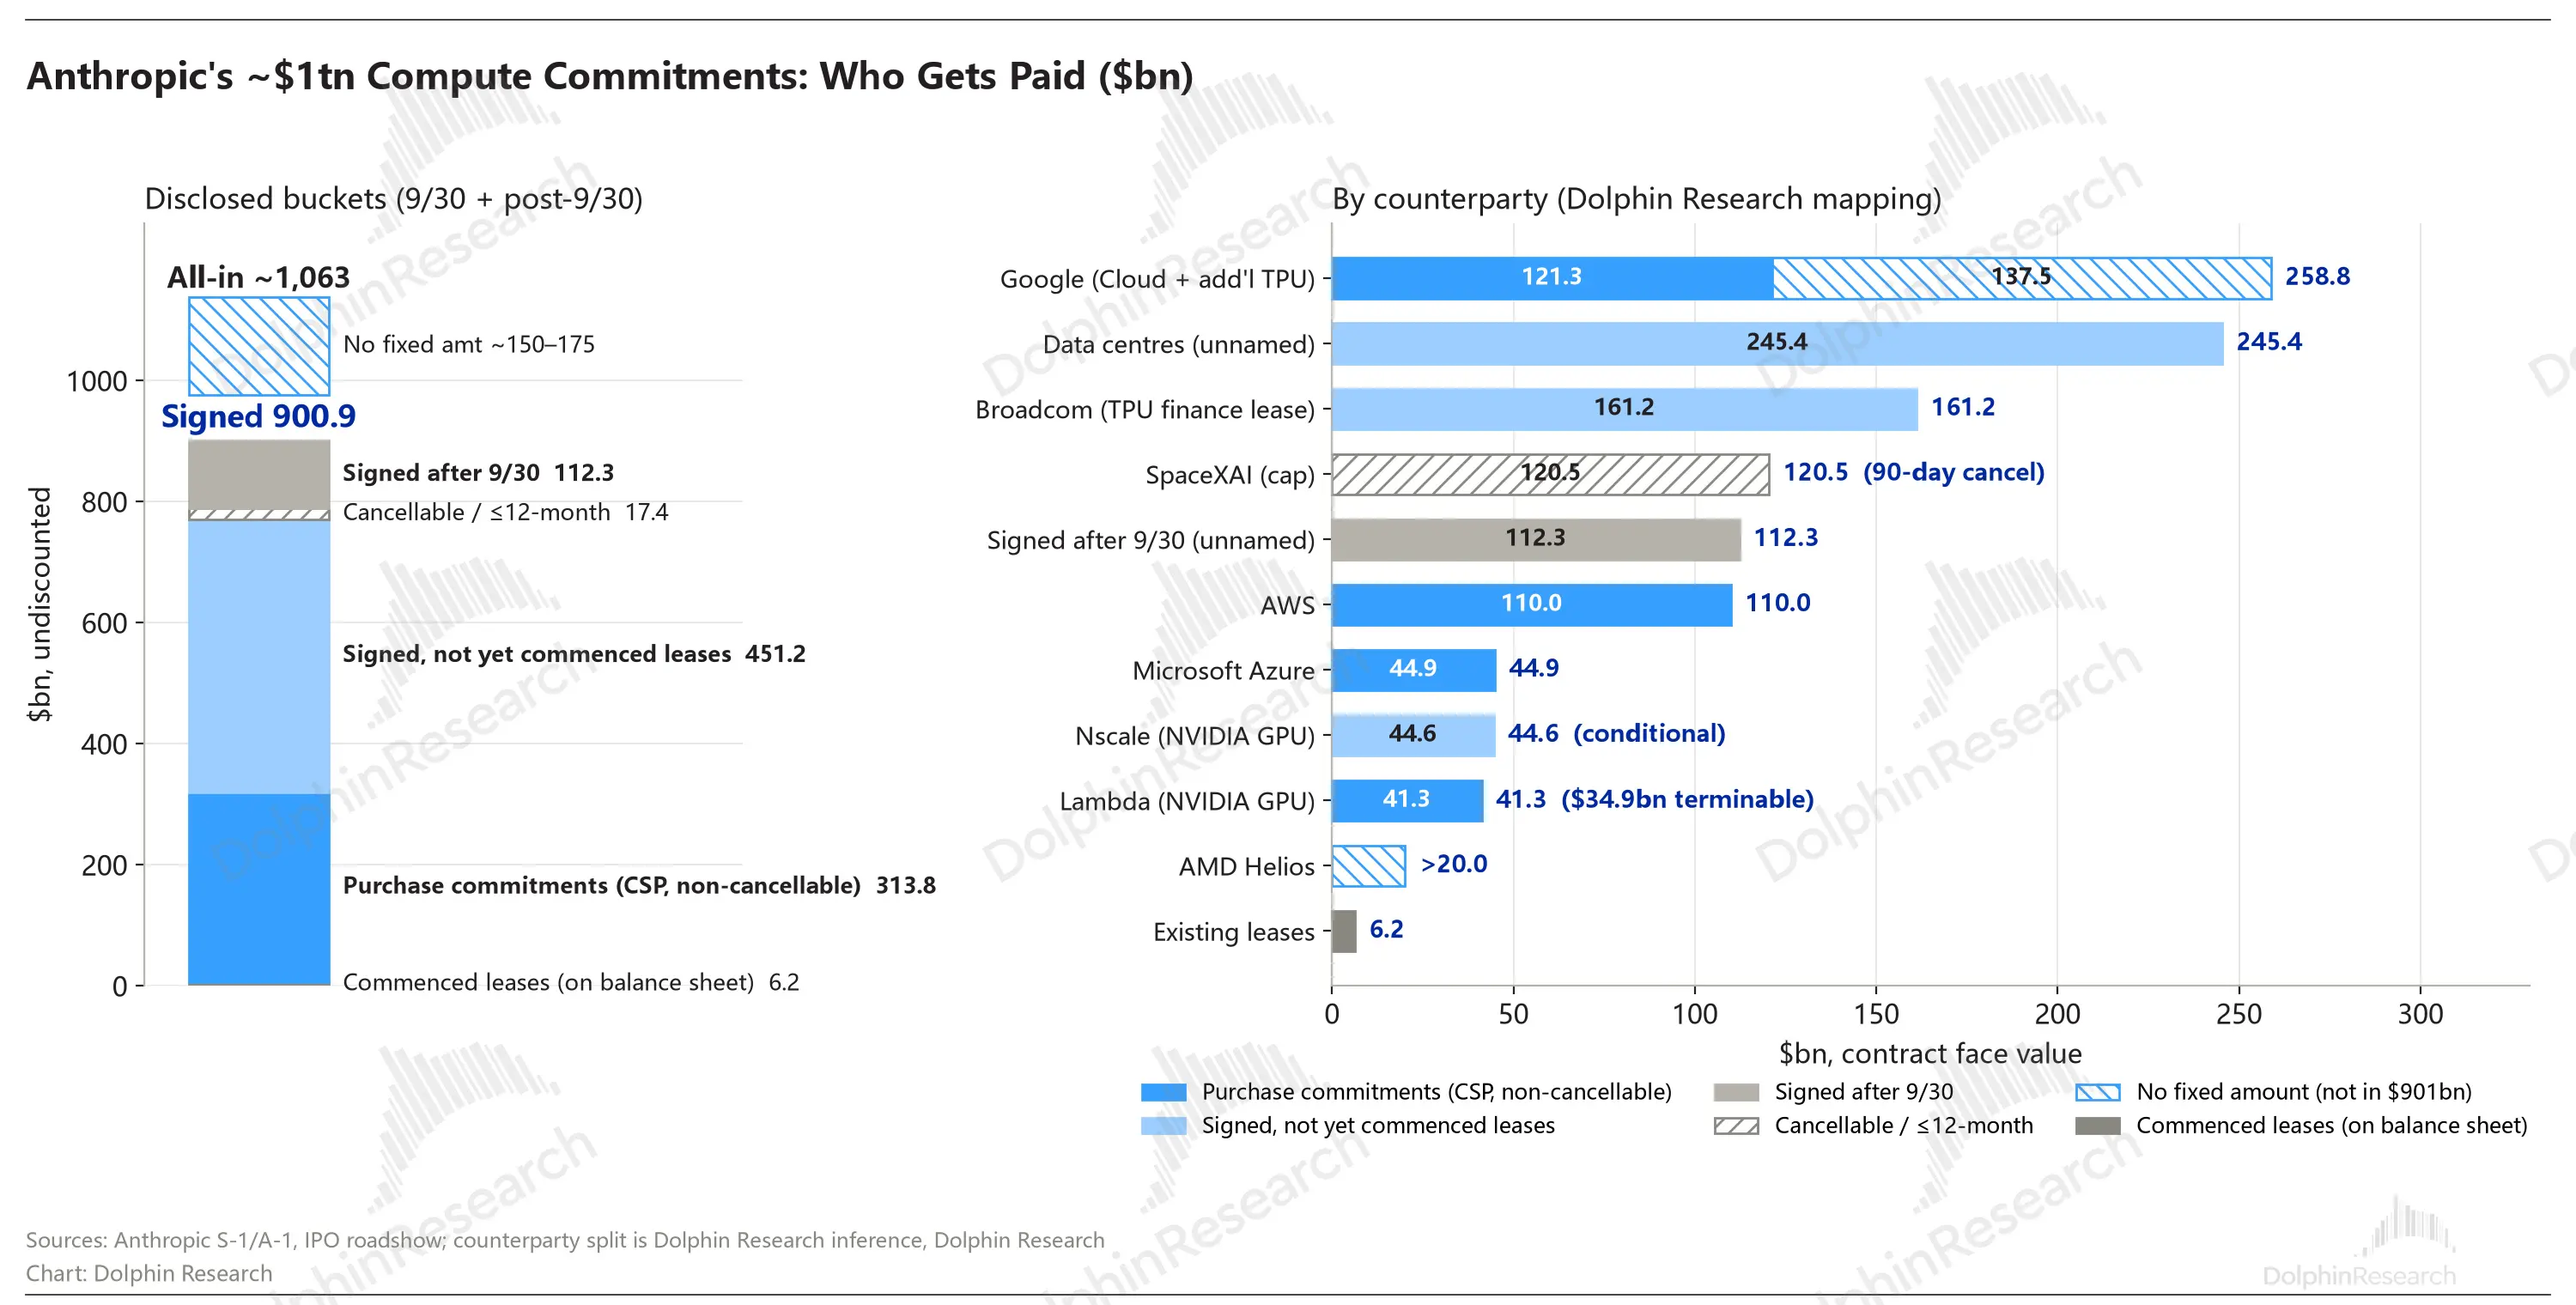
On the other hand, over the past ten months it signed compute contracts totaling nearly $1 tn. That equals 22x its annualized revenue.