D
 +7
ABNB: Blowout beat, no weak links — but is growth pulled forward?
Results beat across the board, but book-now-pay-later flattered the print
+7
Results beat across the board, but book-now-pay-later flattered the print
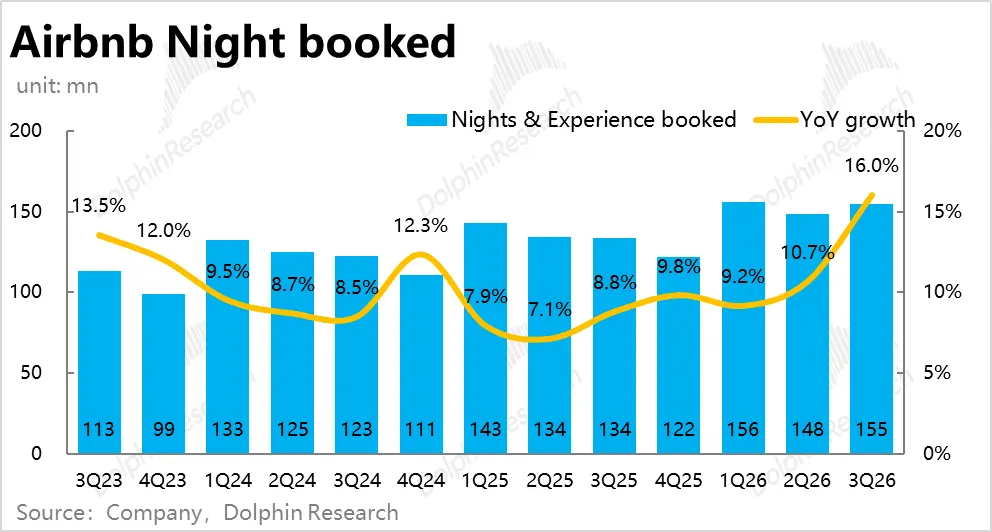
+7Global alt-stay leader $Airbnb(ABNB.US) released FY26 Q2 results early on Aug 7. Helped by the World Cup, the print was solid, with growth in gross booking value and nights beating estimates.
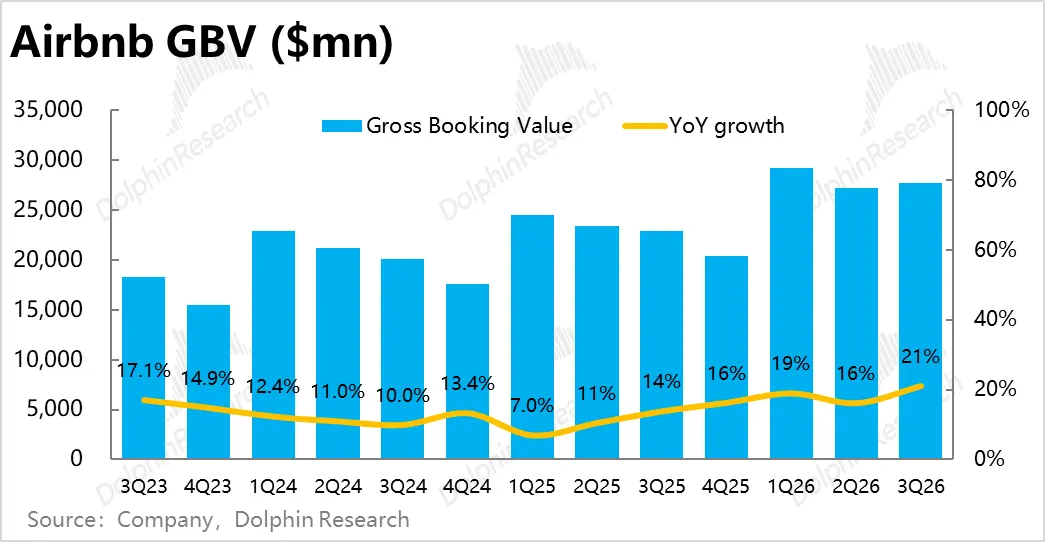
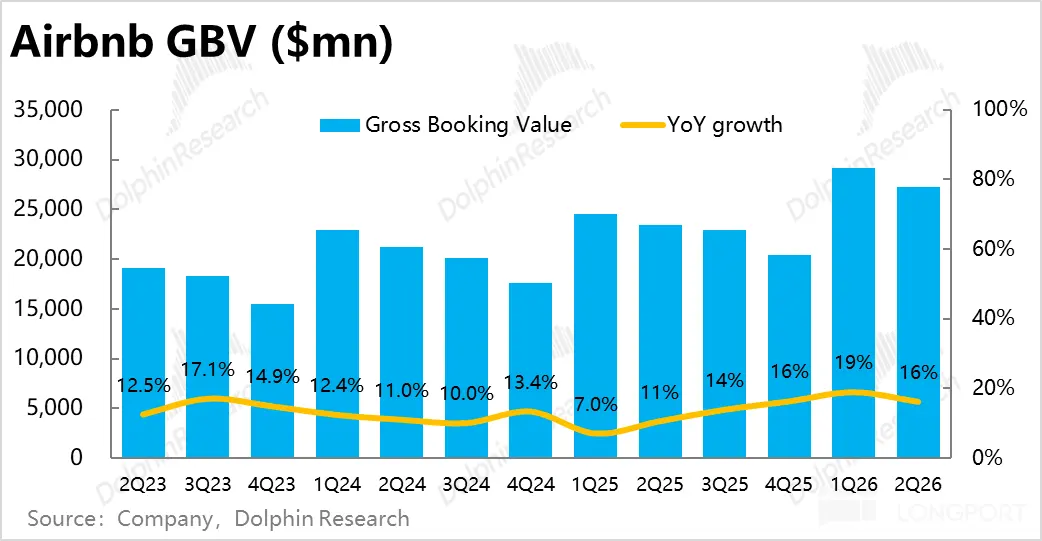
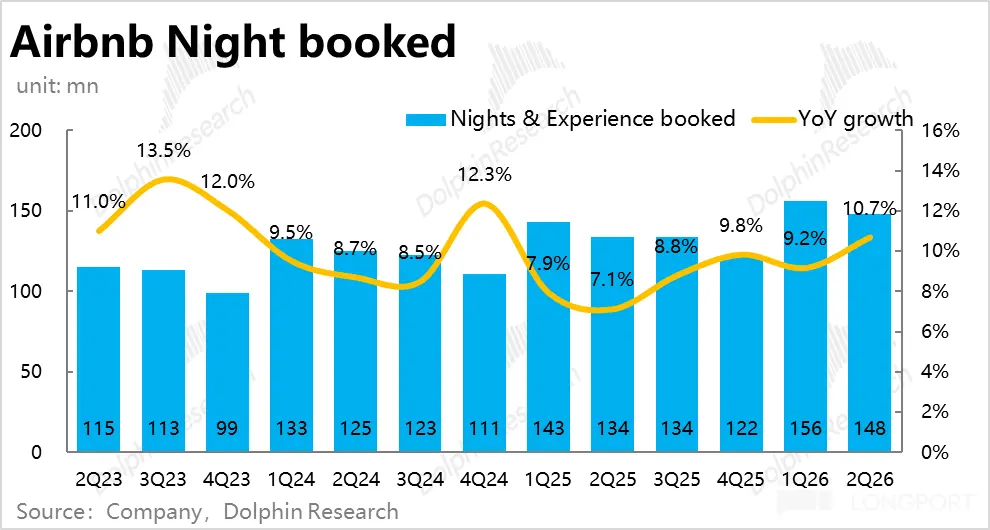
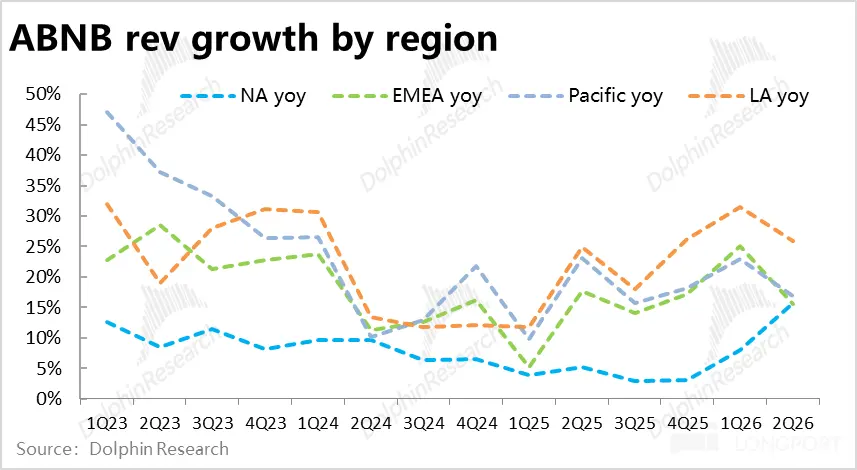
Management also issued upbeat guidance for next quarter, pointing to sustained strength in travel and lodging in the mid term. 1) Nights growth accelerated, underscoring the recovery in travel demand.Focusing on the key operating metric, gross booking value (GBV) grew 16% in nominal terms this quarter, which appears to be a deceleration. Ex-FX growth was 15%...
 +7
Q2 revenue rose 17% YoY to $3.6bn, topping the high end of guidance. Full-year revenue growth guidance was raised from low-to-mid-teens to at least mid-teens, and the Adj. EBITDA margin outlook from 35% to at least 35.5%.
However, Q3 margin will edge down YoY given a faster investment cadence. For the year, the take rate is guided to be only flat vs. 2025. Management will prioritize an AI-native overhaul and the hotels biz in the next phase.Below is the FY26Q1 Airbnb earnings call Trans compiled by Dolphin Research. For our earnings review, see 'Airbnb: Near-term results look fine, but facing a midlife crisis?'.
I. Core highlights recap. 1) Shareholder returns and capital actions: repurchased $1.1bn of common stock in Q1. Secured investment-grade ratings from major agencies, then issued $2.5bn of senior unsecured notes for debt repayment and general corporate purposes...Alt. stays leader Airbnb$Airbnb(ABNB.US) released FY26 Q1 results this morning (May 8). Overall, the quarter was solid, with most metrics slightly beating estimates. Growth metrics accelerated on FX tailwinds.
Guidance for next quarter also came in above expectations. Specifically, growth appears to be accelerating but is essentially stable.On core KPIs, GBV rose 19% YoY, with a clear QoQ pickup. The increase was largely FX-driven. Ex-FX, underlying growth was 13%...The following is Dolphin Research's Trans of $Airbnb(ABNB.US) FY25 Q4 earnings call. For our earnings take, see 'Airbnb: Solid print, but now a cyclical?'.
Key highlights: 1) Shareholder returns: $3.8B of buybacks for the year, using ~80% of FY FCF; total shares outstanding down 9% since 2022. 2) 2026 Q1 guide: a) revenue of $2.59B–$2.63B (+14%–16% YoY), incl. ~3% FX tailwind...Alt. lodging leader Airbnb$Airbnb(ABNB.US) reported Q3 FY2025 results this morning, with overall performance beating expectations. Contrary to prior guidance flagging a potential slowdown, bookings and revenue growth re-accelerated across the board, hitting a 25-year high.
The main blemish was sharp opex expansion, with margins clearly compressing. Revenue rose, but profit lagged.1) Both nights and pricing increased, pointing to resilient travel demand. Versus the earlier cautious guide, actual booking momentum proved far sturdier. Gross booking value (GBV) grew 16% YoY...The following are the Minutes of the Q3 2025 earnings call organized by Dolphin Research. For an interpretation of the financial report, please refer to "Airbnb: Is it truly climbing out of the trough, or just a 'flash in the pan'?" 1. Review of Core Financial Information This quarter, the total booking amount increased by 14% year-on-year to $22.9 billion, mainly driven by the increase in booking volume and average daily rates. The number of booked nights grew by 9% year-on-year, accelerating by 2 percentage points quarter-on-quarter, with the U.S. market performing particularly strongly. In the third quarter, the growth of booked nights in major regions remained stable or accelerated quarter-on-quarter: Latin America grew by approximately 20%...
Alternative accommodation leader Airbnb$Airbnb(ABNB.US), on November 7th, after the U.S. stock market closed, announced its financial results for the third quarter of fiscal year 2025. Overall, although the monetization rate fell short of expectations, resulting in mixed financial metrics and continued issues with profit margin contraction, the more important operational indicators showed accelerated growth quarter-on-quarter. The guidance for GBV growth in the next quarter also exceeded expectations, suggesting that business growth may finally be rebounding. Specifically: 1. Business growth rebounding: Gross Booking Value (GBV) increased by 14% year-on-year...
The following are the Minutes of Airbnb's Q2 2025 earnings call. For an interpretation of the financial report, please refer to "Airbnb: The Financial Report Seems Good, But Weakening Operational Data is Key." 1. Review of Core Financial Information 1. Review of Performance Indicators • The number of booked nights and seats reached 134 million, a year-on-year increase of 7%. Notably, the growth rates in May and June both exceeded those of the first quarter. It is worth mentioning that "booked nights and seats" is a new indicator, which includes the total number of booked nights for accommodations as well as the total number of booked seats for services and experiences...