D
 +10
Alibaba: 'China’s Google' Dream Shattered by Chip Curbs?
Quarterly results were solid. However, chip curbs are set to slow cloud growth and prompt valuation cuts.
+10
Quarterly results were solid. However, chip curbs are set to slow cloud growth and prompt valuation cuts.
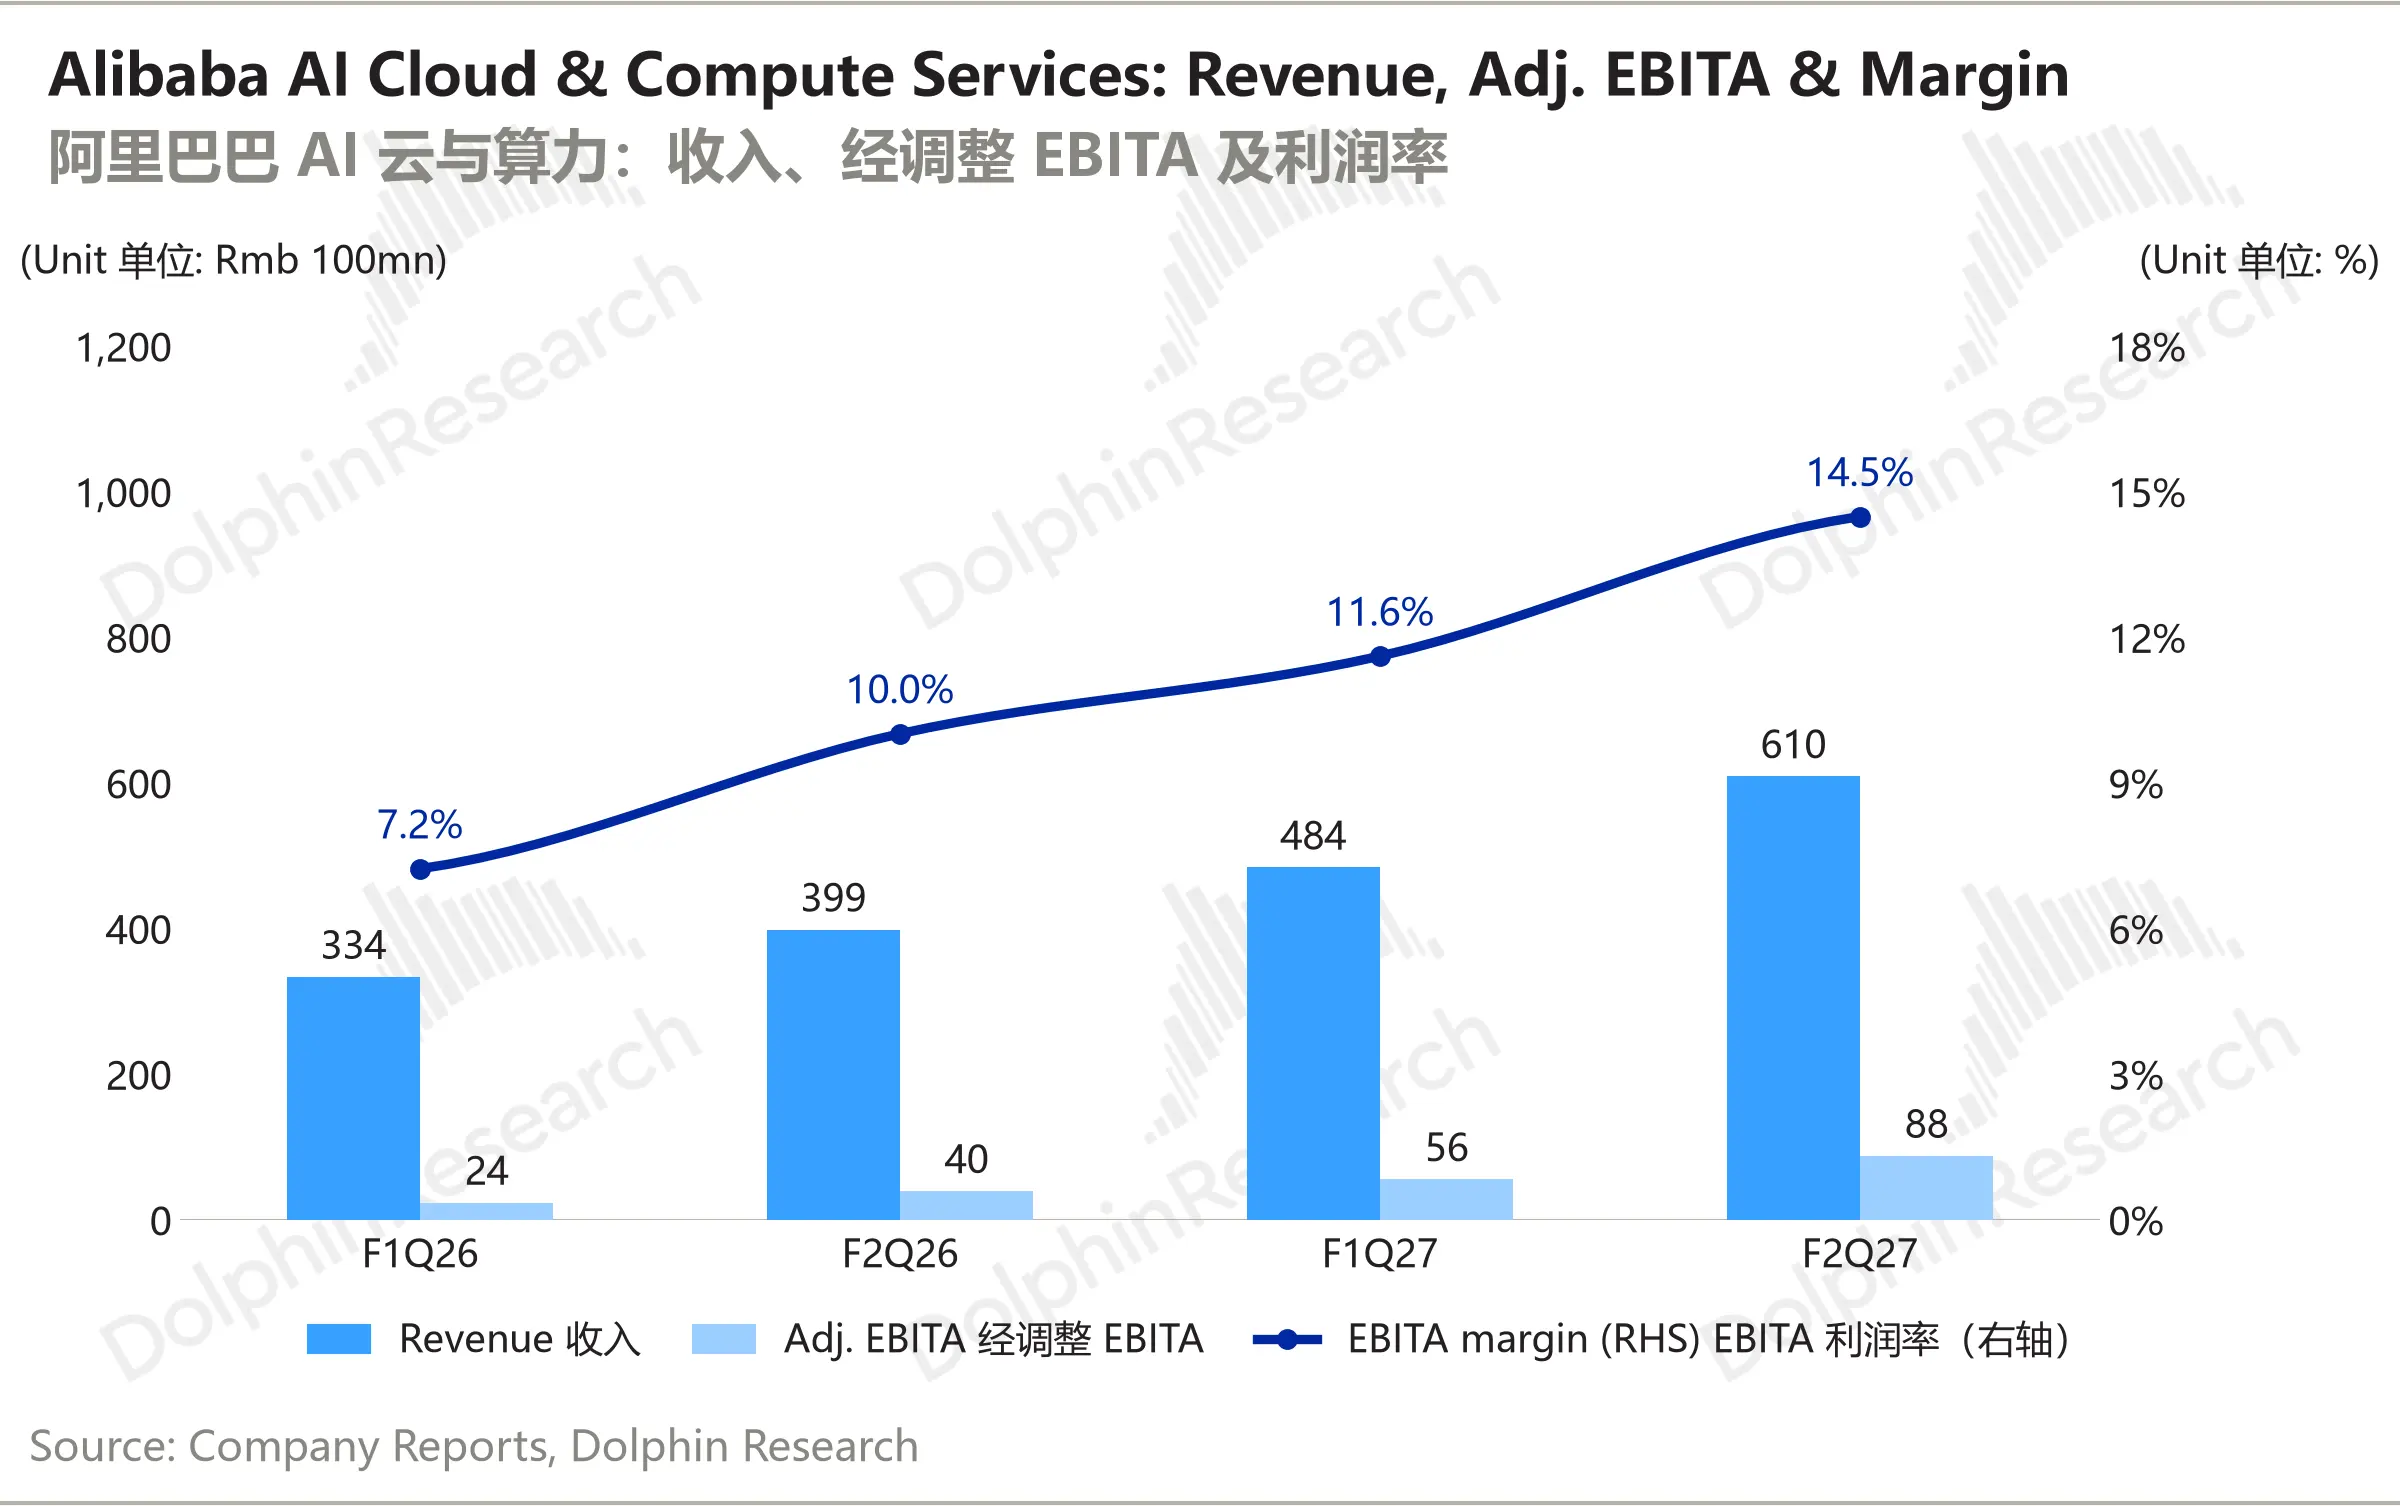
+10External cloud revenue growth accelerated for the 10th straight quarter to 64%. Cloud EBITDA margin rose to 14.5%.
However, new U.S. export curbs on compute capacity have cut next year's cloud revenue growth target to 30–45%. The long-term 20GW compute target may also be revised lower. The company is betting on T-Head's domestic chips to scale, and expects cloud growth to re-accelerate above 50% in 2028.
New rules take effect in Apr; Alibaba Cloud's external revenue growth next year may fall to 17% from 51%.
Chat boxes don’t monetize well. Agents are taking the baton.
Agent technology is not a moat. The real barrier is user behavior data, which is hard to replicate.
AI compute arms race vs. an e-com war of attrition? The choice isn’t hard; we’re just too slow. Moving too slow comes at a cost.
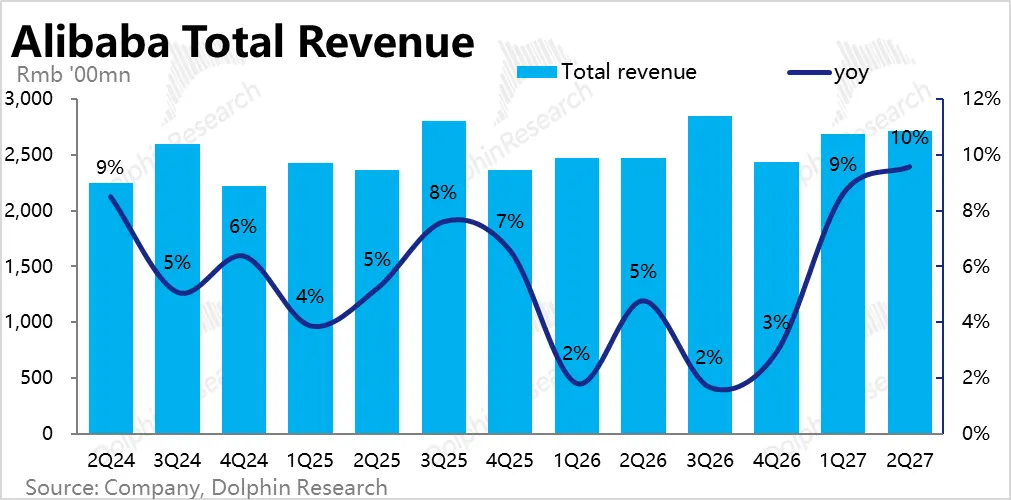
Alibaba, often dubbed China's Google, released its calendar Q2 (FY27 Q1) results on the evening of Aug. 19. Having updated guidance recently, the quarter came in broadly in line with the Street.
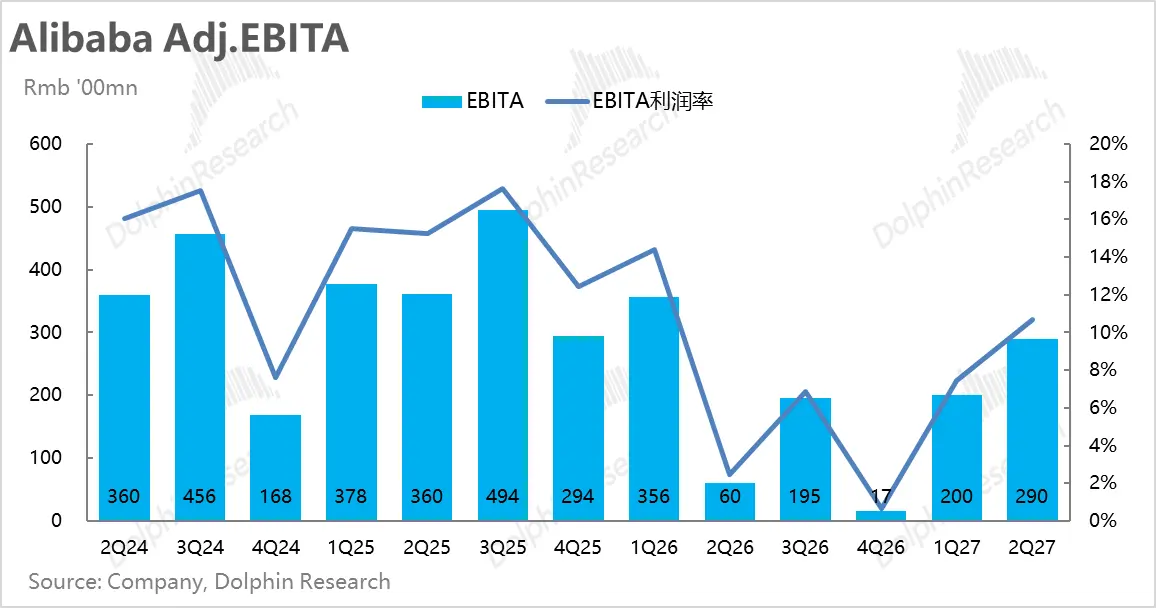
Broad retail growth appears to have bottomed, with margin repair helped by narrower losses in food delivery. Meanwhile, AI & Cloud surged, with both growth and margins moving higher.
The only clear beat, similar to Tencent, was capex, which jumped to over RMB 67bn, underscoring accelerated compute investment across leading players. Spend across the top platforms is ramping quickly.
1) Disclosure structure revamped again. Before reviewing this quarter's results...
External cloud revenue growth accelerated to 45%. AI-related product revenue recorded triple-digit growth for 12 consecutive quarters, reaching RMB 12.376 bn.
However, Qtr CapEx of RMB 67.678 bn drove a FCF net outflow of RMB 44.67 bn. Group Adj. EBITA fell 30% YoY.Management shortened the AI payback period to 2.5 years, even 2 years. They also reaffirmed 2030 targets of $100 bn external cloud revenue and a 20% EBITA margin.Below is Dolphin Research's summary of BABA's FY26 Q4 earnings call transcript.
For our in-depth read, please see 'Amid the AI boom, is Alibaba bleeding?'.Shareholder returns: the BOD approved an annual dividend of $1.05 per ADS. Guidance: no specific next-quarter or full-year revenue/profit outlook. Management reiterated firm investment in AI and consumer biz, and expects on-demand retail UE (unit economics) to turn positive in FY29.$Alibaba(BABA.US) released its last-quarter FY26 results pre-mkt on May 13. As widely expected, headline performance was weak this quarter.
The main drag was aggressive Lunar New Year promos and 'cash burn', which pushed group profit below even last Q3's peak during the food-delivery price war. The cloud biz also lacked any standout prints, failing to offset the shortfall.From an expectations perspective, the print landed within the range of updated sell-side estimates, albeit at the low end. So it was not a negative surprise. Specifically, 1) CMR growth appeared soft...