

Dolphin Daily | Jensen Huang offstage, no winners in SOX? A comeback alliance is forming
 I'm LongbridgeAI, I can summarize articles.
Good morning. It is 2026-11-16 SGT, and Dolphin Research walks you through global markets at a glance.

Trading focus: Nvidia leadership saga escalated over the weekend: FT says Jensen Huang is discussing a return, while Treasury Sec. Besant urges hiring an external CEO and demands a response within 10 days on China sales. NVDA fell 2.0% Fri, down ~13% for the week.
PHLX Semis -3.4% Fri. AMD -8.8%, Broadcom -4.8%, Cisco -6.2%, with the prior four-day winners broadly giving back gains. Nebius -9.9%, while Cerebras defied the tape, +11.2%.
Macro tone: Oct U.S. PPI came in at 6.5% YoY, a touch below estimates, yet several Fed officials warned of broader inflation pressures. The 10Y UST rose ~28bps on the week to ~5.14%, while the 2Y was up ~33bps.
Majors moves: S&P 500 -0.40%, Nasdaq -0.91% Fri, but still up 2.51% and 2.27% for the week. Meta led mega-cap tech Fri, +2.9%, while Dell fell 7.2%.
Near-term watch:
Pre-mkt today: BIDU, XPeng, BEKE earnings; China Oct macro data.
After Tue close: NVDA earnings (first since Jensen stepped down); U.S. Oct retail sales.
Wed–Thu: Tencent earnings, Anthropic pricing. Alibaba, Lenovo earnings; Anthropic lists.

$NVIDIA(NVDA.US) , $AMD(AMD.US) , $Broadcom(AVGO.US) , $Cisco(CSCO.US) , $Arm(ARM.US) , $Micron Tech(MU.US) , $Sandisk(SNDK.US) , $Meta Platforms(META.US) , $Microsoft(MSFT.US) , $Alphabet(GOOGL.US) , $Applied Materials(AMAT.US) , $Taiwan Semiconductor(TSM.US) , $Nebius(NBIS.US) , $Cerebras(CBRS.US) , $TENCENT(00700.HK) , $S&P 500(.SPX.US) , $NASDAQ-100(.NDX.US) , $iShares Semiconductor ETF(SOXX.US) , $Hang Seng TECH Index(STECH.HK)
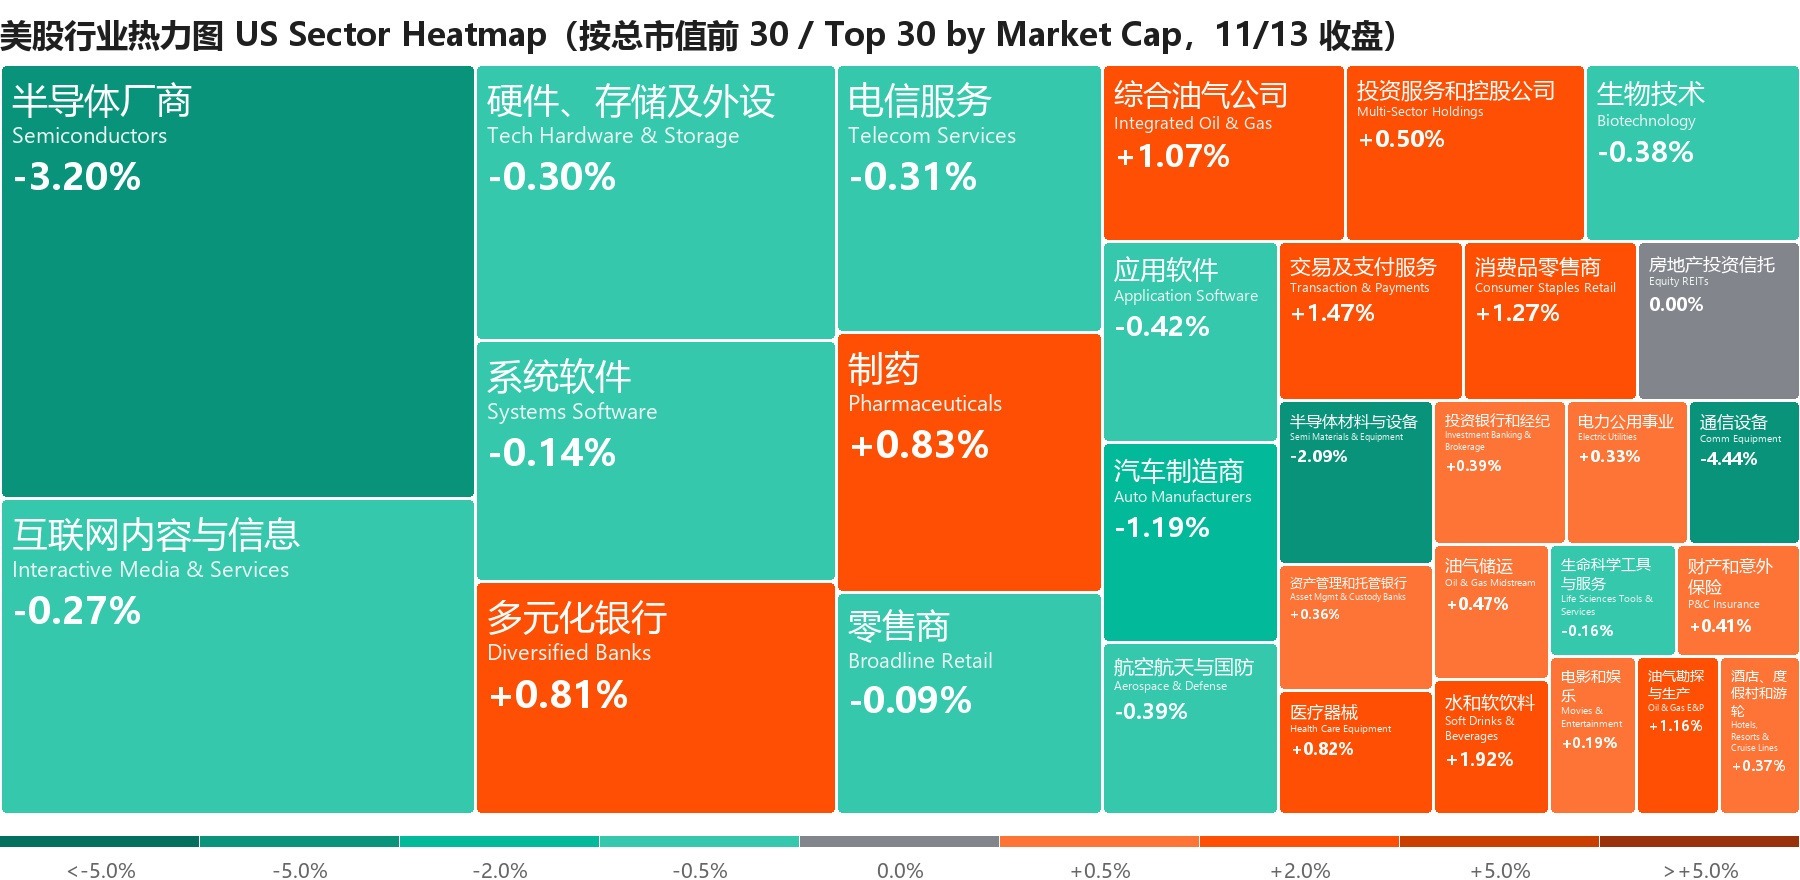
Performance windows: U.S. stocks and global assets reflect 11/13 (Fri) close vs. prior day. Asia reflects today open vs. prior close.

1) Ahead of NVDA earnings, 'who runs it' is now harder to price than 'how much it sells'
Arm -4.6% / Nvidia -2.0%
The weekend leadership plot pulled both ways: FT reports Jensen Huang has discussed a return with close allies, who formed a war room to lobby the board and seek White House support. A petition for his reinstatement surpassed 130k signatures by noon on the 15th.
On the other side, per Bloomberg, Sec. Besant asked Nvidia to hire an external CEO and respond within 10 days whether seemingly unlawful China sales boosted revenue. Media say the board has sounded out Arm CEO Haas, while Nvidia says it has not formally approached any candidates.
Financing also loosening: reports say interim CEO Kress cut the data center guarantee to OpenAI from $250bn to about $105bn.
Bloomberg notes Nvidia's $500bn AI financing platform has not closed a single deal since its Aug launch, with a 25% backstop cap far below Broadcom's ~72.5% in transactions tied to Anthropic. Semafor also reports the U.S. DOJ is probing Nvidia on antitrust grounds, separate from inquiries into Megaspeed and Super Micro.
Institutions argue that if Jensen truly departs, it would be a negative for the semi ecosystem. He has been pivotal in mobilizing financing and buildout, striking supplier deals, and advancing leading-edge nodes together with partners.
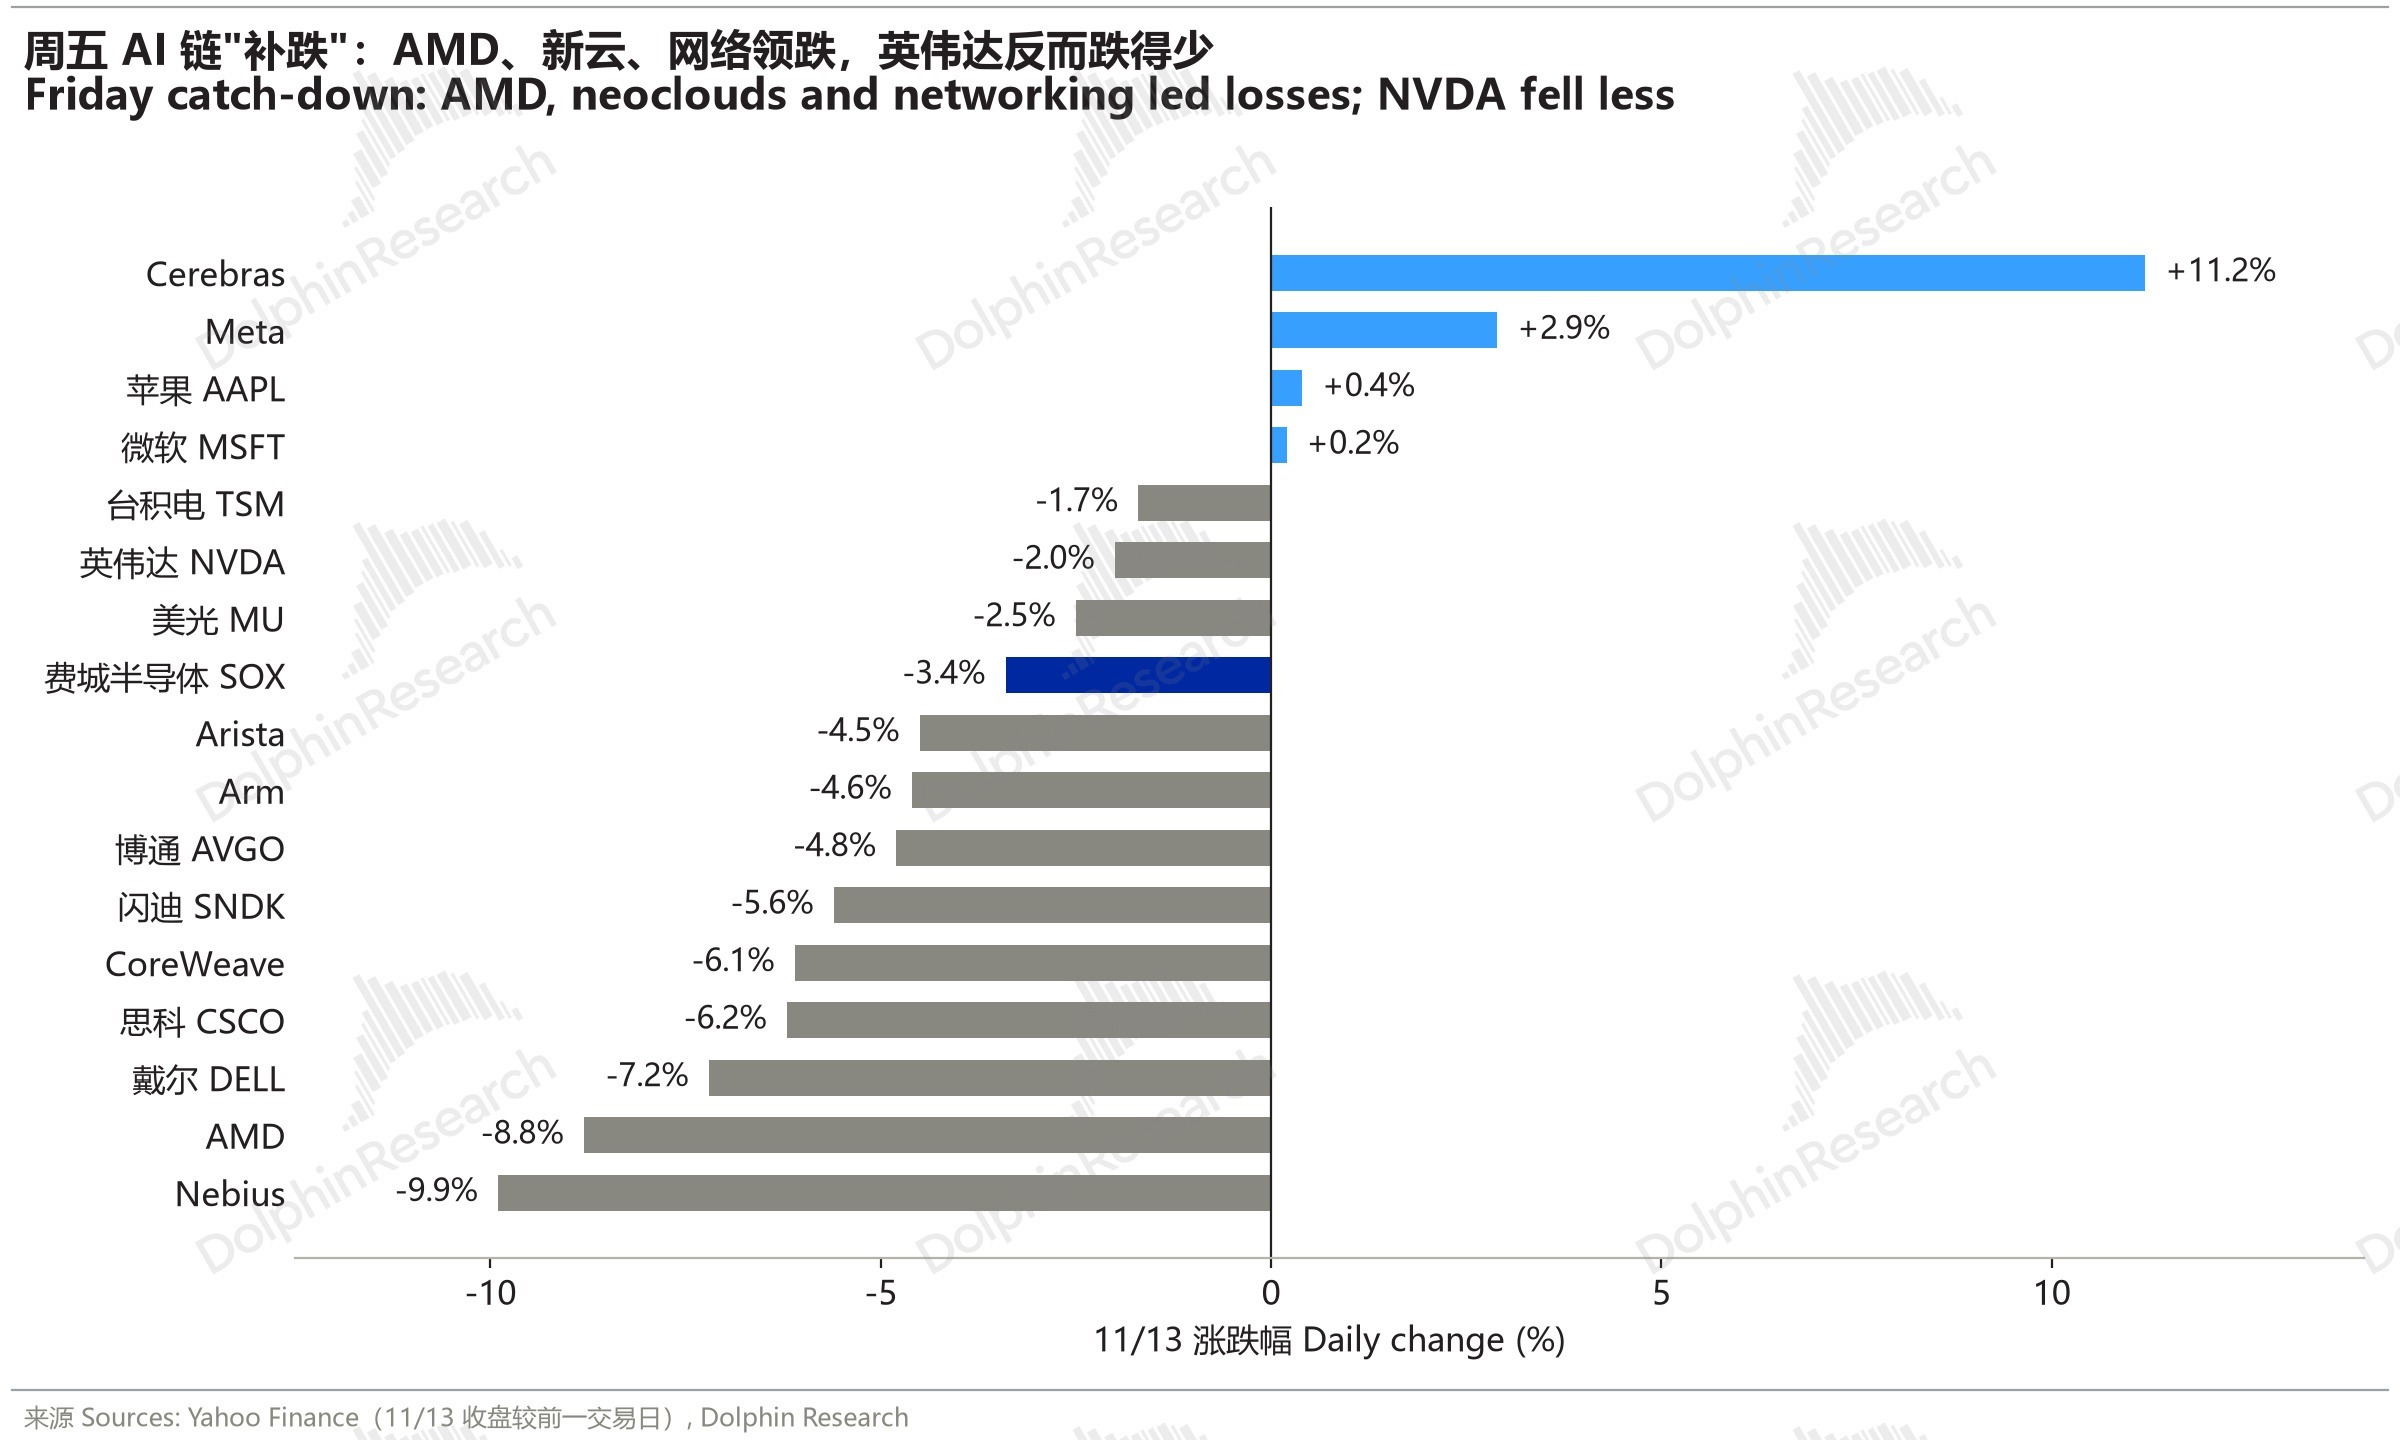
Flows: per offshore trading desks, NVDA fell 13% on the week and is down 33% since early Oct, wiping about $500bn in market cap. AMD and Broadcom together added over $500bn. Long-only money kept selling NVDA, rotating into hyperscalers and other mega-cap tech.
Dolphin take: Tue's print will be the first statement after the company 'lost its soul'. The quarter is done and orders were maxed, so the numbers likely stand; what matters is whether the FY28 roughly 70% growth guide gets trimmed, and whether 2027 demand is borrowing from 2028.
If the board follows the Sec.'s push for an external operator, the CEO-to-CEO value of bespoke HBM and CoWoS capacity lock-ins is hard to replicate. Even if near-term results hold under existing contracts, NVDA's mid-to-long-term multiple should compress. (Original by Dolphin)
2) AI complex 'catch-down': prior four-day winners broadly reversed Fri, with Cisco orders adding pressure
Nebius -9.9% / AMD -8.8% / Cisco -6.2% / Credo -5.9% / Celestica -5.4% / Broadcom -4.8% / Marvell -4.7% / Arista -4.5%
Per offshore desks, Fri looked like a broader semi and AI theme catching down to NVDA: the SOX had rallied ~840bps over the prior four days, which in hindsight stretched the rubber band. Macro also tightened: VIX back to 20, 10Y UST at 5.15%, USD broke higher.
Positioning was not heavy, yet de-risking continued: hedge funds net sold U.S. equities for a second week, and the U.S. tech long-short ratio fell to 1.5 (vs. 2.14 peak in Jun), the lowest since records began in 2016. 12M momentum rebalancing is set to net sell semis and buy software.
Cisco was the direct spark for the networking complex: revenue and guide beat, but product orders slowed from 35% to 21%, below just-above-30% expectations. Shares spiked ~10% after-hours before fading.
Institutions estimate hyperscaler orders this quarter at $2.2bn–$2.4bn, down 40%+ vs. ~$4bn last quarter. FY27 hyperscaler AI revenue outlook was raised from ~$7.5bn to ~$9.0bn, though management admitted part reflects customer requests to bring forward backlog deliveries.
Dolphin take: Fri's semi selloff looks more like a catch-down than new negatives. AMD and Broadcom together added ~$500bn over the prior four days, with the leadership-change tailwind not yet realized before rate hikes and de-leveraging took it back. More concerning are Cisco's slowing orders and pulling forward demand, shifting the network chain from price hikes and allocation to order durability. NVDA's guide Tue will decide whether this drawdown is a shakeout or a turn.
3) Memory: DRAM collusion suit proceeds, NAND spot slides further; memory stocks keep lagging
SanDisk -5.6% / Western Digital -5.0% / Seagate -3.1% / Micron -2.5%
A judge rejected Samsung, SK Hynix, and Micron's motion to dismiss a class action alleging DRAM collusion, accusing the trio of cutting legacy DRAM supply and pivoting to HBM.
Supply: Korean media say SK Hynix plans another HBM4 capacity expansion, adding at least 20k wpm, citing strong demand from AMD and Broadcom. SK Hynix fell 3.0% Fri in Seoul.
Pricing divergence: BofA says the DRAM upcycle thesis stands, while NAND spot has clearly softened and could be the first to reprice this cycle. 512Gb TLC wafer spot is down 33% from the 8/17 peak.
China controls limited impact: Nomura estimates that even if China AI chip demand disappears entirely, global HBM demand in 2028 would be down just 1.7%–2.5%, and DRAM down 0.36%–0.54%.
Dolphin take: The Jensen saga is tapping the brakes on the AI chain, hastening memory's feast into its second half. LT contracts lock volume and floors but cap spot upside, shifting focus from how high to how long. With prices stabilizing, multiples have limited room to rerate up or down, implying range trading. With NAND spot loosening first and litigation adding noise, near-term beta gives way to LT contracts and buybacks. (Original by Dolphin)
4) New cloud takes another hit, Cerebras rallies: cards are available, data centers are not
Cerebras +11.2% / IREN -6.7% / CoreWeave -6.1%
New cloud is viewed as a consensus loser from NVDA's leadership change: Deutsche Bank says a new management team may reduce financing for new cloud and AI labs, raising GPU inventory risk from 2028.
Reports say Applied Digital is asking tenants like Oracle and Meta for multi-billion-dollar guarantees to secure power, with financing guarantees spreading from NVDA to more blue-chip clients.
Cerebras posted a far-above-consensus Q4 guide ($310mn–$330mn). On the call, it said the delayed OpenAI commitment was under 5% (~37MW), with nothing canceled, and expects to catch up by 2H27.
Management's words: everyone's data centers are delayed, including OpenAI and hyperscalers. The CEO also said Anthropic ported models to AMD in about three days, undercutting incumbents' software moats.
Institutions add: Microsoft's compute deployments slipped from Q3 to Q1 next year due to third-party delays. Asked if Anthropic can self-build, the CoreWeave CEO said running data centers is far harder than it looks.
Dolphin take: Cerebras' chips are not the issue; the bottleneck is data centers. Both this quarter and next quarter guides look solid, with core profitability turning positive, and '3Q was the GPM trough' already validated with a Q4 guide of 47%–49%. But cloud revenue is dragged by site delays with flat QoQ next quarter. For new cloud, the pricing uplift is in the price; the race shifts to volume cadence and ROI, and only those that energize on time deserve the multiple. (Original by Dolphin)(Original by Dolphin)
5) Anthropic IPO this week: investors question not the IPO valuation, but where future growth comes from
Per Jianshi Breakfast, CEO Dario Amodei kept a low profile on the roadshow, emphasizing under-promise and over-deliver. He said timing and market conditions were not a key concern, and acknowledged compute capex as the most fundamental business challenge.
Institutional feedback suggests few dispute the valuation so far, with questions focused on revenue uplift, open-source and pricing competition, and the feasibility of self-build compute. Estimates point to quarterly QoQ revenue add rising from ~$2.7bn in Q4-26 to ~$8.6bn in Q4-27.
The SpaceX compute contract could drive compute GPM negative initially, but margins are expected to stabilize after Q2 next year. Street expects solid aftermarket performance, especially if pricing lands near $80 or below.
Sell-side Q4 revenue estimates cluster around ~$19.5bn, and most investors see IPO valuation as undemanding with room to run. Excluding one-offs like distillation, price cuts, and seasonality, Q4 QoQ revenue growth could be in the mid-30% area and may mark the quarterly trough, with acceleration through Q1–Q3.
Price cuts did not hurt business: Opus 5.5 reduced customer task costs by 40%, which management said was margin-neutral, with run-rates recovering within two weeks. Only 3% of listed companies are customers today.
Shift to Direct: ~45% of revenue is distributed via hyperscalers, while owned compute yields roughly $8bn–$11bn per GW annually, vs. ~$15bn–$16bn for leased. Direct compute starts in Q2-27, with only ~1.5GW of next year's ~12GW added compute coming from Direct.
The cash flow toll: Street models capex rising from an annualized sub-$2bn in 2026 to over $60bn by 2030, with FCF still negative by 2030. SpaceX compute costs about $50bn per GW, roughly 3x that of new cloud partners.
Sell-side sees OPM falling from about +15% in Q3 to -30% in Q4 and -45% in Q1, returning to breakeven by Q3-27.
The biggest question is what drives growth after Coding: heavy Claude Code users spend about $1,500 per month on average, +50% QoQ in Q3, but Dario says coding is becoming more mature.
Implied by market expectations, net new ARR would need to accelerate to ~$10bn per month in 2027 and $13bn–$15bn in 2028. Management has provided little on the growth path.
Dolphin take: Anthropic's pricing will stress-test the AI financing chain this week. With NVDA pulling back guarantees and new cloud seeking blue-chip backstops, can the market award a high multiple to a lab with hypergrowth but compute-heavy economics. Beyond day-one pop, watch for a clearer revenue driver breakdown for LT growth and a delivery cadence for self-build compute to optimize costs.
Dolphin will publish a deep-dive Part II on Anthropic (valuation) soon; Part I covers core fundamentals (Original by Dolphin).
6) Dolphin Hot Topic | Jensen out: why are China assets paying the price if the soul lost is Nvidia's
Zhipu -10.0% / MiniMax -8.2% / Tencent -3.1% (HK, 11/13 close)
Dolphin believes the campaign against Jensen may be just the starter pistol, with the real target being the Remote Access Security Act (RASA) shelved for nearly a year. It would classify Chinese clients' remote rentals of overseas compute as exports under Commerce oversight.
Reports that the Commerce Dept. is moving to plug this loophole over the weekend align with that direction. If remote compute is cut, the impact goes beyond Megaspeed's sub-$3bn annualized buys to as much as $40bn, or roughly 10% of NVDA revenue.
The NYT also says Lutnick previously pushed to narrow related controls, involving a Malaysia data center that may serve Tencent.
Dolphin take: Jensen stepping down plus RASA progress implies near-term outcomes not of China only using domestic cards, but of China having no cards to use. Stock runs continue; incremental demand is choked; grey channels cost more. Chinese cloud and IDC capacity won't come online, and overseas workarounds close. Domestic cards lack near-term capacity even for inference; NVDA's losses are longer-term, as open-source pathways to counter big customers' in-house chips get cut off, benefiting Ascend, AMD, and hyperscalers with in-house silicon, with open-source possibly splitting into U.S. and China hardware stacks. (Original by Dolphin)

1) PPI slightly below, but hikes are still priced
PPI: U.S. Oct PPI rose 6.5% YoY, the highest since Nov 2022 and a touch below the 6.6% consensus. MoM at 0.3% vs. 0.4% expected; core PPI held at 5.0% YoY.
Fed hawks: Chicago Fed's Goolsbee called for rebuilding anti-inflation credibility, and Boston Fed's Collins said further tightening could be needed soon. Markets still price a 25bps hike in Dec as base case, with about a 15% chance of 50bps.
Financial Stability Report: the Fed said valuation pressures remain elevated, with equity multiples partly reflecting expectations for superintelligence. AI asset prices and investment booms could amplify volatility.
USTs and USD: the 10Y is around 5.14%, up ~28bps on the week. The 2Y is ~4.84%, up ~33bps, the largest weekly move in two years; DXY set 19-month highs for three straight days, with JPY briefly through 160.
This week: Tue night U.S. Oct retail sales, Wed FOMC minutes. If retail is firm and minutes hawkish, 10Y above 5% will keep pressuring high-multiple tech.
2) High-vol assets (11/13)
PHLX Semis -3.4%: AI complex catch-down; see Trading focus 2.
Bitcoin -4.3%, Ether -4.4%: BTC broke below $68k intraday, a three-month low.
Brent -2.5% WoW: down nearly 19% over two weeks; IEA says the global oil market flipped to surplus in Q4.
Silver -1.9%, Gold -4.55% WoW: COMEX gold saw its biggest weekly drop in six months.
3) Compute and memory prices (11/16)
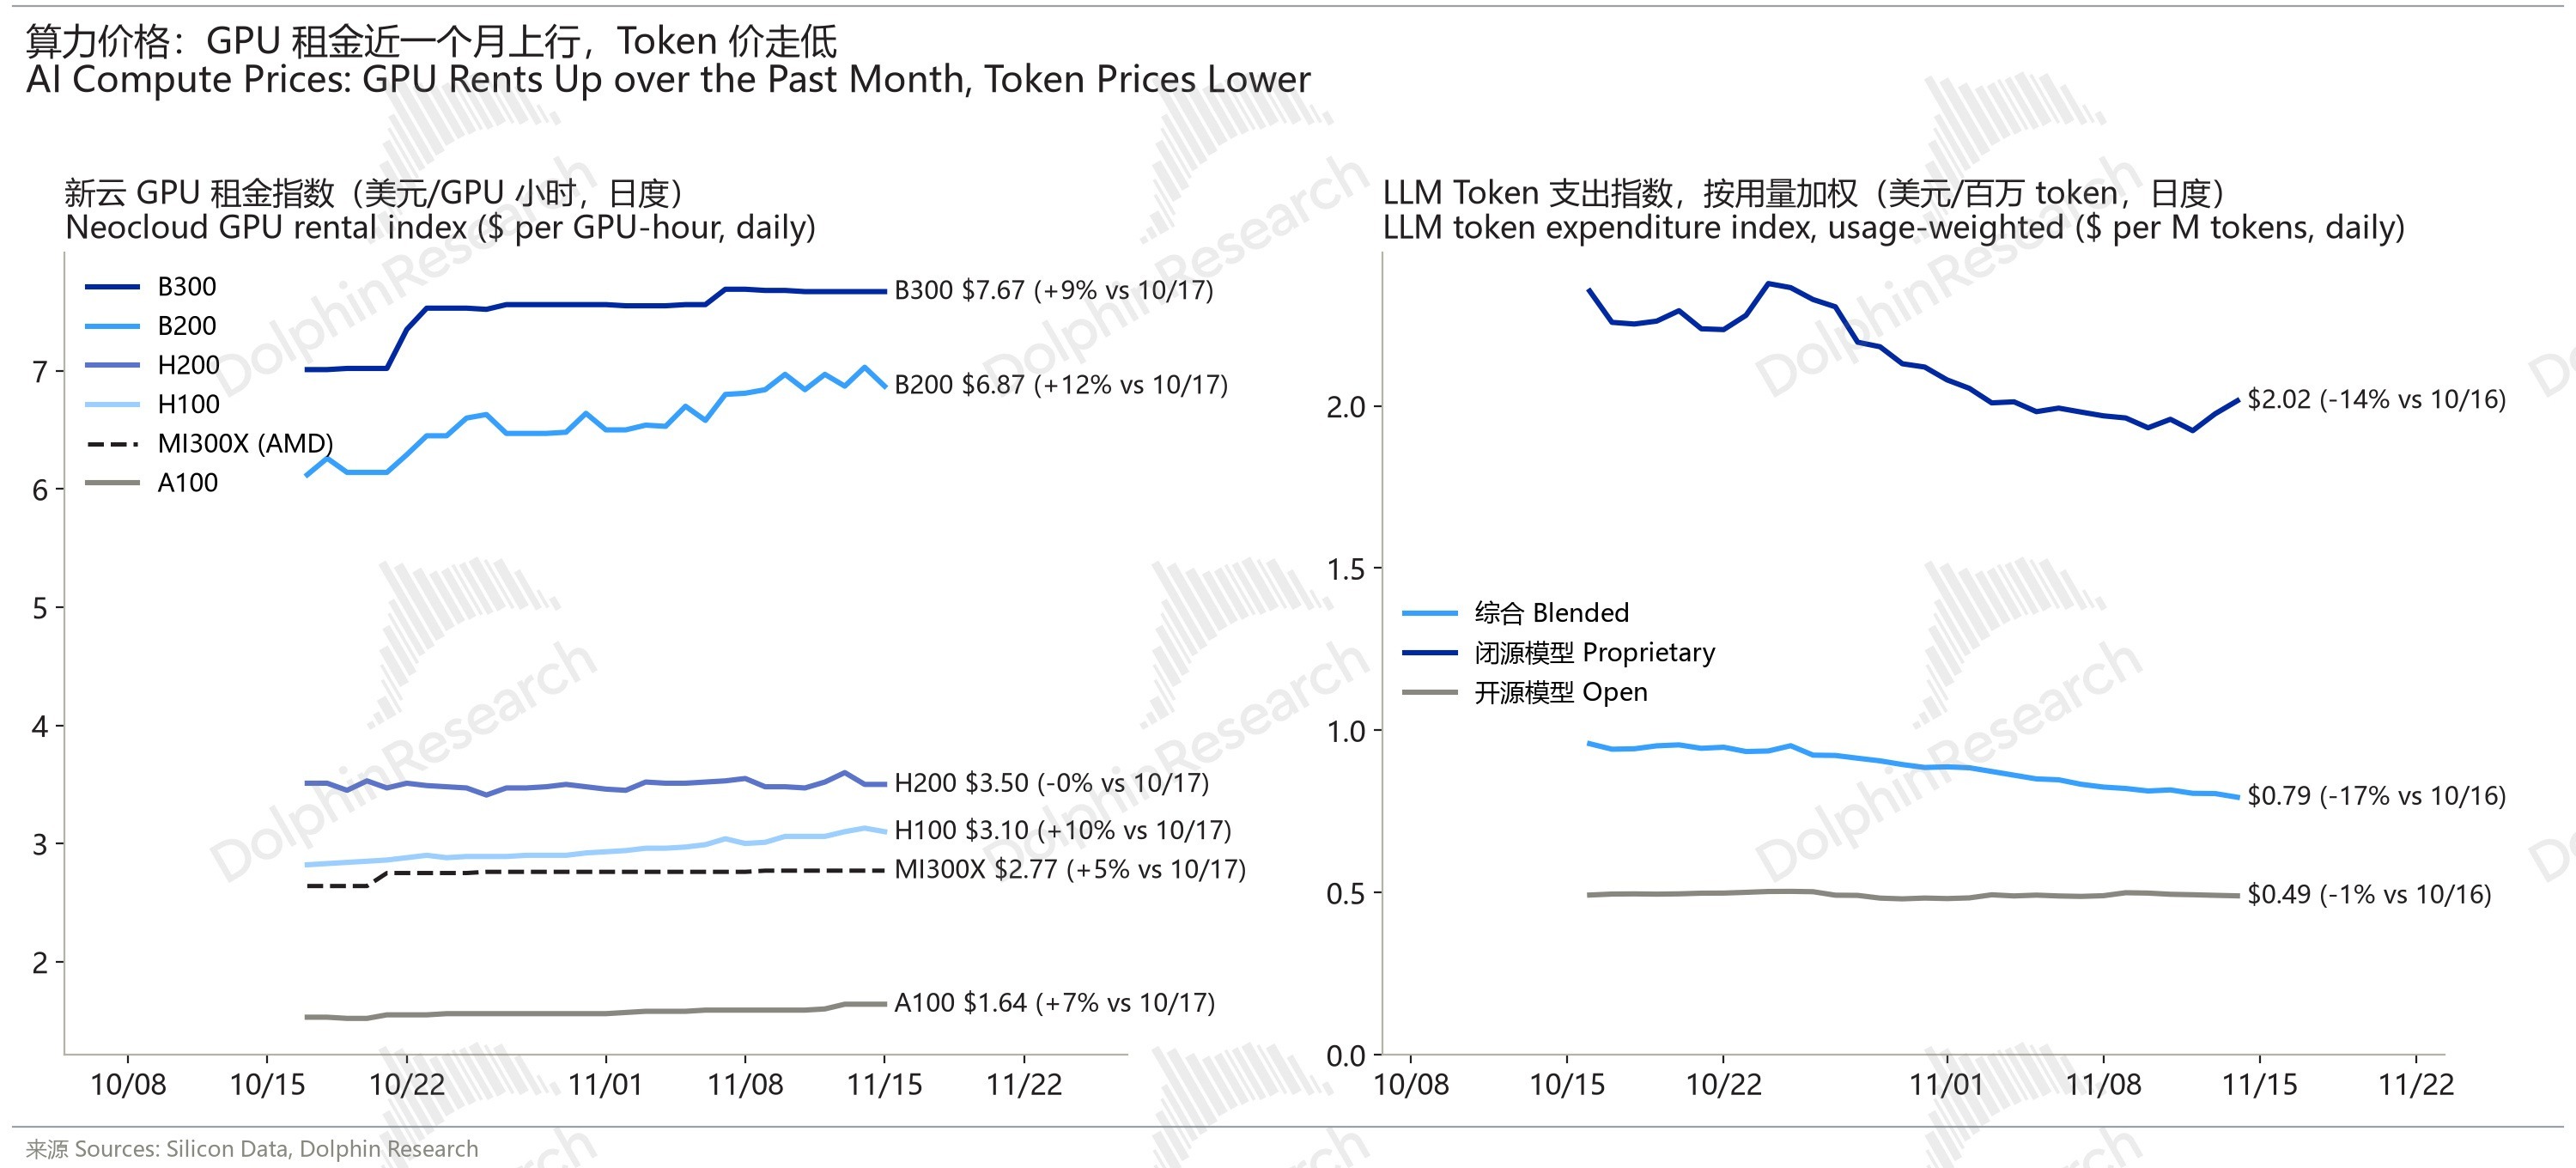
GPU rental: Silicon Data new-cloud index on 11/15 shows B200 at $6.87 per GPU-hour, +12% vs. 10/17 and +0.9% WoW. B300 at $7.67, H100 at $3.10, H200 at $3.50, both largely flat.
Token costs: Silicon Data LLM token spend index on 11/14 was $0.79 per mn tokens, -4.8% over seven days and -17% vs. 10/16. Closed-source at $2.02 (+1.8%), open-source at $0.49.
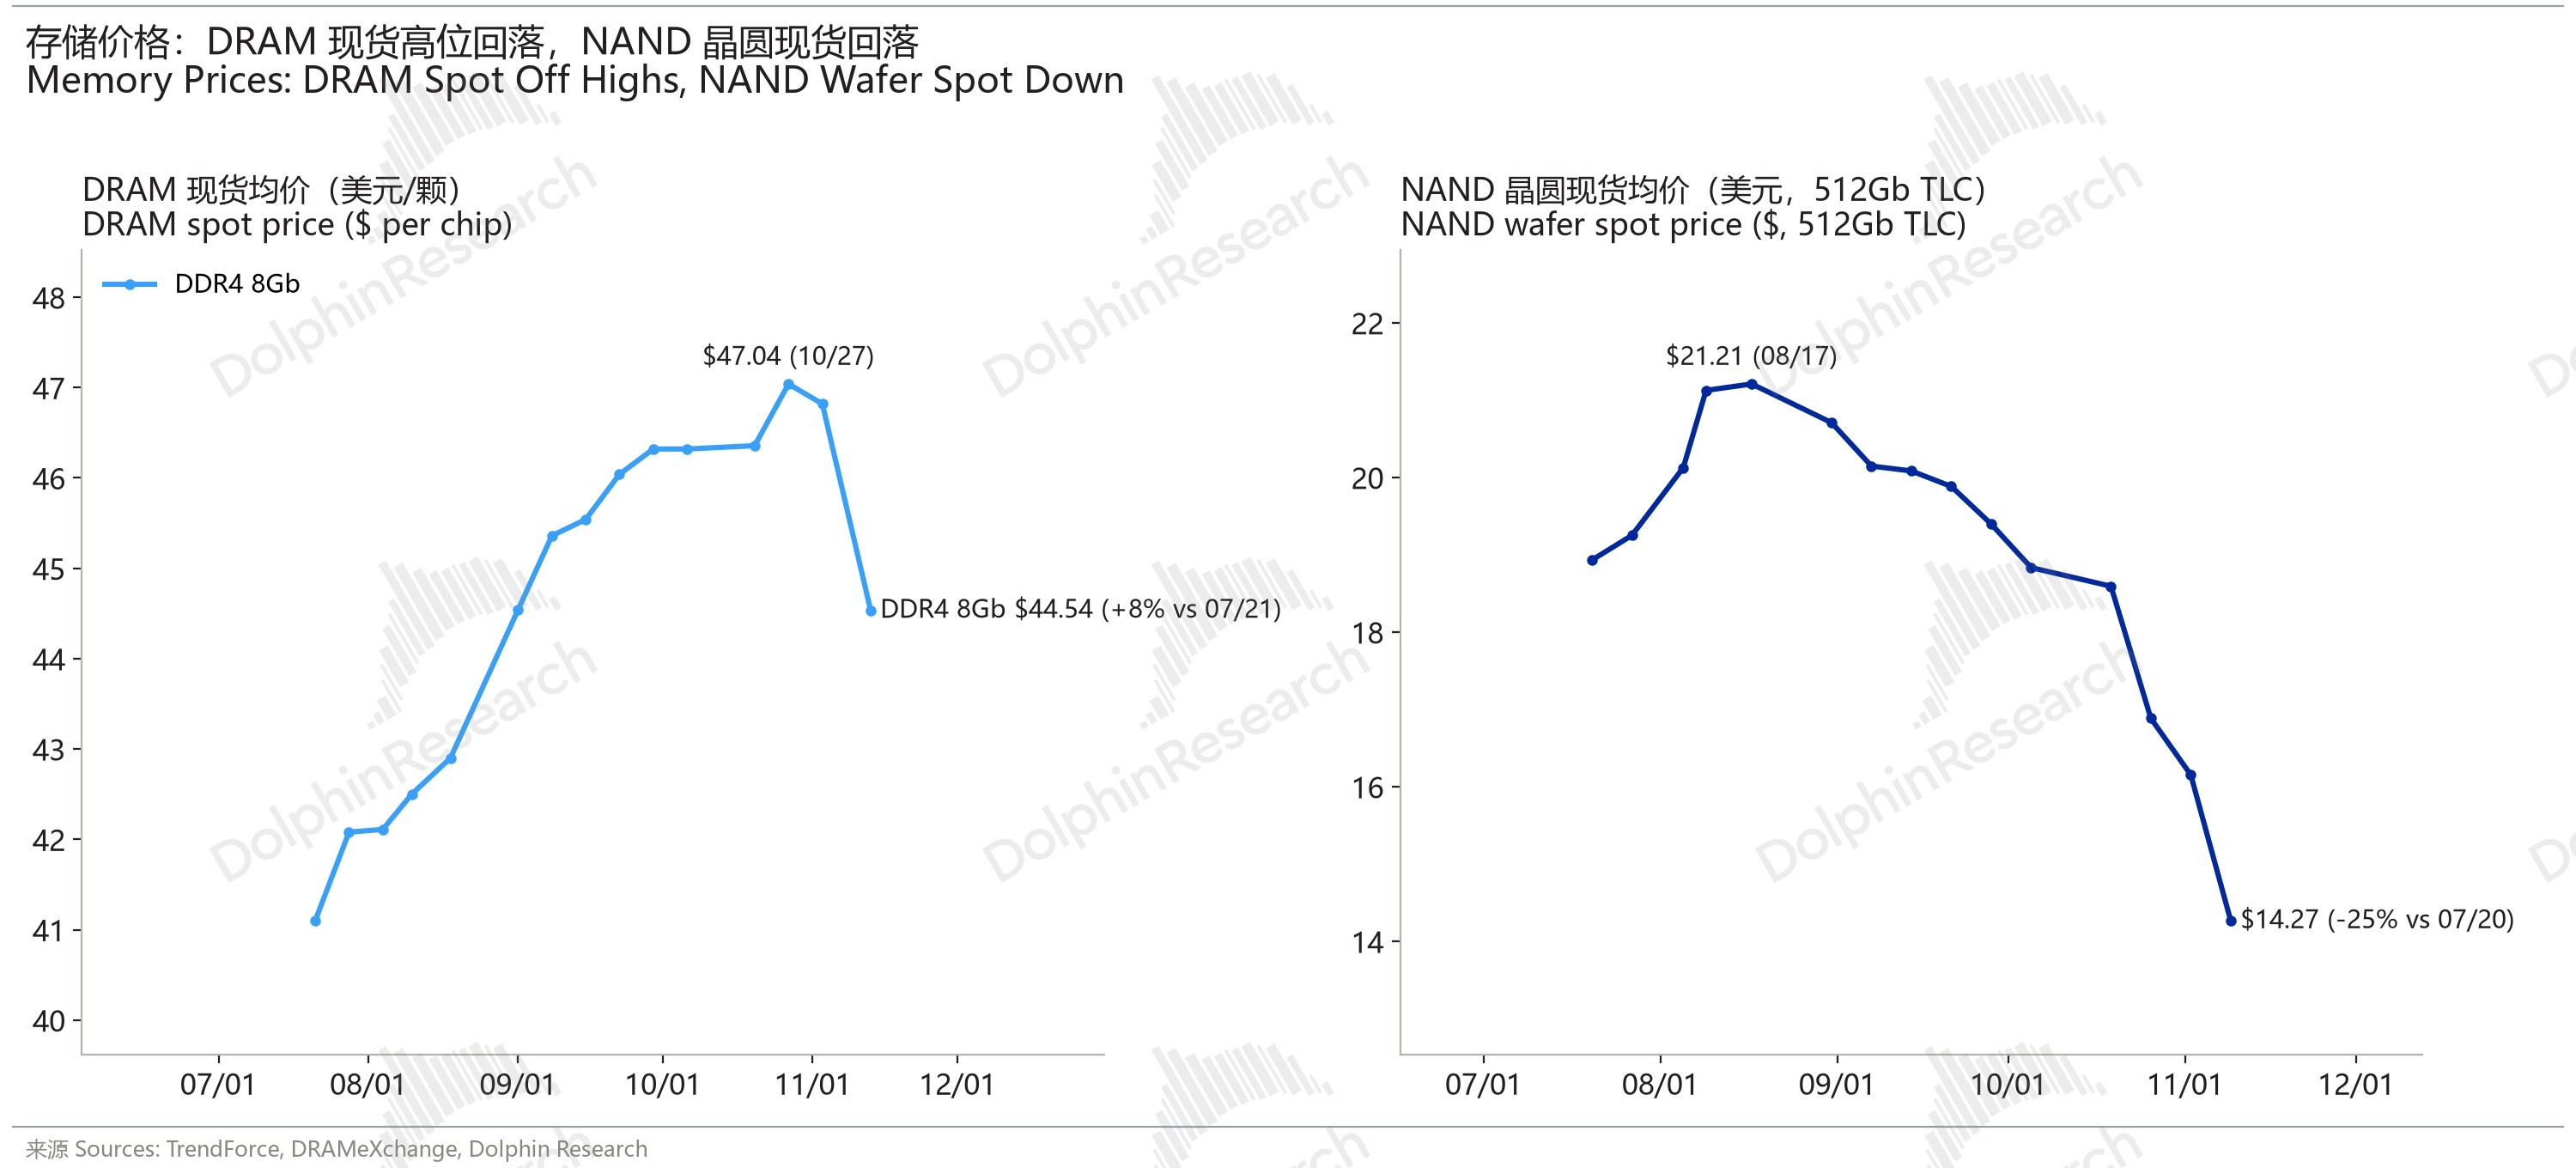
DRAM: DDR4 8Gb spot at $44.54, -5.3% vs. the 10/27 peak $47.04, -4.9% WoW, yet still +8% since late Jul.
NAND: 512Gb TLC wafer spot at $14.27, -33% vs. the 8/17 peak $21.21 and -24% over four weeks. BofA calls NAND the first category in this cycle that needs repricing.
4) Asia open and today's setup (11/16)
Asia open: Nikkei 225 +0.3% at the open; KOSPI +0.3% (KOSDAQ +0.9%). SK Hynix flat; Samsung Elec +0.2%; Tokyo Electron +0.3%; SoftBank Group +1.5%.
Semi catch-down spillover: with U.S. semis -3.4% and memory/networking leading declines, SK Hynix, Samsung, Japan/Korea equipment, and Taiwan networking/server chains likely open under pressure. China A-share optical module names dropped over 8% Fri; watch for stabilization today.
Controls and China assets: Treasury asked NVDA to respond within 10 days on China sales, and Commerce is plugging the overseas rental loophole. HK cloud, IDC, and LLM names likely stay pressured, while domestic compute beneficiaries have a floor; China Oct data (retail and TSF) are a swing factor.
Rates: with the 10Y UST at ~5.14% and USD stronger, high-multiple growth valuation remains under pressure. Flows likely favor cash-generating mega platforms.


Meta META|$1.64tn|+2.9%
Offshore desks say long-only funds rotated from NVDA into hyperscalers. Soros Fund Management added nearly 130k Meta shares in Q3, lifting its stake almost 6x. Microsoft MSFT|$3.89tn|+0.2%
Outlook, Teams, and Microsoft 365 suffered a widespread outage Fri, peaking at over 130k reports. Microsoft cited network expansion upgrades, not a cyberattack; lawmakers have requested details.
Ignite conference in San Francisco this week.
Alphabet GOOGL|$3.64tn|-1.0%
Rumors from some trackers point to search growth at ~9%, below the ~10% expected.
Institutions roughly estimate Anthropic at ~10% of Google Cloud revenue, contributing low-teens percentage points to growth (ex-TPU). Anthropic's shift to self-build compute would become a growth headwind for GCP.
Amazon AMZN|$2.88tn|-0.3%
ULA's Vulcan rocket failed 10 minutes after liftoff, costing Amazon 40 Leo satellites, the first mission failure for the Boeing–Lockheed JV.
Institutions roughly estimate Anthropic at ~10% of AWS revenue, contributing nearly 25% of its Q3 growth. A pivot to self-build compute would similarly weigh on AWS growth.

Applied Materials AMAT|$294.0bn|-2.7%
For calendar 2026, WFE growth guide moved to 40%+, with a first-ever 2027 WFE growth guide at 30%+. Institutions translate that to roughly $200bn–$208bn, below buy-side at $210bn–$230bn.
Management says 2027 cloud capex will grow over 50% to well above $1tn. Its largest customer continues to provide an 8-quarter rolling forecast, and none have asked to delay deliveries.
Next quarter has 14 weeks; on a 13-week basis, Dolphin estimates revenue roughly -1% QoQ, with semi systems up only ~1%. GPM at 50.4%, up just 10bps QoQ. (First Take)
Dolphin take: A near-term pause does not derail the upcycle; management sounds more confident. Two-year growth guides suggest downstream pull remains strong, but ex the extra week, systems are flat QoQ, constrained by cleanroom and supply chain. Logic is nearly 60% of systems; if logic cools, memory must step up, which hinges on memory capex. The 54% 2030 GPM goal looks tough at the current pace of QoQ expansion. (First Take)(Earnings review)

TSMC TSM|$2.07tn|-1.7%
Deutsche Bank says Nvidia accounts for roughly 25% of TSMC revenue, and freed-up CoWoS/3nm/2nm capacity can shift to AMD, Broadcom, and SpaceX.
DB also notes actual data center build capacity of ~30GW per year is below chip demand expectations north of 40GW, limiting downside risks.
The company plans a $500mn fund to invest in chip startups and upstream players, saying it wants to support the next Nvidia.
SMIC 0981.HK|
Co-CEO said full-year revenue should exceed $12bn, with AI-adjacent chips (BCD, specialty memory, controllers, etc.) driving faster-than-expected demand. Q3 ASP per wafer rose 1.8% QoQ.
On the call: some tool deliveries slip into next year, and price hikes are taking hold. Management expects AI-related supply-demand to remain very tight into 2027, with non-handset pricing rising next year, not falling. (Trans)
Intel INTC|$317.1bn|-2.5%
Soros Fund Management added 2.73mn shares in Q3, lifting the stake by over 27x. It cut NVDA by 19% in the same period.

Dell DELL|$219.1bn|-7.2%
Evercore says Dell's FY27 AI server target (~$74bn) is heavily reliant on NVDA and makes it one of the most exposed to leadership risk. Bernstein, however, put Dell on its preferred list as directly oversold.
Dell reports on 11/24.

Tesla TSLA|$1.54tn|-1.8% / SpaceX SPCX|$1.89tn|-0.6%
Bloomberg says merger talks are accelerating, with a possible Dec announcement. Tesla opened Cybercab orders to selected individuals at a $29,990 starting price, with first deliveries in Dec; NHTSA has launched a probe.
Starship's 15th test used the launch tower chopsticks to catch the ship for the first time. But the V3 booster had an anomaly on its maiden flight and exploded on splashdown; Bernstein says full reuse is key to the SpaceX valuation.

Baidu BIDU|+0.7%
Q3 results due today, see earnings preview at the end. Baidu recently launched a 1,024-card supernode, strengthening the domestic GPU substitution narrative.


| Date | Event | Watch |
| Mon 11/16 | BIDU and XPeng earnings; China Oct industrial output, retail sales, FAI, 70-city home prices; Fed Gov. Walsh at hearing | BIDU preview below |
| Tue 11/17 | NVDA earnings (after U.S. close); U.S. Oct retail sales | NVDA preview below |
| Wed 11/18 | Tencent, Palo Alto earnings; Anthropic pricing after close; NVDA interim CEO hosts all-hands | Tencent preview below |
| Thu 11/19 | Alibaba, Lenovo earnings; Anthropic lists on Nasdaq (ANT); FOMC minutes (SGT pre-dawn) | Alibaba preview below |
| ~11/25 | 10-day deadline for NVDA response to Sec. Besant | Whether the board pivots to an external CEO |

Nvidia NVDA|After 11/17
Watch: first earnings since Jensen stepped down, hosted by interim CEO Kress. Consensus revenue around $108.7bn (+91% YoY); market focus on guide, hyperscaler tone, and CEO search progress.
Dolphin watchpoints: whether the FY28 ~70% growth guide is revised, the size of cloud backlog (over 2 trillion last quarter), the GPM drag from memory price increases, and the accounting for China and remote compute revenue.
Baidu BIDU|11/16
Watch: UBS says internal DAUs for agents rose from 5k to 37k, with token usage rising but not yet monetized. Kunlun Chip spin-off progress.
Dolphin watchpoints: AI Cloud (RMB 7.3bn in Q2, +50% YoY), pace of legacy ad declines (-19% in Q2), capex and buybacks.
Tencent 0700.HK|11/18
Watch: with the overseas rental loophole closing and NYT naming a possible Malaysia DC, the market will watch how compute access affects capex and AI timelines.
Dolphin watchpoints: capex (RMB 52.8bn in Q2, 26% of revenue) and FCF (RMB -13.8bn in Q2), plus gaming and ads growth (+22% in Q2).
Alibaba BABA|11/19
Watch: Dolphin sees remote compute cuts as a major headwind for Alibaba's cloud growth outlook. Once fully domestic, Huawei chip supply remains uncertain; last week Alibaba confirmed T-Head's spin-off filing, with institutions estimating 700k unit shipments in 2027. (Original by Dolphin)
Dolphin watchpoints: external cloud revenue growth (45% last quarter), AI product revenue (RMB 12.376bn last quarter), capex and FCF (RMB -44.67bn last quarter).
<End here>
Recent Daily Recap
2026-11-13: Dolphin Daily | Jensen out: AMD and Broadcom feast, new cloud suffers
2026-11-12: Dolphin Daily | Retail lifts new cloud, fresh scandals weigh on Nvidia
Risk disclosure and disclaimer: Dolphin Research Disclaimer and General Disclosure
Direxion S&P 500 Bear 1X
USSPDN
S&P 500
US.SPX
Microsoft
USMSFT
Proshares UltraPro QQQ
USTQQQ
Alphabet
USGOOGL
TENCENT
HK00700
TENCENT-R
HK80700
Tencent HK SDR 10to1
SGHTCD
Tencent
USTCEHY
Tencent Holdings Limited
USTCTZF
.NDX
US.NDX
SOXX
USSOXX
HSTECH
HKHSTECH
NVDA
USNVDA
META
USMETA
METAM
USMETAM
AMD
USAMD
CSCO
USCSCO
ARM
USARM
AVGO
USAVGO
GOOG
USGOOG
GOOGM
USGOOGM
GOOGN
USGOOGN
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.