

Alibaba 2QF27 First Take: Solid print, extending last quarter's playbook of steady e-com and aggressive AI. Group revenu…
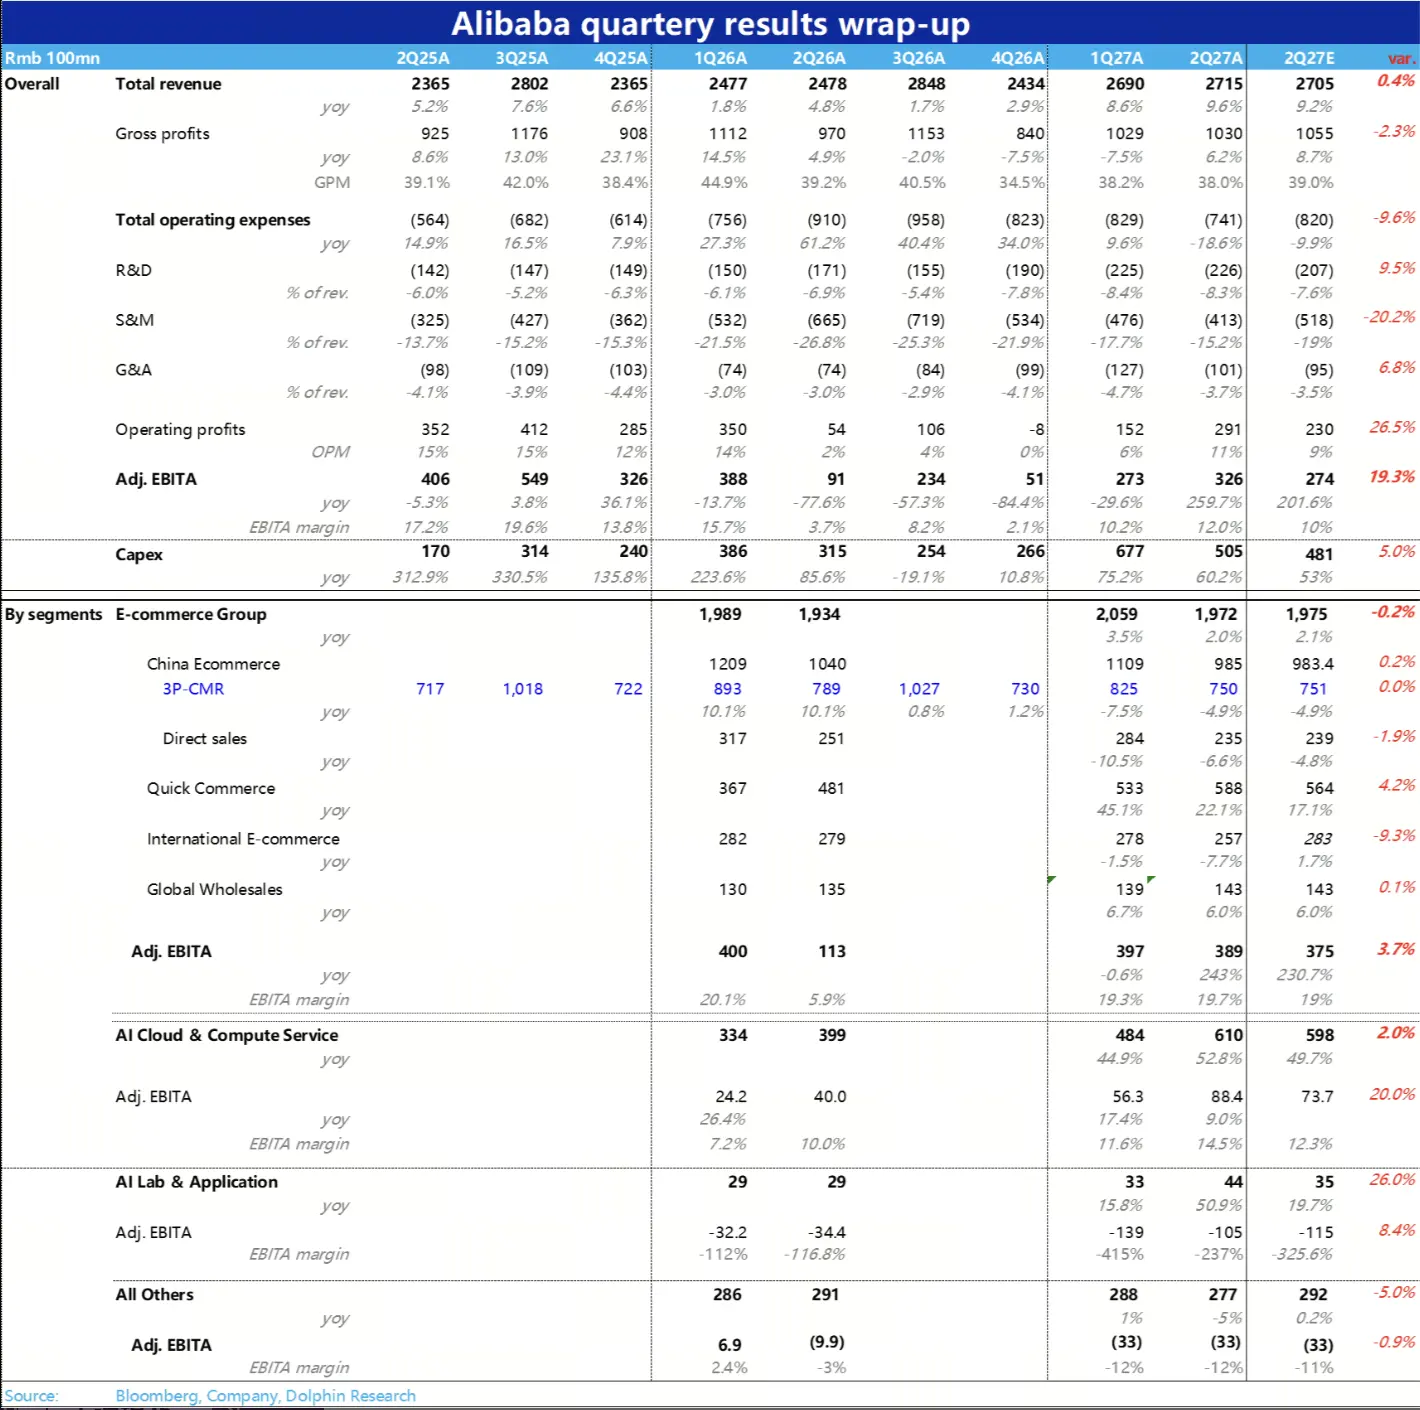
Alibaba 2QF27 First Take: Solid print, extending last quarter's playbook of steady e-com and aggressive AI. Group revenue was approx. RMB 271.5bn, +10% YoY and in line with consensus. Adj. EBITA was approx. RMB 32.6bn, up sharply YoY and QoQ and about 10% above latest bulge-bracket estimates, with no obvious weak spots.
AI Cloud growth accelerated as expected, with a clear margin uplift. The newly carved-out AI Labs & Apps saw faster revenue growth and narrower losses QoQ, while on e-com, CMR declines stabilized and food delivery loss reduction drove a profit rebound.
1) AI Cloud: Growth keeps accelerating; margins improved materially
AI Cloud and compute revenue was approx. RMB 61.0bn, +53% YoY, up from +45% last quarter and at the top end of the +50% to +53% range expected by major banks. EBITA margin rose to 14.5%, higher QoQ and well above the ~12.5% many expected. Both growth and profitability moved in the right direction.
Revenue from external customers grew even faster at +64% YoY vs. +45% last quarter. Growth at Alibaba Cloud and T-Head remains robust.
2) E-com: CMR declines stabilized; profitability rebounded materially
Nominal CMR fell approx. 5% YoY, still negative but stabilizing and in line with consensus. Excluding the revenue offset from the new merchant partnership program, CMR was approx. +1% YoY, similar to last quarter.
On the back of sizable YoY loss reduction in food delivery and stable profitability in domestic long-distance e-com, the commerce group delivered adj. EBITA of approx. RMB 38.9bn, more than doubling YoY and broadly in line with major banks. Intl commerce revenue declined 8% YoY, mainly due to EU customs reform impacting AliExpress.
While broader commerce was not flashy, growth has stabilized. Combined with post-loss-reduction profit recovery, the trajectory looks decent.
3) AI Labs & Apps: Revenue accelerated; losses narrowed QoQ
The new AI segment, covering foundation-model R&D and Qwen applications across 2B and 2C, generated approx. RMB 4.4bn in revenue, +51% YoY and faster than ~16% last quarter. Losses were approx. RMB 10.5bn, narrowing from ~RMB 13.9bn last quarter. Faster growth with smaller losses is a constructive trend.
4) Capex & Cash Flow: Investment remains high; FCF outflows narrowed
Capex was approx. RMB 50.5bn, +60% YoY, still elevated but down from ~RMB 67.7bn last quarter and below some pre-print estimates. Similarly, FCF outflow remained large at RMB 34.5bn but narrowed meaningfully QoQ.
High investment and the resulting cash pressure are the one clear blemish this quarter. That said, the sequential trend has improved.$BABA-W(09988.HK) , $Alibaba(BABA.US)
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.