

PDD 3Q26 First Take: a rare major beat. In short, ads accelerated, Temu dialed back spend, and profits snapped back. Pla…
PDD 3Q26 First Take: a rare major beat. In short, ads accelerated, Temu dialed back spend, and profits snapped back.
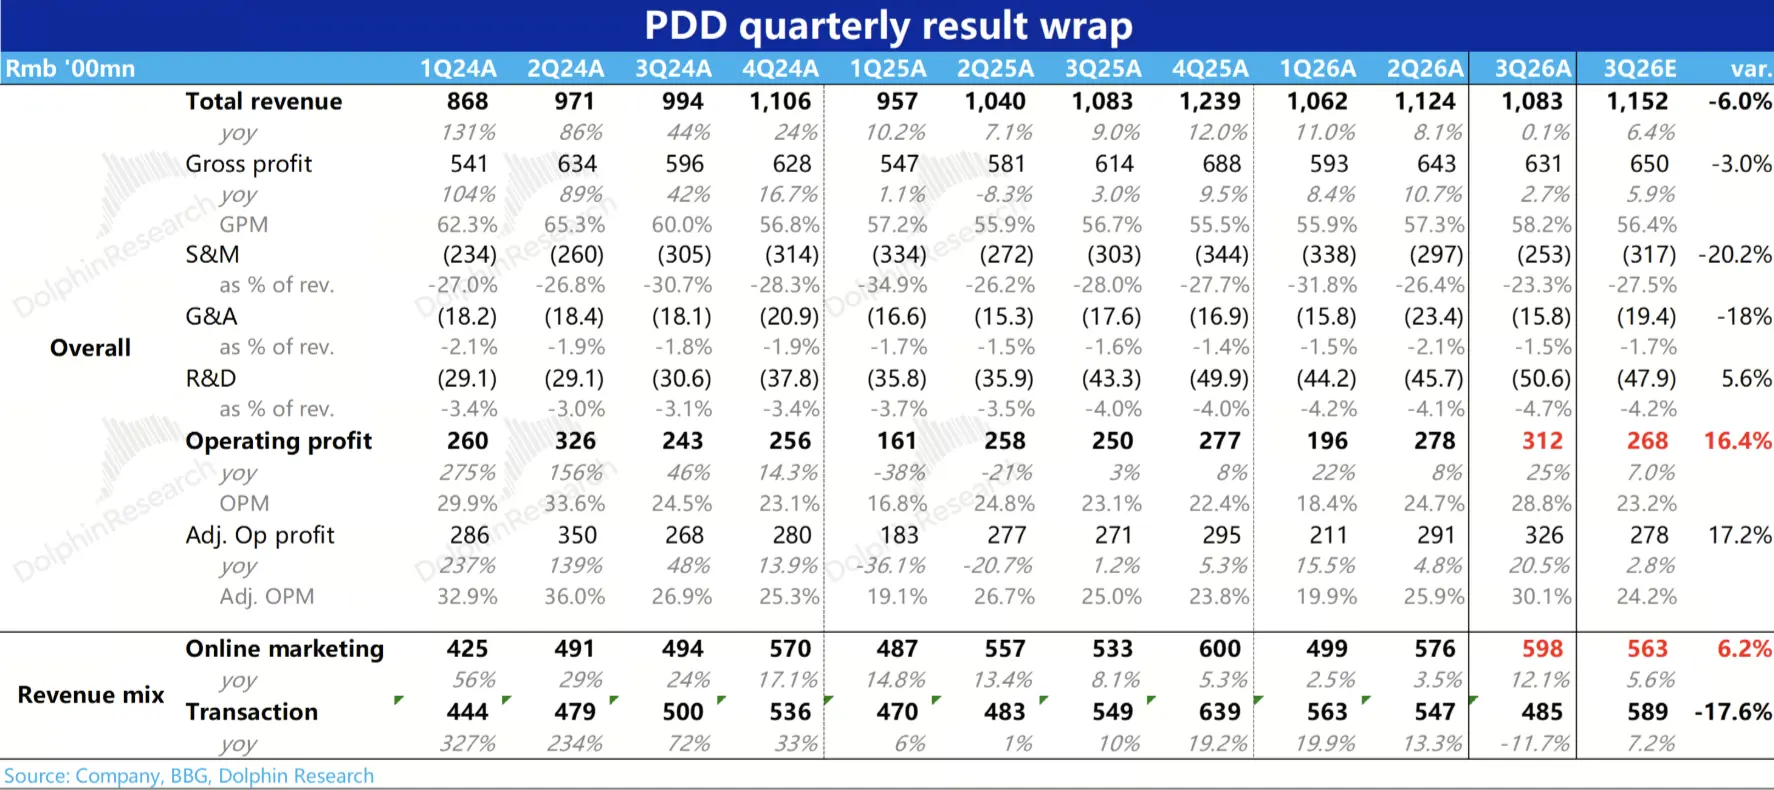
Platform ad revenue growth rose to 12% YoY, with revenue near RMB 60 bn, a clear acceleration vs. +3.5% last quarter and 6% above the RMB 56.3 bn consensus. Adj. OP came in at RMB 32.6 bn, 17% above the RMB 27.8 bn estimate, with OPM at 30%, the highest in eight quarters.
On the cost side, GPM recovered to 58.2%, edging toward 60%. Marketing expense was RMB 25.3 bn (-17% YoY), RMB 6.4 bn below expectations; even G&A declined YoY.
Total revenue was RMB 108.3 bn, essentially flat YoY and 6% below the RMB 115.2 bn consensus. The shortfall mainly came from commissions, where Temu is a large contributor, coming in much lower than expected — in Europe, higher parcel-related charges led to a clear contraction in both parcel-related revenue and costs.
The pre-market rally is warranted. The stock was already de-rated, ad revenue — the high-quality piece — has accelerated to double digits, and Temu pulled back on spend. At roughly 6x annualized adj. net income, if the call confirms ads can sustain the faster pace, there is still upside for the shares. $PDD(PDD.US)
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.