I'm LongbridgeAI, I can summarize articles.
Zhitong Finance APP learned that on November 9, the China Passenger Car Association (CPCA) released its analysis of the national passenger car market for October 2026. In October 2026, national passenger car retail sales totaled 1.643 million units, down 27.1% year-on-year but up 1.5% month-on-month; cumulative retail sales from January to October reached 14.978 million units, a year-on-year decline of 22.3%. The most prominent feature of the domestic auto market in October was "failing to boom during the peak season," with the traditional "Silver October" severely lacking luster. Since the Mid-Autumn Festival fell in September, October had a longer sales period, resulting in better month-on-month performance compared to September. This year, the purchasing performance of first-time buyers, who typically support growth in the autumn and winter auto markets, was poor. The sluggishness in the A00 and A-segment markets indicates that recent auto market policies have primarily supported consumption upgrades, and the raised threshold for subsidy eligibility has somewhat suppressed the car-buying demand of those without vehicles.
1. Review of the National Passenger Car Market in October 2026
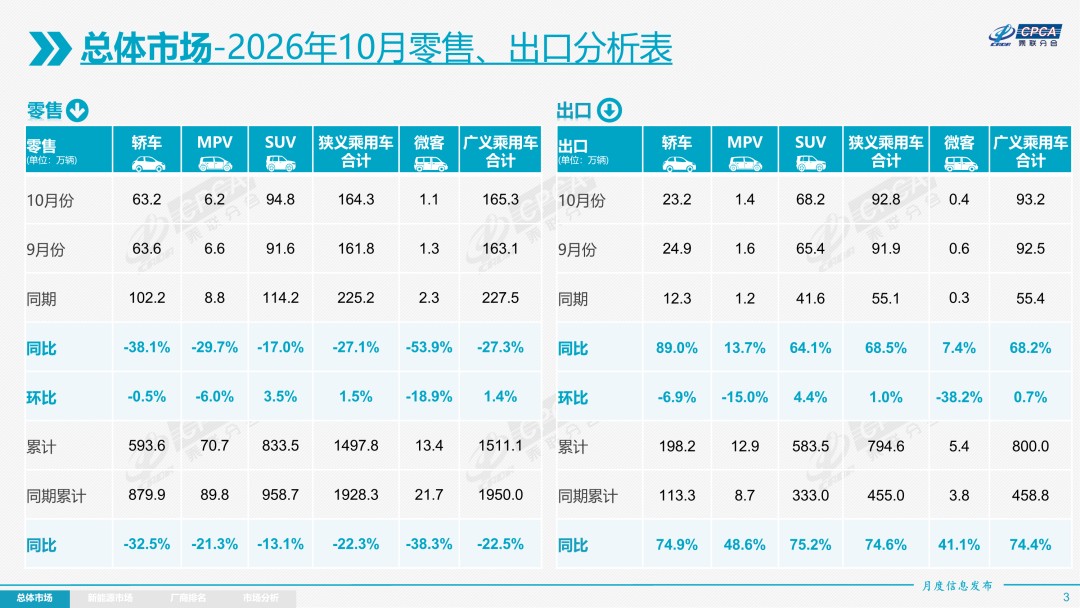
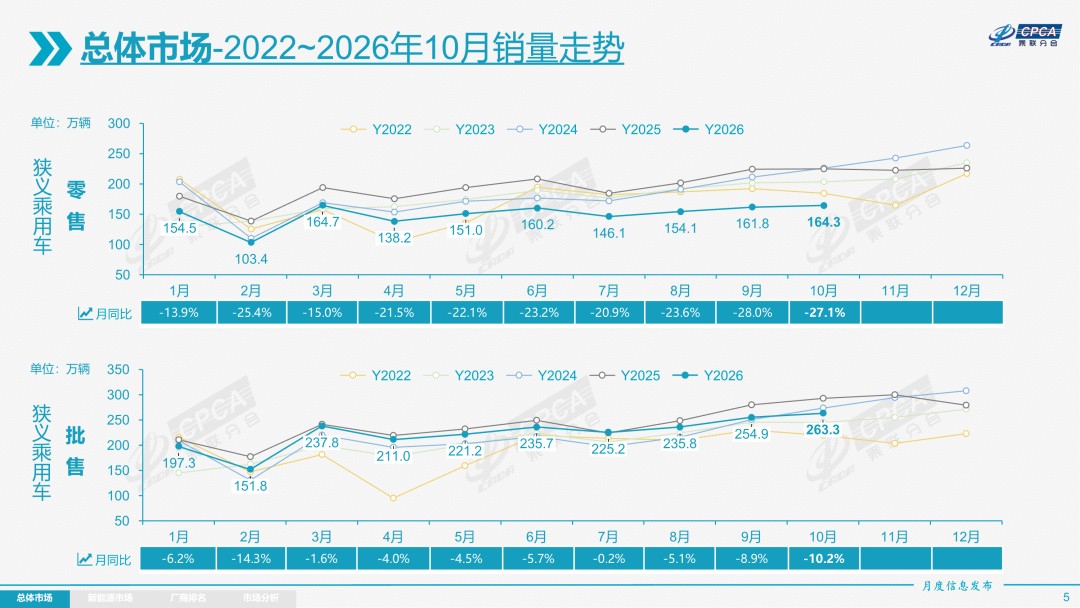
Retail: In October 2026, national passenger car retail sales totaled 1.643 million units, down 27.1% year-on-year and up 1.5% month-on-month; cumulative passenger car retail sales from January to October reached 14.978 million units, a year-on-year decline of 22.3%.
Against the backdrop of pressure on the overall auto market and a year-on-year decline in retail sales in October 2026, strong export performance became a key variable supporting automakers' sales volumes. Moreover, the export structure showed a distinct characteristic of "mid-to-low-priced mainstream models," which directly helped mainstream domestic brands stand out more prominently amidst diverging performances. Specifically, passenger car exports (including complete vehicles and CKD) reached 928,000 units in October, a year-on-year increase of 68.5%, with exports accounting for a high 35% of manufacturers' sales (compared to 19% last year). Among these, new energy passenger car exports totaled 582,000 units, a significant year-on-year increase of 144.7%, with A00 and A0 segment battery electric vehicles (BEVs) accounting for 56% of BEV exports. Since export models are mainly mid-to-low-priced mainstream vehicles, domestic brands focusing on cost-performance and scale advantages (such as BYD, Chery, and Geely) demonstrated stronger sales resilience driven by exports, while automakers relying on high-end or pure internal combustion engine (ICE) models faced greater pressure. This confirms the core logic of the current auto market: under the pattern of "domestic stock competition and overseas incremental breakthrough," the structural dividends of exports are reshaping the competitive ranking of domestic brands.
The most prominent feature of the domestic auto market in October was "failing to boom during the peak season," with the traditional "Silver October" severely lacking luster. Since the Mid-Autumn Festival fell in September, October had a longer sales period, resulting in better month-on-month performance compared to September. After the autumn harvest, income realization and colder weather should have highlighted vehicle usage demand, but this year, the purchasing performance of first-time buyers, who support growth in the autumn and winter auto markets, was poor. The sluggishness in the A00 and A-segment markets indicates that recent auto market policies have primarily supported consumption upgrades, and the raised threshold for subsidy eligibility has somewhat suppressed the car-buying demand of those without vehicles. The long-term lack of new product launches in the ICE vehicle market, coupled with rising usage costs, is unfavorable for the full release of purchasing power among first-time buyers.
Recently, oil prices have remained at high levels, and prices for non-ferrous metals and minerals have risen, leading to low consumer purchasing power and willingness to buy.
Overall, the passenger car market in October exhibited five distinct characteristics: First, total volume continued to face deep year-on-year pressure, with limited month-on-month recovery, and extreme structural divergence. "Accelerated shrinkage of ICE vehicles and resilient leadership of new energy vehicles" became the market main theme, with high oil prices continuously accelerating the pace of "oil-to-electricity substitution." Second, while new energy penetration rates should have seasonally stabilized in autumn, they continued to hit new highs this year. In October, the new energy retail penetration rate climbed to 67.5%, and the wholesale penetration rate reached 67.3%, both setting historical records. Third, the extended-range electric vehicle (EREV) market landscape underwent significant changes, with strong growth from Xiaomi and Leapmotor driving month-on-month strength in EREV sales in October. Fourth, ICE vehicle exports accounted for 40% of manufacturers' ICE wholesale sales in October (24% in October 2025), and new energy vehicle exports accounted for 33% of manufacturers' new energy wholesale sales (15% in October 2025). "Exports surpassing domestic demand" stabilized manufacturers' wholesale volumes and profits. This month, luxury new energy vehicle exports accounted for 78% of manufacturers' sales, making export volume the core driver of automakers' growth. Fifth, joint venture automakers actively broke through, with strong surges in pure electric new products from SAIC Volkswagen and FAW-Volkswagen, plug-in hybrid vehicles from SAIC General Motors becoming the main sales force, and strong performance from Japanese hybrid models. However, the current downturn in the auto market is a phased phenomenon caused by the superposition of short-term policy disturbances and a high base, not a peak in the fundamentals of car popularization. The characteristic of "high popularity in big cities and weak popularity in counties and townships" is particularly evident, and the blue ocean of first-time buyer demand in lower-tier counties remains vast.
In October, ICE vehicle retail sales dropped 45% year-on-year, with pure ICE vehicles down 51% and ordinary hybrid vehicles up 28%. Among ICE vehicles, domestic brands fell 46% year-on-year, mainstream joint ventures fell 46%, and luxury brands fell 37%, all indiscriminately impacted by high oil prices.
In October, new energy vehicle retail sales decreased 13.7% year-on-year, with domestic brands down 15%, mainstream joint ventures up 69%, and luxury brands down 45%. Domestic retail sales of A00 segment electric vehicles from domestic brands suffered a larger decline due to unfavorable subsidy policies.
In October, domestic brand retail sales reached 1.21 million units, down 22% year-on-year and up 7% month-on-month. The domestic retail share of domestic brands for the month was 73.8%, an increase of 4.8 percentage points year-on-year. Overall, domestic brands performed relatively steadily in the new energy and export markets.
In October, mainstream joint venture brand retail sales were 320,000 units, down 38% year-on-year and up 2% month-on-month.
In October, the retail share of German brands was 12.6%, down 1.1 percentage points year-on-year; Japanese brands had a retail share of 10.2%, down 2.1 percentage points year-on-year. The US brand market retail share was 2.7%, down 1.1 percentage points year-on-year.
In October, luxury car retail sales were 110,000 units, down 39% year-on-year and down 34% month-on-month. The retail share of luxury brands in October was 7%, down 1.4 percentage points year-on-year.
Exports: According to CPCA data, passenger car exports (including complete vehicles and CKD) in October were 928,000 units, up 68.5% year-on-year and 1.0% month-on-month, accounting for 35% of passenger car manufacturers' sales (36% last month, 19% in the same period of 2025). New energy vehicles accounted for 62.8% of total exports in October, a significant increase of 20 percentage points compared to the same period last year. Domestic brand exports reached 810,000 units in October, up 77% year-on-year; joint venture and luxury brand exports were 118,000 units, up 28% year-on-year.
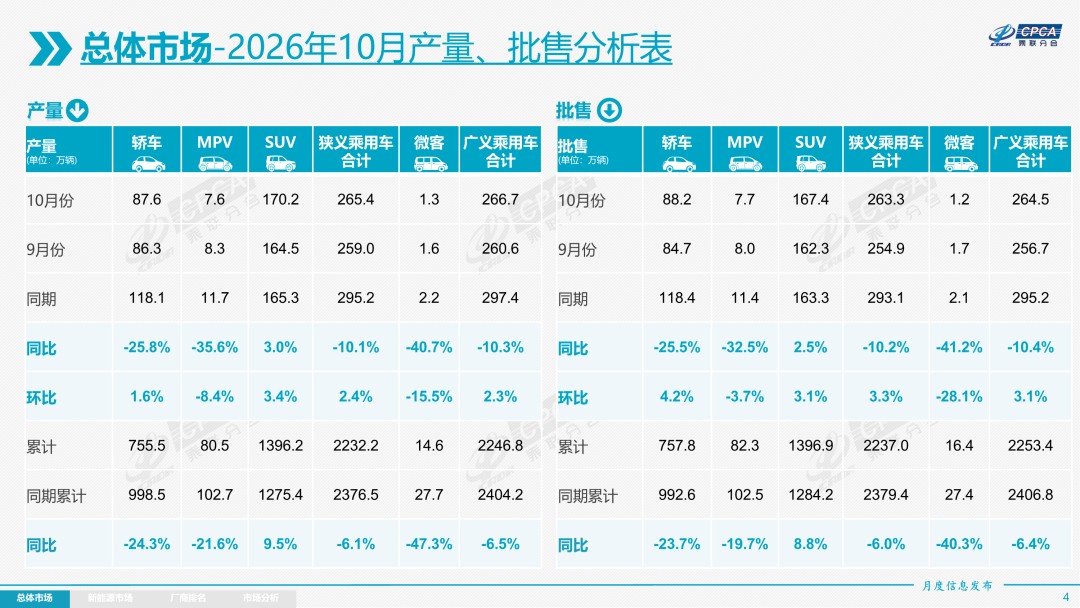
Production: Passenger car production in October was 2.654 million units, down 10.1% year-on-year and up 2.4% month-on-month. Luxury brand production decreased 26% year-on-year and 12% month-on-month; joint venture brand production decreased 37% year-on-year and 15% month-on-month; domestic brand production decreased 2% year-on-year and increased 7% month-on-month.
Wholesale: In October, national passenger car manufacturers wholesaled 2.633 million units, down 10.2% year-on-year and up 3.3% month-on-month. Boosted by the surge in exports, the year-on-year growth rate of passenger car wholesale in October was 16.9 percentage points higher than the retail growth rate. Domestic automakers wholesaled 2.09 million units in October, down 2% year-on-year and up 6% month-on-month. Mainstream joint venture automakers wholesaled 368,000 units, down 36% year-on-year and up 2% month-on-month. Luxury car wholesale was 174,000 units, down 25% year-on-year and down 22% month-on-month.
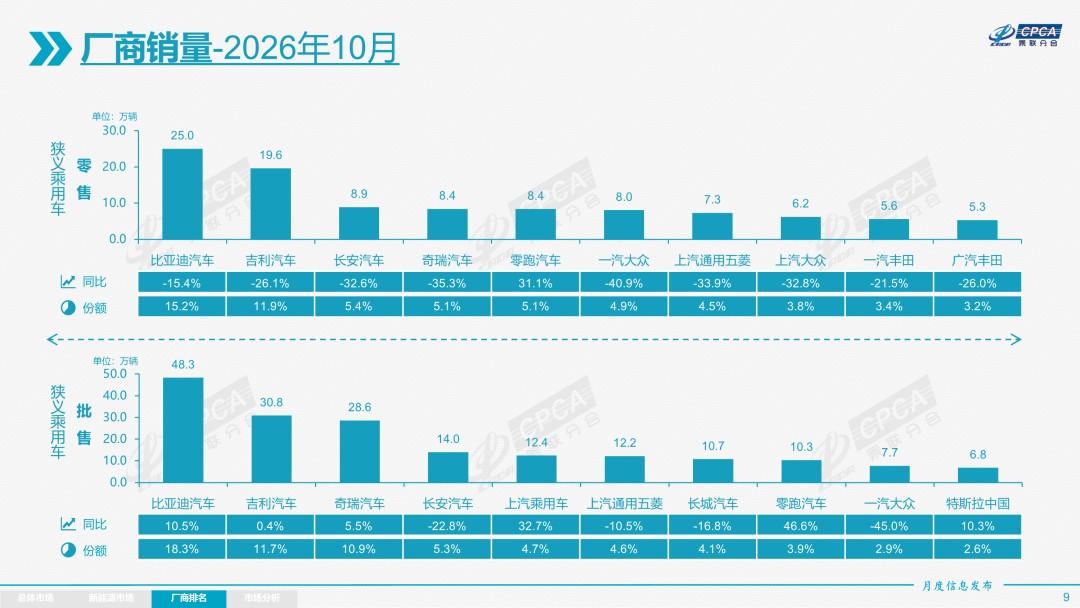
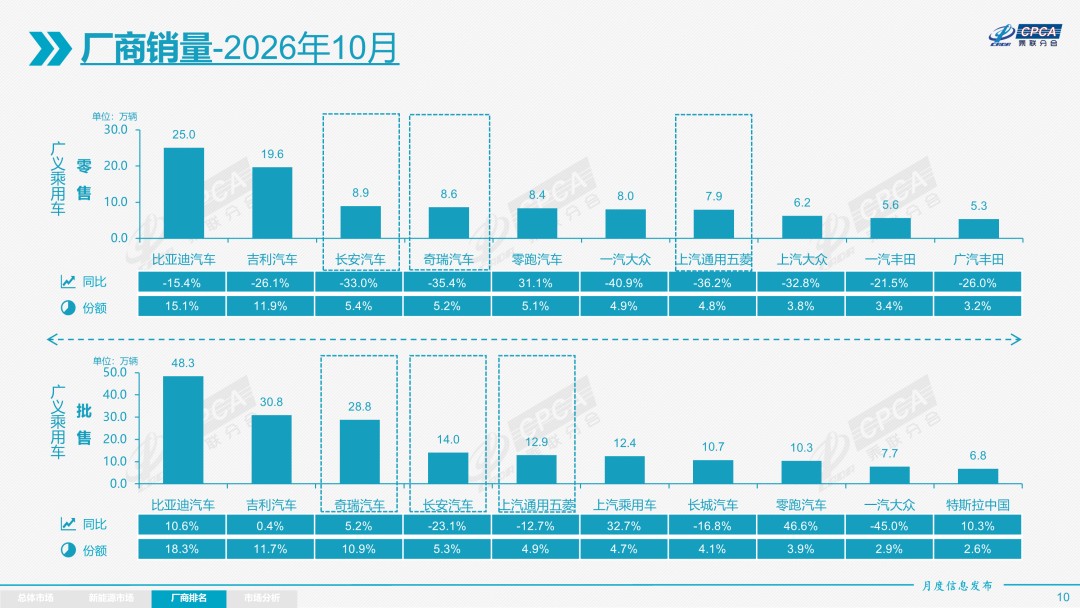
The overall wholesale pattern of major passenger car manufacturers continued to change in October, with automakers such as Leapmotor, GAC Aion, BAIC Motor, and SAIC Passenger Vehicles achieving high year-on-year growth of over 20%. Market concentration remained relatively stable in October, with 8 passenger car manufacturers having wholesale sales of over 100,000 units (6 last month, 7 in the same period last year), accounting for 63.5% of the overall market share (54% last month, 55% in the same period). Manufacturers with wholesale volumes of 50,000-100,000 units accounted for 16.1% of the share (21% last month, 22% in the same period), and those with 10,000-50,000 units accounted for 16.8% (22% last month, 22% in the same period).
Inventory: Due to significant operational pressure in the October market, manufacturers' wholesale volumes were 21,000 units lower than production, while manufacturers' monthly domestic wholesale volumes were 63,000 units higher than domestic retail. De-stocking features were prominent this year, with overall passenger car industry inventory decreasing by 600,000 units from January to October (a decrease of 100,000 units in the same period of 2025, 940,000 units in 2024, and 90,000 units in 2023).
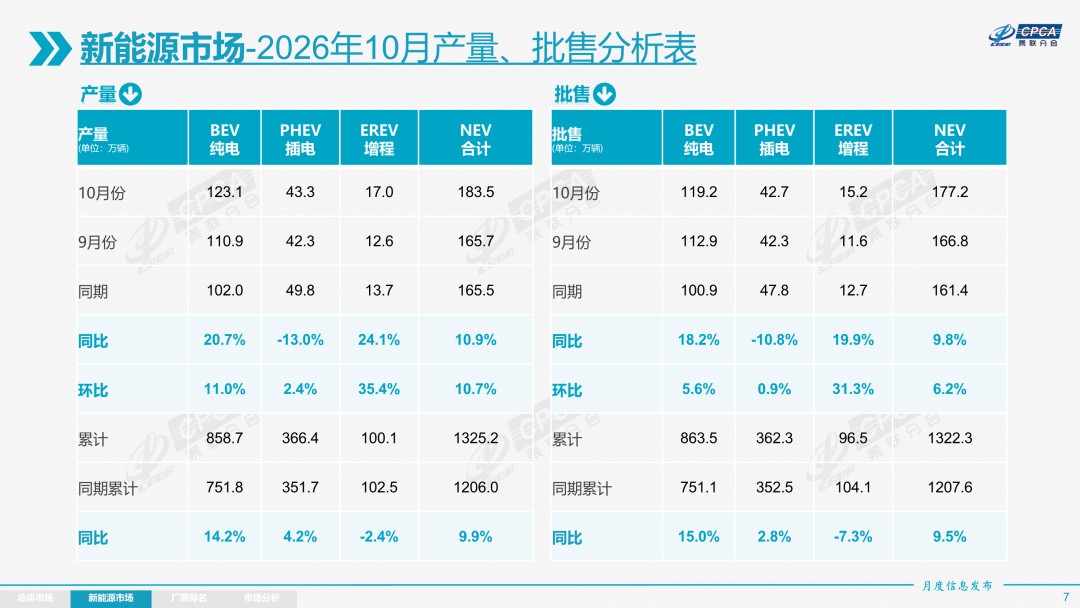
New Energy: New energy passenger car production reached 1.835 million units in October, up 10.9% year-on-year and 10.7% month-on-month. Cumulative new energy passenger car production from January to October reached 13.252 million units, up 9.9% year-on-year.
New energy passenger car wholesale sales reached 1.772 million units in October, up 9.8% year-on-year and 6.2% month-on-month; cumulative new energy passenger car wholesale sales from January to October reached 13.223 million units, up 9.5% year-on-year. Conventional ICE passenger car wholesale sales reached 860,000 units in October, down 35% year-on-year and down 2% month-on-month.
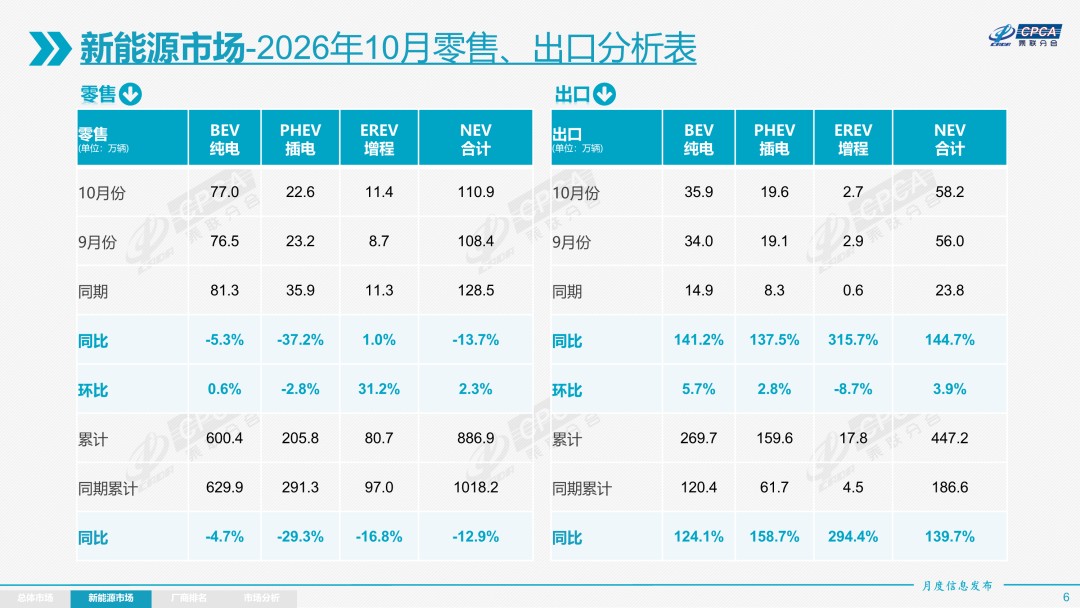
New energy passenger car market retail sales were 1.109 million units in October, down 13.7% year-on-year and up 2.3% month-on-month; cumulative new energy passenger car market retail sales from January to October were 8.869 million units, down 12.9% year-on-year. Conventional ICE passenger car retail sales were 530,000 units in October, down 45% year-on-year and down 0.1% month-on-month; among them, ordinary hybrid vehicles increased 28% year-on-year and 1.3% month-on-month.
New energy passenger car manufacturer exports were 582,000 units in October, up 144.7% year-on-year and 3.9% month-on-month; cumulative new energy passenger car manufacturer exports from January to October were 4.472 million units, up 139.7% year-on-year. Conventional ICE passenger car exports were 346,000 units in October, up 11% year-on-year and down 4% month-on-month.
1) Wholesale: The new energy vehicle manufacturer wholesale penetration rate in October was 67.3%, an increase of 12 percentage points compared to October 2025. The new energy vehicle penetration rate for domestic brands was 77.1%; for luxury cars, it was 48.4%; and for mainstream joint venture brands, it rose to 20.7%.
Pure electric wholesale sales in October were 1.192 million units, up 18.2% year-on-year and 5.6% month-on-month; narrow-sense plug-in hybrid (PHEV) sales were 427,000 units, down 10.8% year-on-year and up 0.9% month-on-month; EREV wholesale was 152,000 units, up 19.9% year-on-year and 31.3% month-on-month. In the October new energy wholesale structure: pure electric accounted for 67.3% (year-on-year +4.8%, month-on-month -0.4%), narrow-sense PHEV accounted for 24.1% (year-on-year -5.5%, month-on-month -1.3%), and EREV accounted for 8.6% (year-on-year +0.7%, month-on-month +1.6%).
B-segment electric vehicle wholesale in October was 307,000 units, up 12% year-on-year and down 7% month-on-month, accounting for 26% of the pure electric share, a decrease of 1.4 percentage points from the same period last year. The A00 segment economy electric vehicle market faced significant pressure, with A00 wholesale sales of 101,000 units in October, down 41% year-on-year but up 29% month-on-month, accounting for 8% of the pure electric share, a substantial decrease of 8.6 percentage points from the same period last year. A0 segment wholesale sales were 456,000 units, accounting for 38% of the pure electric share, up 13.6% year-on-year. A-segment electric vehicles were 269,000 units, accounting for 23% of the pure electric share, down 3.6 percentage points year-on-year. From the long-term popularization trend, economy electric vehicles have the most growth potential; only the popularization of entry-level electric vehicles can truly drive sustainable incremental growth in the auto market.
In October, there were 25 passenger car models with wholesale sales exceeding 20,000 units (23 last month): BYD Song (74,365 units), Geely Xingyuan (71,337 units), BYD Yuan UP (69,216 units), BYD Dolphin (39,096 units), Model Y (38,567 units), MG4 EV (35,876 units), Qiyuan Q05 (35,023 units), BYD Seagull (32,287 units), Hongguang MINI (31,402 units), Wuling Bingo (30,954 units), Leapmotor A10 (30,687 units), Fangchengbao Tai 7 (30,274 units), BYD Yuan PLUS (30,240 units), Tiggo 7 (30,239 units), Starship 7 (29,501 units), Model 3 (29,262 units), Chery JAECOO J5 (26,689 units), Xingyue L (26,433 units), Boyue (25,075 units), MG ZS (23,574 units), Jetour Traveler (23,306 units), BYD Seal 06 (22,467 units), BYD Sea Lion 06 (21,957 units), BYD Sea Lion 05 (21,106 units), and XPeng L03 (20,637 units). New energy models occupied an absolutely dominant position.
2) Retail: In October, the retail penetration rate of new energy vehicles in the overall domestic passenger car market was 67.5%, an increase of 10.5 percentage points year-on-year and 0.5 percentage points month-on-month. For domestic retail in October, the new energy vehicle penetration rate among domestic brands was 84.8%; among luxury cars, it was 19.4%; while among mainstream joint venture brands, it only rose to 19.7%. In terms of monthly domestic retail share of new energy vehicles, domestic brand new energy vehicles accounted for 68.2% in October, down 2.6 percentage points year-on-year; mainstream joint venture brand new energy vehicles accounted for 5.9%, up 2.6 percentage points year-on-year; new forces accounted for 23.9%, with brands like Leapmotor driving a 1.2 percentage point year-on-year increase in the new forces' share.
3) Exports: New energy passenger car exports in October were 582,000 units, up 144.7% year-on-year and 3.9% month-on-month. They accounted for 62.8% of passenger car exports, an increase of 20 percentage points from the same period last year; among them, pure electric vehicles accounted for 61.7% of new energy exports (62.6% last year), and the core focus, A00+A0 segment pure electric vehicles, accounted for 56.4% of pure electric exports (42.1% last year). With the emergence of scale advantages and expanding market demand for Chinese new energy vehicles, more Chinese-made new energy brand products are going global, with continuously improving overseas recognition. Narrow-sense PHEVs accounted for 33.7% of new energy exports (34.7% last year), and EREVs accounted for 4.6% (2.7% last year). Although recently affected by some interference from external countries, the number of developing countries importing domestic narrow-sense PHEVs is growing rapidly, showing clear advantages. Outstanding enterprises in new energy exports in October included: BYD Auto (165,194 units), Chery Auto (83,843 units), Geely Auto (80,119 units), Tesla China (59,012 units), SAIC Passenger Vehicles (42,030 units), Changan Auto (30,343 units), Leapmotor (21,132 units), SAIC-GM-Wuling (16,866 units), XPeng Motors (13,326 units), GAC Aion (12,150 units), and Great Wall Motor (12,029 units).
In terms of overseas system construction, some domestic brands have a high proportion of CKD exports, demonstrating excellent international performance. Among them, Great Wall Motor's CKD export ratio was 31.1%, SAIC-GM-Wuling's was 41.9%, Leapmotor's was 8.0%, and SAIC Passenger Vehicles' was 27.6%.
4) Automakers: The overall trend of new energy passenger car enterprises was strong in October. BYD Auto's dual drive of pure electric and plug-in hybrid solidified the leading position of domestic brands in new energy. Narrow-sense PHEV performance, represented by BYD Auto, Geely Auto, and Chery Auto, remained consistently strong, while SAIC Passenger Vehicles, SAIC Volkswagen, and SAIC General Motors showed strong new energy growth. In terms of product launches, as domestic automakers implemented a "multi-pronged" strategy in the new energy route, the market base continued to expand. The number of manufacturers with monthly new energy wholesale sales exceeding 10,000 units reached 23 (one less year-on-year, one less month-on-month), accounting for 95.5% of the total new energy passenger car volume (94.3% last month, 94.5% last year). These included: BYD Auto (482,610 units), Geely Auto (211,240 units), Chery Auto (133,890 units), Leapmotor (103,025 units), Changan Auto (99,494 units), SAIC-GM-Wuling (97,241 units), SAIC Passenger Vehicles (76,479 units), Tesla China (67,829 units), XPeng Motors (50,237 units), Xiaomi Auto (50,168 units), Great Wall Motor (49,498 units), GAC Aion (43,160 units), NIO (34,246 units), Li Auto (29,025 units), Dongfeng Motor (28,141 units), Arcfox (24,857 units), Seres Auto (22,136 units), FAW Bestune (19,643 units), SAIC Volkswagen (17,975 units), FAW-Volkswagen (14,933 units), SAIC General Motors (12,344 units), FAW Hongqi (11,629 units), and GAC Toyota (11,058 units).
Domestic new energy passenger car retail brands exceeding 20,000 units were: BYD Auto (250,301 units), Geely Auto (131,708 units), Leapmotor (83,573 units), Changan Auto (68,925 units), SAIC-GM-Wuling (67,696 units), Xiaomi Auto (50,123 units), Chery Auto (44,747 units), SAIC Passenger Vehicles (38,881), Great Wall Motor (37,469 units), XPeng Motors (36,911 units), NIO (34,030 units), Harmony Intelligent Mobility Alliance (33,538 units), GAC Aion (30,011 units), Li Auto (27,018 units), Arcfox (24,857 units), Dongfeng Motor (21,262 units), and FAW Bestune (20,793 units).
5) New Forces: The retail share of new forces in October was 23.9%, up 1.2 percentage points year-on-year. Pure electric vehicles accounted for 66.9% of new force model sales, a significant decrease from 74.3% in the same period last year; sales of new force pure electric vehicles in the 100,000-150,000 RMB range increased substantially. Independent new energy brands of traditional domestic automakers, acting as "second-generation creators," performed strongly, with a share of 15.3%, up 0.8 percentage points year-on-year. Self-created new energy brands of large domestic groups such as Zeekr, Yipai Technology, Aion, Arcfox, and Voyah performed excellently.
6) Ordinary Hybrids: Ordinary hybrid passenger car wholesale in October was 123,000 units, up 38% year-on-year and down 2% month-on-month. Key contributors included FAW Toyota (34,794 units), GAC Toyota (30,540 units), Geely Auto (19,915 units), SAIC Passenger Vehicles (13,160 units), Great Wall Motor (10,749 units), Changan Ford (3,893 units), Dongfeng Honda (3,329 units), GAC Trumpchi (2,096 units), GAC Honda (1,752 units), and Changan Auto (1,525 units). Domestic ordinary hybrid models from Geely Auto, SAIC Passenger Vehicles, Changan Auto, and others have emerged strongly in overseas markets.
2. Outlook for the National Passenger Car Market in November 2026
There are 21 working days in November, the same as last year, but 2 more days than in October, resulting in longer effective production and sales time in November. November is a period of significant fluctuation in the auto market, where the external economic environment and seasonal demand will comprehensively affect the market. Historically, the auto market tends to be weaker in November.
Effective production and sales time in November is more abundant than in October. Colder weather and migrant workers returning home will drive the release of car purchases in county and township markets, creating structural opportunities for new energy and low-to-mid-end ICE vehicles. November is a reasonable time for proactive inventory buildup: year-end demand is relatively hot, and consumers have high demand for available inventory, requiring early stock reserves. The current constraint is insufficient dealer confidence, with some dealers looking for opportunities to exit, weakening the channel's reservoir function. Year-end market de-stocking pressure remains high.
The export side exhibits characteristics of "front-loaded rhythm and total volume overdraft." Exports gradually cool down in November, as overseas pre-Christmas car buying demand requires earlier transportation, concentrating the shipment window before mid-November. This year's rush to export will be significantly stronger: the expectation of reduced export tax rebates and the tightening of overseas tariff windows form a combined incentive, leading to early delivery of some orders. This pushes up short-term export data while also overdrawing export momentum for the first quarter of next year. This means that November exports provide a phased boost to the wholesale end, and should not be linearly extrapolated as a trend of strengthening.
According to data from the China Statistical Yearbook compiled by the CPCA: While car ownership has surged, the accident rate has plummeted, fully releasing the dividend of technical safety. Over eight years, car ownership increased from 232 million to 359 million, a growth of about 54.7%; while the accident rate per 10,000 cars dropped significantly from 7.2 to 3.9, a decrease of 45.8%. Against the backdrop of a substantial expansion in the total number of cars, the number of accidents actually decreased by 15.8%, and the number of injuries decreased by 29.4%. This fully demonstrates that under strong regulation, the popularization of passive safety (body structure, airbags) and active safety (AEB, assisted driving) technologies has significantly reduced the risk per vehicle. Enhanced safety confidence is conducive to the popularization of private cars.
"Shrinking first-time purchases and dominance of replacement purchases" weaken the year-end tail effect. Both ends of the replacement chain are constrained: poor disposal of used cars inhibits the efficiency of replacement conversion; weak income expectations among first-time buyers lengthen the car-buying decision cycle. Although there is still a balance in the trade-in subsidy, its marginal effectiveness is diminishing, serving more as a floor rather than driving incremental growth. The decline in lithium carbonate prices benefits battery costs, but the transmission has a time lag, and the beneficiaries are concentrated among head automakers with self-developed batteries. Overall, the auto market in November will see a mild month-on-month recovery and a narrowing year-on-year decline. Export rush shipments provide short-term support, but sustainability is questionable. The true recovery of the auto market depends on whether the replacement chain can be unblocked and whether consumer confidence can stop declining.
3. Auto Industry Profit Margin at 3.3% from January to September 2026, Sales Profit Margin at 1.4% in September
From January to September, industrial enterprises above designated size achieved operating revenue of 106.21 trillion yuan, up 6.6% year-on-year; incurred operating costs of 90.30 trillion yuan, up 6.1%; and the operating revenue profit margin was 5.68%, an increase of 0.44 percentage points year-on-year. From January to September 2026, profits in the electronics industry, driven by artificial intelligence, doubled, and profits in upstream raw material industries grew significantly, greatly promoting the overall improvement of industry profits. However, the auto industry faced dual pressures of rising costs and weak demand, resulting in poor profitability. From January to September 2026, auto production was 23.37 million units, down 4% year-on-year; revenue was 804.35 billion yuan, up 2.6%; costs were 716.27 billion yuan, up 3.8%; profits were 26.75 billion yuan, down 23%; and the sales profit margin was 3.3%. Among them, in September, auto production was 3.06 million units; sales revenue was 103.74 billion yuan, up 0.6%; costs were 92.57 billion yuan, up 2.5%; profits were 1.42 billion yuan, down 68%; and the sales profit margin was 1.4%, at a four-year low.
In 2026, various regions vigorously promoted the implementation of the "Two New" policies, gradually and effectively releasing domestic demand vitality. However, the improvement in efficiency in the auto industry significantly lagged behind other consumer goods. As the national anti-involution work continues to advance, the auto industry is squeezed by upstream sectors, with significant cost increases. Soaring oil prices and surging profits in non-ferrous metals and semiconductors have led to serious wait-and-see attitudes among terminal users when buying cars, resulting in continuous high operational pressure for automakers.
4. China's Auto Exports Reached 8.63 Million Units from January to September 2026
From January to September 2026, China's auto exports reached 8.63 million units, a year-on-year growth of 52%. In September, China's auto exports were 1.18 million units, up 55% year-on-year and 13% month-on-month, indicating a relatively strong overall trend in the auto market. The main growth drivers this year are still attributed to high oil prices, improved competitiveness of Chinese products, and continuous growth in Global South markets. Exports to Mexico and the Philippines saw a significant month-on-month decline in September. From January to September 2026, Anhui's auto export growth was 115%, with Zhejiang ranking second. Shanghai enterprises had higher average export prices.
The top 10 countries for China's total auto exports in September 2026 were: Russia (112,962 units), UK (58,740 units), Brazil (58,725 units), Australia (46,559 units), Belgium (45,369 units), Thailand (39,323 units), UAE (39,120 units), Mexico (38,962 units), Italy (37,731 units), and Spain (34,051 units). The top five in terms of incremental growth compared to the same period were: Russia (43,836 units), Brazil (34,423 units), UK (31,173 units), Thailand (25,615 units), and Italy (25,024 units). Exports to Russia recovered significantly from January to September 2026. The top 10 countries for cumulative total vehicle exports from January to September 2026 were: Russia (752,602 units), Brazil (539,675 units), UK (424,173 units), Australia (373,674 units), Belgium (367,879 units), Mexico (361,518 units), Italy (245,836 units), UAE (237,970 units), Philippines (235,933 units), and Thailand (224,121 units). The top five in terms of incremental growth compared to the same period were: Russia (394,809 units), Brazil (321,527 units), UK (199,582 units), Australia (150,298 units), and Italy (136,011 units).
Full-year customs data this year shows differentiated growth trends for various vehicle types: passenger cars generally performed strongly, while trucks performed poorly in September. Pickup truck growth improved in September, heavy truck exports declined from high levels, and other truck markets performed strongly. Large and medium-sized buses performed weakly, while the export share of light buses rebounded to 63% in September.
In September 2026, China's new energy vehicle exports were 612,000 units, up 104% year-on-year; cumulative new energy vehicle exports from January to September were 4.07 million units, up 75% year-on-year, showing very good performance, with a 23% month-on-month increase in new energy vehicle exports in September.
The top 10 countries for China's total new energy vehicle exports in September 2026 were: Belgium (43,675 units), UK (43,548 units), Brazil (42,130 units), Thailand (37,714 units), Australia (33,437 units), Germany (26,465 units), Spain (24,711 units), Italy (24,134 units), Russia (17,520 units), and Philippines (17,027 units). The top five in terms of incremental growth compared to the same period were: Brazil (30,759 units), Thailand (25,201 units), Australia (24,072 units), UK (24,027 units), and Belgium (22,806 units). The top 10 countries for China's total new energy vehicle exports from January to September 2026 were: Brazil (379,234 units), Belgium (351,032 units), UK (313,638 units), Australia (270,577 units), Thailand (213,455 units), Philippines (205,197 units), Germany (142,382 units), Italy (133,234 units), Spain (131,120 units), and South Korea (125,164 units). The top five in terms of incremental growth compared to the same period were: Brazil (237,917 units), Australia (161,462 units), UK (160,373 units), Belgium (127,500 units), and Thailand (116,136 units).
There is significant differentiation in the export of various new energy vehicles: Pure electric passenger car exports from January to September 2026 were mainly to: Belgium (245,860 units), Thailand (198,551 units), Brazil (196,069 units), Australia (192,382 units), and UK (159,580 units). The main destinations for plug-in hybrid passenger car exports from January to September 2026 were: Brazil (181,165 units), UK (151,559 units), Belgium (101,962 units), Italy (84,119 units), and UAE (76,601 units). The main destinations for cumulative plug-in hybrid truck exports in 2026 were: Australia (17,346 units), Argentina (3,849 units), Mexico (2,754 units), Pakistan (2,500 units), Chile (2,220 units), and New Zealand (2,064 units). The main destinations for pure electric bus exports for the full year were: Nepal (2,325 units), Ethiopia (1,236 units), Pakistan (829 units), and Israel (739 units).
5. China's Auto Imports Were 290,000 Units from January to September 2026
In September 2026, imported cars totaled 21,000 units, down 49% year-on-year and 6% month-on-month. From January to September 2026, auto imports were 290,000 units, down 20% year-on-year. This year, passenger cars accounted for over 99% of the auto import structure, holding an absolutely dominant position. If pickups included in light trucks are considered, the proportion of passenger cars is even higher. From January to September 2026, imported hybrids grew 15%, showing good performance, while pure electric passenger cars decreased 27%, and plug-in hybrids decreased 54%, indicating weak performance for imported new energy passenger cars. Imported passenger car displacements were concentrated in gasoline models under 2 liters. Last year, 3-4 liter models showed better resistance to decline, while this year, 1.5-2 liter models performed relatively better.
Pressure on the decline of imported cars remained high in September. The top 10 countries for imports in September 2026 were: Japan (7,399 units), Germany (7,255 units), UK (2,488 units), Slovakia (1,418 units), Mexico (818 units), USA (791 units), Austria (355 units), Belgium (112 units), South Korea (95 units), and Italy (90 units). The top five in terms of incremental growth compared to the same period were: Mexico (307 units), Austria (107 units), Belgium (42 units), South Korea (41 units), and France (16 units). The top 10 countries for imports from January to September 2026 were: Japan (136,652 units), Germany (66,438 units), USA (28,350 units), Slovakia (20,422 units), UK (18,803 units), Mexico (4,974 units), Austria (4,193 units), Thailand (2,270 units), Italy (786 units), and South Korea (760 units). The top five in terms of incremental growth compared to the same period were: Thailand (2,027 units), Austria (1,948 units), Mexico (1,576 units), China (540 units), and South Africa (373 units).
From January to September this year, imported car retail sales were 250,000 units, down 32%, showing poor performance. In September, it dropped to 27,000 units, down 38% year-on-year, showing very poor performance, with significant future pressure. Domestic demand for domestically produced and imported luxury cars is generally weak, with significant pressure in luxury car markets in regions such as Beijing, Shanghai, Hangzhou, Chengdu, and Shenzhen. Demand in northern and central-western oil-producing regions such as Xinjiang and Shandong is relatively strong this year.
6. China's Sales Accounted for 32% of World Auto Share from January to September 2026
According to statistics from the International Organization of Motor Vehicle Manufacturers, global auto production continues to grow, reaching 96.38 million units in 2025, a 5% increase from 91.77 million units in 2024, with China accounting for 35.4% of world production share. Global auto sales continue to grow, reaching 96.89 million units in 2025, a 6% increase, with China accounting for 35.4% of world sales share. From January to September 2026, cumulative world auto sales were 72.52 million units, up 3% year-on-year; among them, single-month sales in September were 8.74 million units, up only 2% year-on-year and 12.4% month-on-month, indicating weak growth momentum in the global auto market.
Cumulative global auto sales from January to September 2026 were 72.52 million units. By country, China's sales were 23.27 million units, with a share of 32.1%, a significant drop from 35.4% in 2025; US sales were 12.30 million units, with a share of 17.0%, a slight decline; India performed brightly, with its share rising to 6.7%, becoming a growth highlight. Looking at historical share changes, China's global share continued to rise from 2022 to 2025, reaching a phased high in 2025. The shares of major European countries overall remained stable with slight declines, while emerging markets like Brazil and Russia maintained stable shares. The decline in China's market sales in the first nine months of 2026 was the core reason for the change in global share. The rapid growth of emerging markets like India partially offset the growth pressure in the Chinese and US markets, supporting the global auto market to maintain slight positive growth.
With the rise of the East and the decline of the West, except for Toyota, Hyundai-Kia, Suzuki, and Tata, other international brands saw a significant decline in share in 2026. Compared to 2019, Chinese domestic brands have comprehensively increased their world share this year. Geely, BYD, Chery, SAIC, Changan, and other domestic brands performed strongly. The trend of global electrification has also led to the gradual weakening of some established international automakers. Except for factors promoting better performance in the Indian market for brands like Suzuki, other international brands saw a comprehensive and significant decline in share.
7. China's New Energy Passenger Cars Accounted for 63% of World New Energy Vehicles from January to September 2026
From January to September 2026, world new energy passenger cars reached 18.38 million units, up 15% year-on-year, among which September new energy vehicle sales were 2.65 million units, up 16% year-on-year and 18% month-on-month, with the growth rate returning to historical normal levels. The new energy vehicle share from January to September 2026 reached 25.3%, among which pure electric vehicles accounted for 17.8%, and plug-in hybrids accounted for 7.6%. The hybrid share reached 8%, showing excellent performance.
European new energy passenger car sales in 2025 were 3.86 million units, an incremental increase of 960,000 units from the same period last year, up 33%. Preliminary statistics show European new energy passenger car sales in September were 544,000 units, up 38% year-on-year, and 3.68 million units from January to September 2026, up 35% year-on-year. Due to price increases caused by high tariffs and the cancellation of new energy subsidies, US new energy vehicle sales in September 2026 were 120,000 units, down 44% year-on-year, and 950,000 units from January to September, down 32%.
The global new energy vehicle penetration rate shows a trend of rapid improvement, reaching 13.1% in 2022, 15.9% in 2023, 19.5% in 2024, and 23.6% in 2025. The world new energy vehicle penetration rate in 2026 was 25.3%, among which Germany reached 34.2%, Norway reached 83%, UK 36.7%, while the US had only 7%, and Japan only 4%, indicating extremely obvious imbalance in global new energy development.
From January to September 2026, China's new energy passenger cars accounted for 63% of the world share, reaching a good level of 65.5% in the third quarter. For pure electric: China's share of the world pure electric vehicle market from January to September 2026 was 59%. Performance at the beginning of the year was temporarily poor due to Spring Festival factors, reaching 62% in the third quarter. For plug-in hybrids: China's share of the world plug-in hybrid market from January to September 2026 reached a high level of 71%, reaching 74% in the third quarter, showing super strong performance in the world plug-in hybrid market.
In 2025, the overseas sales share of domestic new energy passenger cars reached 15.8%, an increase of 6.2 percentage points. In 2026, the overseas sales share of domestic new energy passenger cars increased significantly, reaching 27.8% in September, a further substantial leap of 12 percentage points.