$NVIDIA(NVDA.US) Stock Analysis: Record Growth vs. Leadership Chaos
Nvidia is experiencing a historic disconnect between its explosive business fundamentals and plummeting share price.
The Bull Case (Fundamentals)
• Blowout Q3: Revenue surged 103% YoY to $115.8B, crushing estimates. Net income doubled to $65.3B with a massive 56% profit margin.
• Strong Guidance: Interim CEO Colette Kress projected $130B in Q4 revenue and raised FY28 growth guidance to 75%, proving AI infrastructure demand remains insatiable.
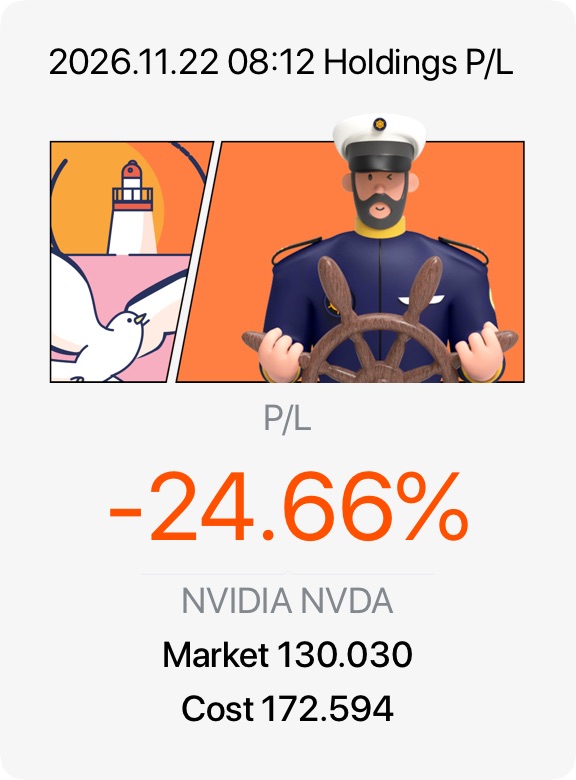
• Deep Value: Trading around $125.53—down ~46% from its October peak—NVDA sits at a rare ~8.4x forward P/E, backed by a massive $227B+ buyback authorization.
The Bear Case (Headwinds)
• Leadership Vacuum: Co-founder Jensen Huang resigned on Nov. 12 amid personal conduct and national security probes, stripping the stock of its “founder premium”.
• Regulatory Scrutiny: Reports of an SEC accounting probe and tighter U.S. export controls have sparked a 7-week losing streak—NVDA’s longest since 2008.
• Rising Rivals: Custom chips and competition from AMD and Google continue to pressure long-term market share.
Wall Street Consensus
Despite the sell-off, analysts remain overwhelmingly bullish with a consensus Buy rating (30 Buy, 13 Hold, 1 Sell) and an average price target of $232.59 (+85% upside).
Bottom Line: Nvidia is a cash-printing machine priced for a crisis. While fundamentals scream bargain, expect heavy volatility until a permanent CEO is named and regulatory dust settles.