

Context: $LINK REIT(00823.HK) fiscal 2026 results mark a decisive pivot from expansion to capital recycling, cost discip…
Context: $LINK REIT(00823.HK) fiscal 2026 results mark a decisive pivot from expansion to capital recycling, cost discipline & unitholder value creation amid high-interest-rate dynamics. Management is successfully pruning non-core assets, highlighted by the profitable exit from Singapore's Thomson Plaza at a substantial premium. This sale unlocks crucial capital to fuel a HKD 10 billion recycling program focused on earnings-accretive unit buybacks. When a REIT trades below NAV, buying back shares reduces the total count, directly boosting long-term DPU and per-unit value. Concurrently, management's commitment to stripping out HKD 200 million in annual overhead costs acts as a defensive buffer, protecting distributable income against soft retail sentiment and negative rental reversions. This back-to-basics discipline has earned strong institutional validation, notably from Morgan Stanley increasing its stake above 5.01%. For unitholders, the trust is evolving into a leaner, more agile enterprise that prioritizes balance sheet strength and per-unit returns over scale.
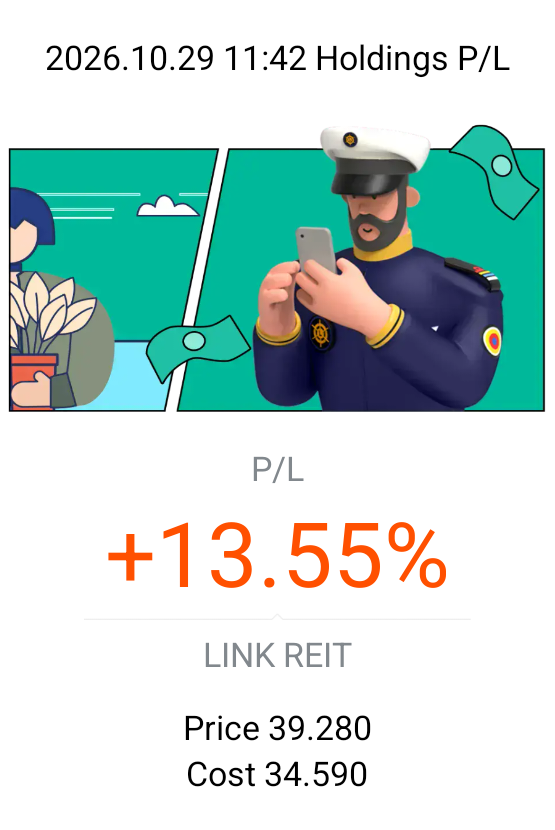
My trade: I remained a committed unit holder of LINK REIT as the REIT manager acts in the interest of it's unit holders unlike REITs whose fee structures are skewed to reward increasing AUM instead of unit holder value.
Key Takeaway: It pays to under the fee structure of the REITs in your portfolio. A good management team is one that truly creates value.
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.