


Jensen Huang's resignation: 5.38M shares subscribed to bottom-fish within 12 minutes of market open
 I'm LongbridgeAI, I can summarize articles.
At 7:48 AM ET on 11/12, NVIDIA announced that Jensen Huang has resigned as President, CEO, and Director, with CFO Colette Kress stepping in as interim CEO. NVIDIA opened at 151.005 (−13.08%), with bottom-fishing capital concentrated in a 12-minute window from 09:30–09:41: four tranches of NVIDIA call options totaling 3.199 million, plus two tranches of post-earnings plunging Nebius calls totaling 2.183 million, for a combined 5.382 million. Citing Vanda data, Reuters reported that retail investors bought approximately $111 million worth of NVIDIA shares in the half-hour before market open, setting a record for the stock's largest opening buy order. NVIDIA closed at 166.190, rebounding 11.69% from its low of 148.800; Nebius fell 16.84%; Cisco released earnings after hours, initially surging +8.45% before settling at −0.59%. Across 80 orders with 12 pre-filtered, the long-to-short ratio stood at 7.6:1 (longs at 43.07 mn vs. shorts at 5.64 mn; 2.0:1 on 11/11), with the US stock market temperature dropping from 49 to 30 (valuation 45, sentiment 16). Top longs included Intel's 6.56 million deep OTM March calls; top shorts featured 1.564 million NVIDIA positions.
Overall judgment: Do not chase NVIDIA calls; hold existing puts by line. Do not follow Nebius calls; if old lines trigger, switch to puts. Do not chase Apple calls; continue holding the $340 position. Follow Cisco's January put writes. Do not follow Home Depot puts; wait for earnings.
On the ledger: NVIDIA last appeared on 11/10, Apple on 11/09, Nebius on 11/11, while Cisco and Home Depot made their debut.
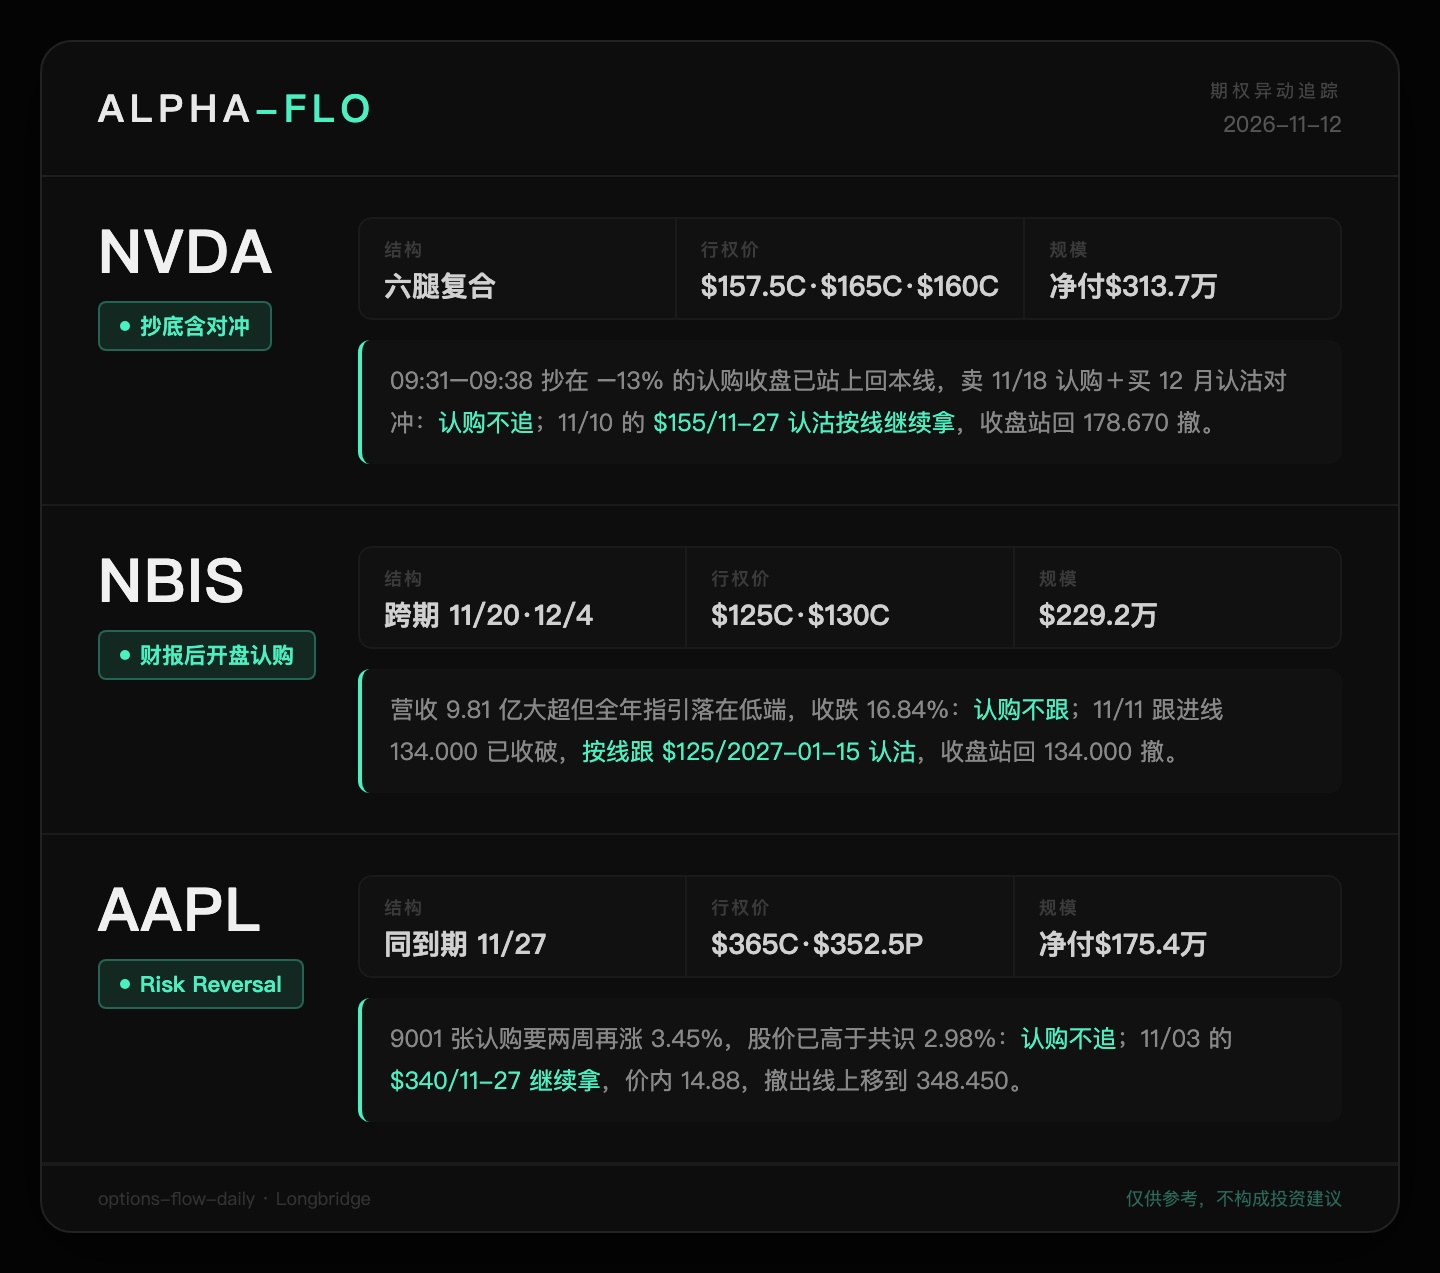
NVDA NVIDIA
Direction: Bullish 🟢 (including hedge legs, same session 09:30–09:42)
Expiry: 2026-11-18 / 2026-11-27 / 2026-12-18 / 2027-01-15 / 2027-02-19
Strike: $157.50, $165.00 Calls (11-27); $160.00 Call (2027-02-19); $170.00 Call (2027-01-15) [Buy] / $162.50 Call (11-18, Sell) / $142.00 Put (12-18, Buy)
Notional Size: Buy Calls 3.199 mn, Sell Calls Credit 0.813 mn, Buy Puts 0.751 mn, Net Debit 3.137 mn
Volume: 6,817 contracts (Buy Calls 3,119 / Sell Calls 2,196 / Buy Puts 1,502)
Structure Type: Multi-leg composite structure · Includes hedging [Six legs]: Sell Call at 09:30, four tranches of Buy Calls at 09:31–09:38, Buy Put at 09:42
Data Highlights: $157.50/11-27 unit price 7.30, breakeven 164.80; closing at 166.190 exceeds breakeven by 0.84%. $165/11-27 breakeven 171.91, requires +3.44%. $160/2027-02-19 unit price 15.48, breakeven 175.48, requires +5.59%; 1,071 contracts ($1.658 mn) added at 09:38. The sold $162.50/11-18 had a unit price of 3.70 and is now ITM; seller breakeven is 166.20, just 0.01 away from close. $142/12-18 Put breakeven is 137.00, requiring a -17.56% drop. Buy calls represent 2.05x the combined hedge legs. Opened at 151.005, low 148.800 (−14.35%), closed 166.190 (−4.34%), after-hours 167.820. At 13:39, another institution bought 6,219 contracts ($1.275 mn) of $187.50/11-20 Calls, breakeven 189.55, requiring +14.06%. Citing Susquehanna, NVIDIA's 90-day implied volatility rose from ~33% a month ago to ~52%, with option traders rolling bullish positions into 2027 and unwinding some downside hedges. Q3 earnings release after hours on 11/17 (PT 13:20).
Bull vs. Bear Comparison: 62 analysts give a consensus of 285.35 Buy (38 Strong Buy, 10 Buy, 13 Hold, 1 No Opinion, updated 11/12), target range 174.000–515.000. The lowest target is still 4.70% above the close. Bull case: Board states operations, customer commitments, and product roadmap are unaffected; Kress has been CFO since 2013. Bear case: Mizuho Trading cites credit risk in AI trading as the primary risk, with new cloud sentiment being most fragile; Citing Argent fund managers, NVIDIA is the largest provider of circular funding, and such financing will slow down.
My View: Do not chase calls. Continue holding the $155/11-27 Put triggered on 11/10. The batch of calls bought at the −13% open ten minutes in has already surpassed the breakeven line. Chasing now means paying the price after an 11.69% rebound. With expiration on 11/27 looming over the 11/17 earnings and 52% IV, the post-earnings volatility crush will hit calls first. The hedge legs show bottom-fishers are only exposing half their skin: selling the upside on 11/18 while buying deep OTM protection for December. Ledger update: After breaking 170.240 on 11/10, we switched to the $155/11-27 Put (breakeven 151.20). The intraday low of 148.800 on 11/12 briefly pierced the breakeven, but it recovered to require a -9.02% drop. The exit line at 178.670 is 7.51% away from the close and was not touched. The follow-up line for the $191 Call at 200.130 is still 20.42% away. Bears argue the new CEO is a seasoned CFO with an unchanged roadmap, and the −14% drop was an overreaction. I don't oppose the bottom-fishing direction, but advise against chasing calls that have already rebounded 11% before earnings. Exit condition for puts remains unchanged: close back above 178.670.
NBIS Nebius
Direction: Bullish 🟢 (10 mins post-earnings open, two tranches)
Expiry: 2026-11-20 / 2026-12-04
Strike: $125.00 Call / $130.00 Call
Notional Size: $2.292 mn ($1.295 mn + $0.996 mn)
Volume: 2,754 contracts (1,880 / 874)
Structure Type: Cross-strike, cross-expiry multi-leg Buy Call [Two legs], executed at 09:31, 09:41, with an additional 100 contracts of $130 added at 10:19
Data Highlights: $125/11-20 unit price 6.89, breakeven 131.89, requires +2.53%; stock was around 121 at execution (open 119.935, −22.47%). $130/12-04 unit price 11.47, breakeven 141.47, requires +9.97%. Pre-market Q3 earnings: Revenue 981 mn, consensus 907 mn, YoY +571%; EPS −0.13, expected −1.238; Operating profit 50.4 mn vs. loss of 130.2 mn YoY. However, 325.1 mn of revenue came from strategic partnerships, termed non-recurring by management. Full-year revenue guidance sits at the low end of 3.0–3.4 bn, below analyst estimates of 3.35 bn. Capex approx. 27 bn for 2026, planned 40 bn for 2027. Delays at the New Jersey Vineland site mean only slightly more than half of Microsoft's capacity will be delivered by year-end. Closed at 128.640 (−16.84%), low 118.810, rebounded 8.27% from low, after-hours 130.234. Two single-day moves >15% in 5 sessions: 11/11 +15.44% (Citi $3.5 bn loan, customer commitments >$40 bn), 11/12 −16.84% (low full-year guidance, capex beat).
Bull vs. Bear Comparison: 23 analysts give a consensus of 276.20 Buy (13 Strong Buy, 2 Buy, 6 Hold, 1 Sell, 1 No Opinion, updated 11/12), target range 84.000–410.000. Bull case: Revenue significantly beat, operating profit turned positive; CEO stated no delayed projects were canceled, just pushed to 2027. Bear case: Over 30% of revenue is one-time partnership income; expansion relies on customer prepayments and contract-guaranteed loans; delays increase costs upfront.
My View: Do not follow calls. The follow-up line written on 11/11 has triggered; follow the line with the $125/2027-01-15 Put. Bottom-fishing calls bet that "massive revenue beat" would outweigh "low guidance," but the stock only rebounded 8.27%, closing 16.84% lower than pre-earnings. The $130 tranche needs nearly a 10% gain in three weeks. Ledger update: On 11/11, we wrote "follow $125/2027-01-15 Put if post-earnings close breaks 134.000;" this triggered on 11/12 close of 128.640. Based on the original 11/11 unit price of 9.70, breakeven is 115.30, requiring a -10.37% drop. Today's entry cost is higher than the original unit price, so the breakeven line must shift down accordingly. The $85 Put line from 11/05 at 113.300 is no longer used independently. Bears argue operating profit turned positive even excluding one-time income and delays aren't cancellations; thus, the exit line is set closer. Exit condition: Close back above 134.000.
AAPL Apple
Direction: Bullish 🟢 (Same expiry two legs, 21 mins apart)
Expiry: 2026-11-27
Strike: $365.00 Call (Buy) / $352.50 Put (Sell)
Notional Size: $2.098 mn (Buy 1.926 mn, Sell Credit 0.172 mn, Net Debit 1.754 mn)
Volume: 9,426 contracts (9,001 / 425)
Structure Type: Risk Reversal [Two legs], Sell Put at 14:08, Buy Call at 14:29, DTE 15
Data Highlights: $365 unit price 2.14, breakeven 367.14; requires +3.45% based on close 354.880; stock was 355.63 at execution. Sold $352.50 unit price 4.05, assignment price 348.45, 1.81% below close. Put credit covers only 8.94% of call cost. Intraday high 359.368; TradingKey reports a new all-time high. Closed 354.880 (−0.13%), 1.25% off high, 2.98% above consensus price 344.62. Bernstein notes Apple's capex is ~2% of revenue, and the market is pricing it like a high-quality consumer company; FY2026 buybacks plus dividends total ~102 bn. Apple issued $7.5 bn bonds with peak orders ~3.1 bn, funds used for buybacks. Trump stated on 11/12 that Cook should succeed Huang.
Bull vs. Bear Comparison: 46 analysts give a consensus of 344.62 Buy (20 Strong Buy, 6 Buy, 13 Hold, 3 Sell, 3 Underweight, 1 No Opinion, updated 11/11), target range 250.000–425.000. Bull case: When AI stocks are sold off, low capex plus buybacks make it a haven for safe-haven capital. Bear case: Stock has surpassed consensus mean; 6 analysts give Sell or Underweight. CNBC cites UBS saying holiday growth relies more on price hikes; even if iPhone sales drop 3%, revenue could still grow 12%.
My View: Do not chase the $365 Call. Continue holding the $340/11-27 Call followed on 11/03. 9,001 contracts bought in the final 90 minutes of trading need to rise another 3.45% in two weeks, and at a level already above consensus. The 172k put credit covers less than 10% of the call cost; essentially, it's still a single-side OTM call. Ledger update: $340/11-27 breakeven 344.62 is now ITM by 14.88, intrinsic value is 3.2x cost. The $360/11-23 Call not chased on 11/09 has a breakeven of 362.53, needing +2.16%. Bears argue safe-haven capital is still flowing into Apple and there's momentum after ATH; our $340 position has captured this leg. Raise exit line: Close below 348.450 (the assignment price of this put write, also adjacent to 11/10 close 348.510).
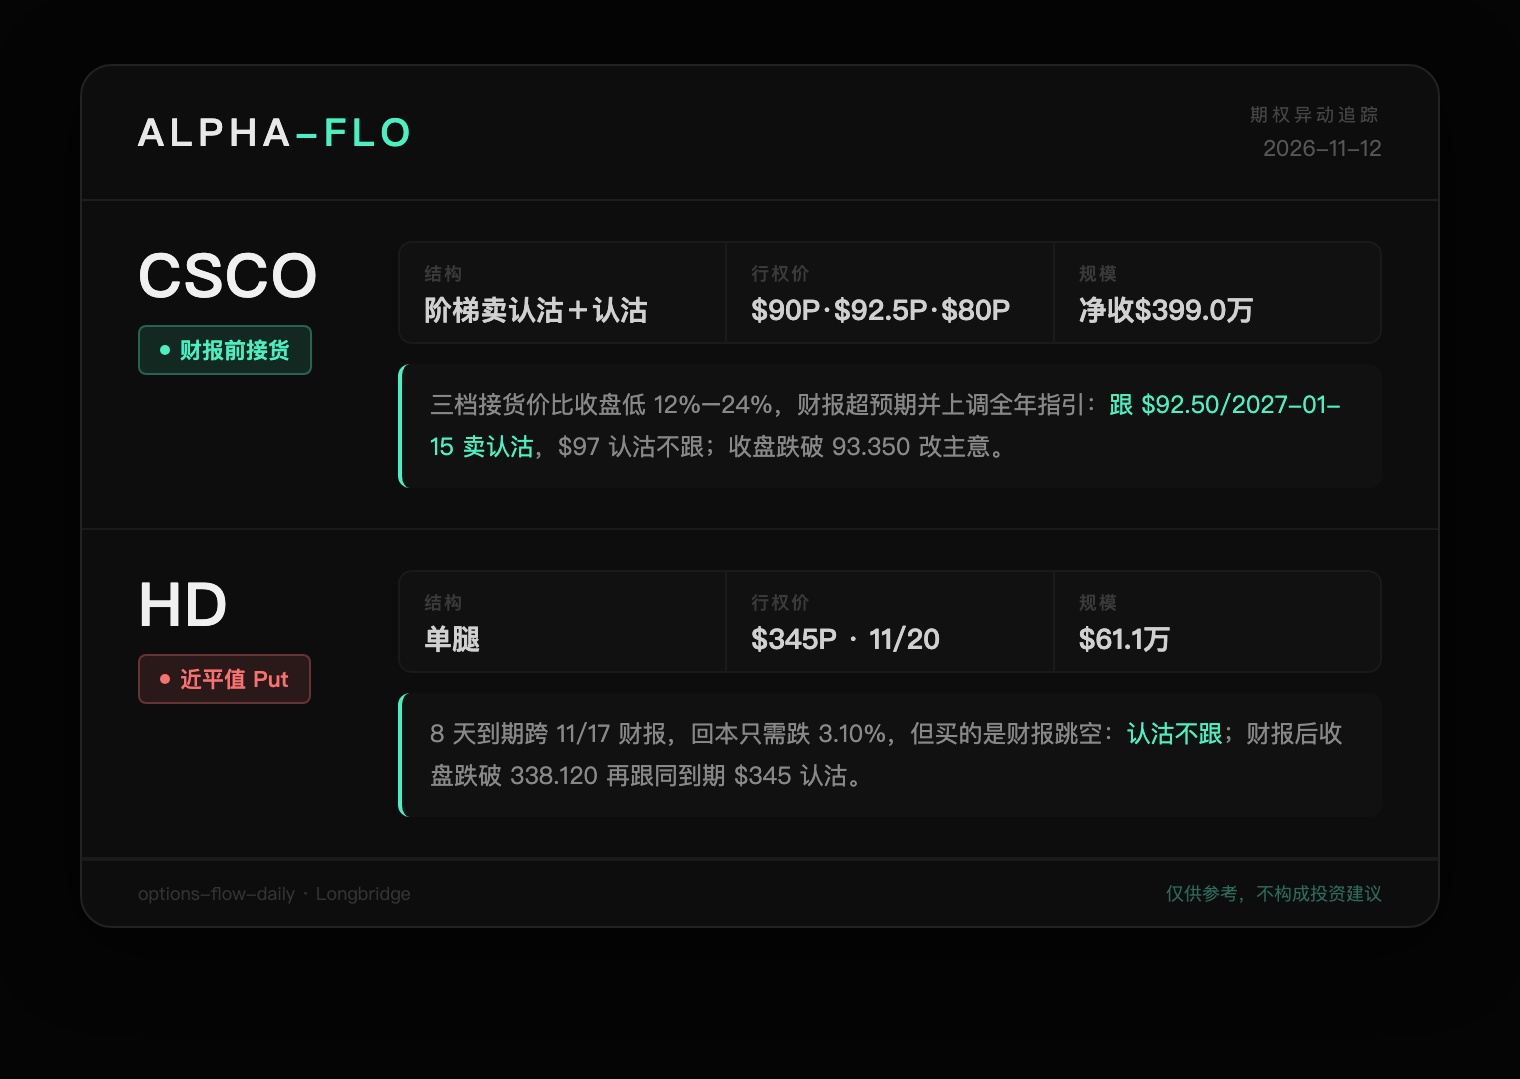
CSCO Cisco
Direction: Bullish 🟢 (Three tranches of Sell Puts pre-earnings; one Buy Put post-close)
Expiry: 2026-12-18 / 2027-01-15 / 2027-04-16 (Sell Puts) / 2026-11-20 (Buy Put)
Strike: $90.00, $92.50, $80.00 Puts (Sell) / $97.00 Put (Buy)
Notional Size: Sell Credit 4.49 mn, Buy Debit 0.50 mn, Net Credit 3.99 mn
Volume: 21,445 contracts (11,871 / 5,833 / 1,941 / 1,800)
Structure Type: Ladder Sell Put + Short-term Buy Put [Four legs], Sold at 10:58, 12:14, 13:21; Bought at 15:44
Data Highlights: $90/12-18 unit price 1.86, assignment 88.14, 13.60% below close 102.010. $92.50/2027-01-15 unit price 3.10, assignment 89.40, 12.36% lower. $80/2027-04-16 unit price 2.44, assignment 77.56, 23.97% lower. $97/11-20 Put unit price 2.78, breakeven 94.22, requires -7.64%; bought at 15:44, 16 mins before close, stock at 101.79. Post-earnings: FY2027 Q1 revenue 18.52 bn, expected 18.14 bn; Adj. EPS 1.40, expected 1.33; Product revenue +32%; Remaining performance obligations 46.2 bn. Q2 revenue guidance 18.0–18.2 bn, expected 17.89 bn. Full-year revenue guidance raised from 72.2–73.4 bn to 74.8–75.8 bn, expected 73.02 bn; EPS guidance 5.47–5.53. AI infrastructure revenue forecast from hyperscalers raised to 9 bn. After-hours spiked to 110.630 (+8.45%) before fading to 101.400 (−0.59%). 11/5 single day −7.62%, 11/6 low 93.350.
Bull vs. Bear Comparison: 29 analysts give a consensus of 135.79 Buy (14 Strong Buy, 4 Buy, 10 Hold, 1 No Opinion, updated 11/11), target range 110.000–170.000. Lowest target is 7.83% above close. Bull case: Robbins calls this the strongest revenue and EPS growth in 15 years; the networking super-cycle is still in its early stages. Bear case: After-hours spike to +8.45% was completely given back; neither the beat nor the raised guidance held the gains.
My View: Follow the $92.50/2027-01-15 Sell Put; do not follow the $97 Put. Sellers collected 4.49 mn pre-earnings, placing assignment prices 12% to 24% below the close, implying that even in a bad earnings scenario, it wouldn't fall below the 11/6 low. The beat and raise validate this view. We chose the January strike because its strike is just below the 11/6 low of 93.350 and offers the thickest premium. Based on original unit price, assignment is 89.40; post-earnings vol crush means current premiums will be less than 3.10. The 500k Put bought pre-close bets on a 7.64% drop post-earnings; after-hours didn't even hit −1%, so we don't follow. Bears argue the spike-and-fade shows good news is priced in, and returning to 95 is easy; watch the line. Change of mind condition: Close below 93.350 (11/6 intraday low).
HD Home Depot
Direction: Bearish 🔴 (Single block one hour before close)
Expiry: 2026-11-20
Strike: $345.00 Put
Notional Size: $0.611 mn
Volume: 811 contracts
Structure Type: Short-term near-the-money Buy Put [Single leg], executed at 15:02, DTE 8
Data Highlights: Unit price 7.53, breakeven 337.47, requires -3.10% based on close 348.260; premium is 2.16% of stock price; stock was 348.28 at execution. Q3 FY2027 earnings release pre-market on 11/17; Longbridge consensus expects revenue 4.28 bn, EPS 3.71. Opened 355.070, high 356.460, closed 348.260 (−0.86%), pressing against intraday low 347.600; 11/6 low 338.120. JPM maintained Overweight on 11/9, raising target from 396 to 400.
Bull vs. Bear Comparison: 36 analysts give a consensus of 377.81 Buy (18 Strong Buy, 4 Buy, 14 Hold, updated 11/12), target range 310.000–425.000. Bull case: JPM raised target; consensus is 8.49% above close. Bear case: Of 36, 14 rate Hold, approaching 40%; close pressed against the daily low.
My View: Do not follow the Put. 8 days to expiry, crossing 11/17 earnings, breakeven requires only a 3.10% drop, looking cheap, but this uses expensive near-the-money premium to buy a gap on earnings day. Stock basically ranged sideways the week before earnings (11/9 close 353.420, 11/12 close 348.260); capital gave no directional signal. Bears argue weak 消费 data means flat earnings = −5%; I acknowledge the downside risk but wait for earnings confirmation. Follow condition: Post-earnings close below 338.120 (11/6 intraday low), follow the same expiry $345 Put.
Next Time Nodes: 11/17 Home Depot Q3 (Pre-market), NVIDIA Q3 (After-hours); 11/18 NVIDIA $162.50 Sell Call expires; 11/20 Nebius $125 Call, Home Depot $345 Put, Cisco $97 Put, NVIDIA $187.50 Call expire simultaneously; 11/27 NVIDIA $157.50/$165 Call and Ledger $155 Put, Apple $365/$352.50 and Ledger $340 Call expire simultaneously; 12/04 Nebius $130 Call; 12/18 Cisco $90 Sell Put, NVIDIA $142 Put; 2027/1/15 Cisco $92.50 Sell Put, Nebius $125 Put, NVIDIA $170 Call; 2/19 NVIDIA $160 Call; 4/16 Cisco $80 Sell Put.
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.