
$Mapletree Log Tr(M44U.SG)
Mapletree Logistics Trust: Is the Turnaround Taking Shape?
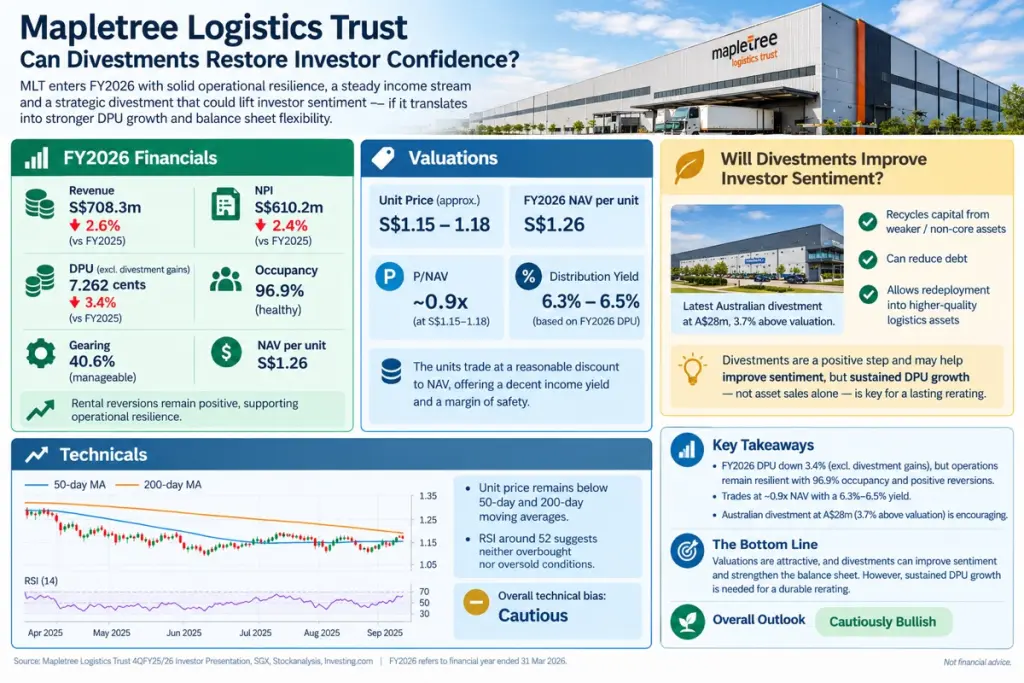
Mapletree Logistics Trust (MLT) had a softer FY2026, but the underlying business remains fairly steady. Revenue slipped 2.6% to S$708.3m, NPI fell 2.4% to S$610.2m, while DPU declined 3.4% to 7.262 cents, excluding divestment gains. Occupancy remains strong at 96.9%, rental reversions are positive and gearing at 40.6% remains manageable.
Valuation is becoming more interesting. At around S$1.15–1.18, MLT trades at roughly 0.9x NAV of S$1.26 per unit, with an estimated 6.3–6.5% distribution yield.
Technically, the picture remains mixed. The unit price is below its 50-day and 200-day moving averages, while an RSI around 52 suggests the counter is neither overbought nor oversold.
The Australian divestment at A$28m, 3.7% above valuation, is a constructive development. Recycling weaker or non-core assets could strengthen the balance sheet and free up capital for higher-quality logistics opportunities.
The key question now is whether asset recycling can translate into stronger DPU growth and renewed investor confidence. Divestments may help, but the longer-term catalyst remains sustainable earnings and distribution growth.
Not financial advice.