

01810

Dolphin Research Daily | ANT Sapping Chip Stocks; AMD Sinks on Short Report; Curbs Cap BABA's 2027 Cloud Growth
 I'm LongbridgeAI, I can summarize articles.
It is Nov 20, 2026 (Singapore). Dolphin Research brings you a one-glance wrap of global markets.

What’s Trading: Anthropic opened 34% above IPO price and closed up 17%, with fully diluted market cap near $1.8tn, now 7th globally. The Nasdaq 100 swung from +2% intraday to close down over 2%, the S&P fell for a sixth straight day as money rotated out of semis into ANT.
AMD fell 7.7% after a short report from investigative outlet Hunterbrook; Nebius -9.4%. Alibaba Cloud accelerated to +53% YoY, but new compute export rules cut its 2027 cloud growth target to 30%–45%.
Macro Sentiment: Nov Philly Fed Manuf. Index printed 6.3, far below the 20 consensus, with price components still rising. Chicago Fed President Austan Goolsbee did not rule out a larger-than-usual hike next month; VIX jumped 15.8% to 28.4, gold -2.2%, and the DXY rose to its highest since Apr 2025.
Key Movers: ADR earnings diverged, PDD +11.0%, NetEase -11.4%. Cybersecurity rallied against the tape, Palo Alto +6.4%, Okta +5.7%. Lenovo beat on revenue but swung to a loss; its HK shares fell 5.5% yesterday.
Near-term Watch:
Today: Japan Oct CPI (07:30), China Nov LPR (09:15). Kuaishou, NetEase, Lenovo HK to be priced off earnings.
Next week: 11/24 Dell, Xiaomi earnings. 11/26 US Thanksgiving (market closed).
Dec 8–9: FOMC; Goolsbee says all options are on the table.

$Anthropic(ANT.US) , $NVIDIA(NVDA.US) , $AMD(AMD.US) , $Amazon(AMZN.US) , $Alphabet(GOOGL.US) , $Alibaba(BABA.US) , $BABA-W(09988.HK) , $Taiwan Semiconductor(TSM.US) , $Broadcom(AVGO.US) , $Micron Tech(MU.US) , $Marvell Tech(MRVL.US) , $Coreweave(CRWV.US) , $Nebius(NBIS.US) , $PDD(PDD.US) , $NetEase(NTES.US) , $NTES(09999.HK) , $LENOVO GROUP(00992.HK) , $S&P 500(.SPX.US) , $NASDAQ-100(.NDX.US) , $iShares Semiconductor ETF(SOXX.US) , $Hang Seng Index(00HSI.HK) , $Hang Seng TECH Index(STECH.HK)

1) ANT +17% Day One: ~$1.8tn fully diluted, 7th largest globally
Anthropic +17.1% (vs IPO) / Zoom -9.6% / AMZN -3.9% / GOOGL -3.5%
Debut: ANT opened at $111.50, +34.3% vs the $83 IPO, and hit $115.10 intraday. It broke below $100 within 30 minutes and closed near the day low at $97, still +17.1% vs IPO, then fell another ~2% after hours; turnover was 850mn shares, ~$87bn.
On ~13.2bn total shares outstanding, close implied ~$1.28tn. Fully diluted valuation was close to $1.8tn, behind AAPL, MSFT, NVDA, GOOGL, AMZN and SpaceX, ranking 7th globally, surpassing Saudi Aramco, AVGO and TSM.
Final prints: Greenshoe was fully exercised with primary shares; alongside a concurrent private placement, gross proceeds were near $120bn.
'Proxy' sold off: Zoom, long seen as a trading proxy for ANT exposure, was dumped after the open and fell 9.6%. AMZN and GOOGL faded with the tape, though GOOGL briefly rose 4%–5% early on positive chatter around the Gemini 4 Neon model.
Unlock cadence: ~15.5bn shares are locked up, 12x day-one float, to be stagger-released across 25 windows over one year, with the three largest waves in early Mar, mid-May and Nov 2027.
Dolphin take: On a 1–3Y view, a ~$1.5tn valuation looks defensible; above that, the risk-reward worsens.
The key issue is low earnings visibility: frontier model token pricing falls 45%–55% per year, and AI substitution of knowledge work shrinks the $40tn wage TAM. That said, remote-compute export limits are restraining open-source, likely supporting post-IPO sentiment longer; watch the big unlocks in Mar, May and Nov next year. (Original article)
2) S&P down 6 straight: ANT drains semis; AMD -7.7% on short report
Nebius -9.4% / AMD -7.7% / CoreWeave -6.1% / NVDA -3.3% / TSM -2.9%
MU -2.1% / MRVL -4.9% / AOI -3.3% / AVGO -2.1%
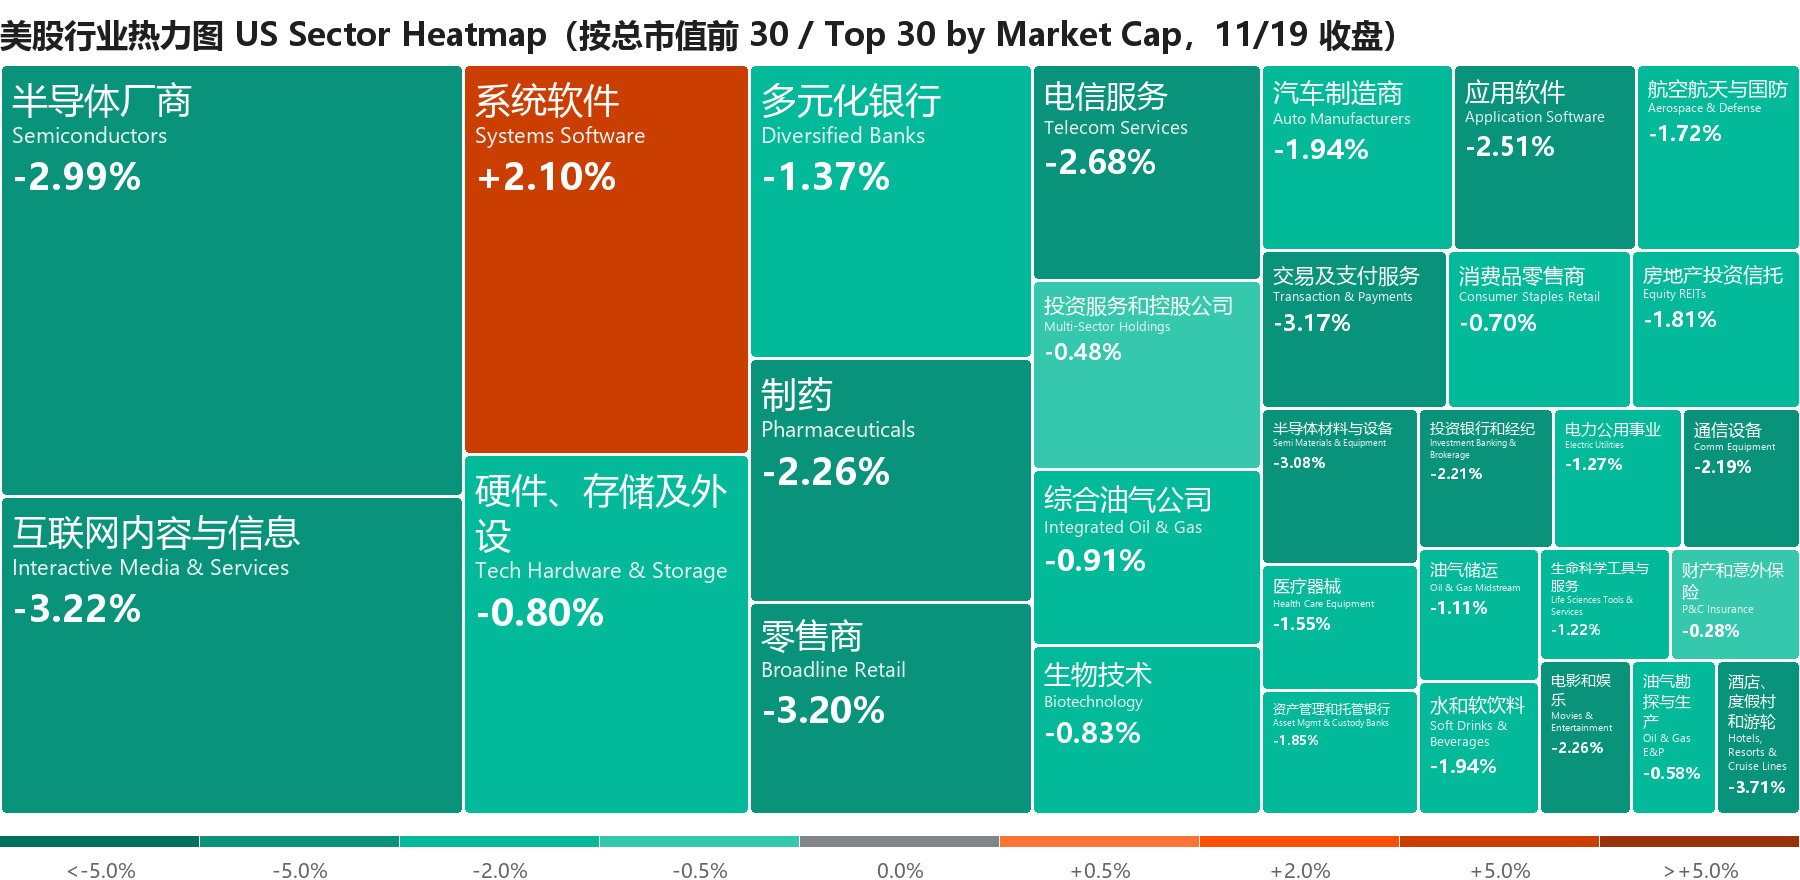
Rally faded: QQQ was up as much as 2.4% in the first 30 minutes and closed -2.2%. Semis reversed from +4.8% early to -2.7% at the close, and software opened +4% but finished -1%.
When Hunterbrook released its AMD short, the market was already rolling over. Less than five minutes after ANT opened, QQQ fell another 1.5% and then bled lower all day.
The S&P 500 fell 2.02%, its sixth straight decline, closing at the lowest since Apr 29. The Dow dropped 1,101pts, closing below 50k for the first time since Jun, and all 'Magnificent Seven' closed lower; the SOX fell 2.41% with 27 of 30 constituents down.
New-cloud names were hit hardest: CoreWeave and Nebius were up nearly double digits intraday but reversed to close at -6.1% and -9.4%. A CoreWeave cofounder disclosed buying $30mn of company bonds due 2031, but buying debt over equity failed to stem the slide.
Rotation: A Zeus Quanto PM said investors seeking the 'purest AI exposure' bought ANT, with some selling NVDA and other semis to fund it.
Goldman flow desk flagged steady institutional de-risking in Tech, with systematic strategies selling hard and retail now the marginal buyer. Historically, the S&P’s median Max drawdown in the Nov–Dec window is ~3%, with most gains skewed to after Dec 15.
BofA’s Nov Global Fund Manager Survey showed Tech overweights dropped from net 37% in Oct to net 12%, the biggest fall since Jun 2006, and 52% expect hyperscalers to announce capex cuts in the next six months.
AMD short: AMD was up 5% early but reversed after the report, down as much as 11% intraday; Hunterbrook Capital, affiliated with the outlet, was short AMD at publication.
The report alleges that after Inspur was added to the US Entity List in Mar 2025, at least six updated AMD firmware builds were integrated there. Firmware on AMD servers at related firms Kaytus (Singapore) and Aivres (US) matched Inspur’s by 99.94%; AMD’s site still lists Aivres as an Instinct AI server partner.
China exposure higher than NVDA: AMD invoiced $7.75bn to Mainland China and Hong Kong in 2025, 22.4% of revenue (NVDA ~9.1%), and $4.28bn to Singapore, 12.4%.
Rebuttal: The report concedes these ties are small relative to AMD’s scale and are insufficient proof of export-law violations. AMD said the piece mischaracterizes its biz and that it complies with US export controls.
NVDA six-day slide: Down 14.5% over six sessions, erasing $611bn of mkt cap. Per WSJ, Wall St. backers of NVDA’s $500bn AI financing plan have yet to deploy capital, and the first deal likely won’t close before 2027.
Bloomberg also reported Trump may allow Blackwell sales to China in 2–3 years when it is less cutting-edge, but no approval for near-term shipments.
Dolphin take: Regardless of confidence in the report, the market will question whether AMD has 'remote compute' risks similar to NVDA. If so, some capital may rotate to Anthropic, accelerating the drain on chip stocks.
3) Alibaba: AI Cloud +53%, but new rules cap 2027 cloud growth at 30%–45%
BABA -1.3% / Alibaba-SW 9988.HK
Solid quarter: For the Sep quarter, group revenue was RMB 271.5bn (+9.6% YoY), in line with the Street. Adj. EBITA was RMB 32.6bn, nearly 10% above consensus, with the beat led by Cloud.
AI cloud and compute revenue was RMB 61.0bn (+53% YoY vs +45% prior), with external customer revenue +64%. EBITA margin rose to 14.5%, up ~300bps QoQ, vs Street ~12%–12.5%.
Alibaba disclosed computing equipment revenue (incl. T-Head) for the first time at RMB 10bn this quarter. Mgmt cited a richer mix of high-GP products, global compute shortages enabling pricing, and scale effects as margin drivers.
Rule impact: Mgmt said US export curbs on compute will reduce capex, and initial 2027 cloud revenue growth target is 30%–45%, recovering to 50%+ by 2028 as domestic compute ramps. The 2030 target for $100bn external cloud revenue and 20%+ long-term margin stands, but CEO Eddie Wu noted the 20GW data center build by 2032 may be revised lower.
Post-2027, added AI chip capacity will be mainly in-house and prioritized for internal model training. T-Head’s next-gen GPU Zhenwu V900 will deliver 3x M890 compute and enter mass production in Q1 2027.
Spillovers: FT reported TSMC and Samsung have halted some processor shipments to China pending licenses. A-share AI chip designers nosedived yesterday while AI mfg. chain outperformed.
Dolphin take: No glaring weakness this quarter, but clouds loom ahead. Under the new rules, Alibaba’s compute capacity could undershoot plan by 19%–27% with the brunt in 2027; we estimate external cloud growth could slow from 50%+ to 20%–35% in 2027, below mgmt’s 30%–45%.
By SOTP, our neutral range is cut to $87–$139 (Cloud EV/S down to 2–4x from 5–6x). The stock is already below the lower bound, so downside looks limited, but domestic chip capacity ramp remains uncertain; conservative investors may wait for policy clarity. (First Take)(Earnings Review)(Call Transcript)

1) Philly Fed slumps; Fed hawks up the ante: larger-than-usual hike not ruled out
Data: Nov Philly Fed fell to 6.3, the lowest since May and well below estimates (20.0–23.2 across houses). New orders slipped into contraction while prices paid climbed to 58.2.
Initial jobless claims were 203k vs 197k est.; continuing claims rose 70k to 1.763mn, the highest since late Aug.
Pricing: After hawkish minutes, odds for a 25bp hike in Dec are ~90% and ~10% for 50bp; by the Jan meeting, the cumulative 50bp hike odds are ~80%.
Fed speak: Chicago Fed’s Austan Goolsbee said inflation prints remain elevated with little progress where improvement was expected. All options are on the table for Dec, including a larger-than-usual hike; he likened the AI boom to a 'python swallowing a pig', with DC buildouts, corporate capex and wealth-effect consumption potentially overheating growth.
Fed Vice Chair Jefferson said investment in data centers and advanced compute is pushing up inflation, and AI-driven productivity gains will lower prices only 'in the future'.
Rates and USD: The 10Y UST yield fell 1.4bps to 5.052%, down for a second day, offering little support to equities. DXY rose to 103.9, the highest since Apr 2025; CNH briefly weakened to 6.6999, the weakest since mid-Oct.
2) Higher-vol assets (11/19)
VIX +15.8% to 28.44: Nearly touched 29 intraday, closing at the highest since Mar 30; ANT’s listing did not soothe nerves.
COMEX gold -2.16% to $3,660.9: Spot gold fell 2.78% to $3,620 late NY; spot silver -4.86%. Deutsche Bank said selling has turned into indiscriminate de-grossing, driven by sharply lower inflation expectations amid hawkish Fed rhetoric; gold/copper shorts could add further.
Crude little changed: Two VLCCs hit mines in the Strait of Hormuz, sending oil up >1% intraday before giving back gains; Brent Jan settled at $91.98.
Bitcoin -1.9% to ~$61.8k: Risk appetite cooled, with no bounce.
3) Compute and storage pricing (11/20)
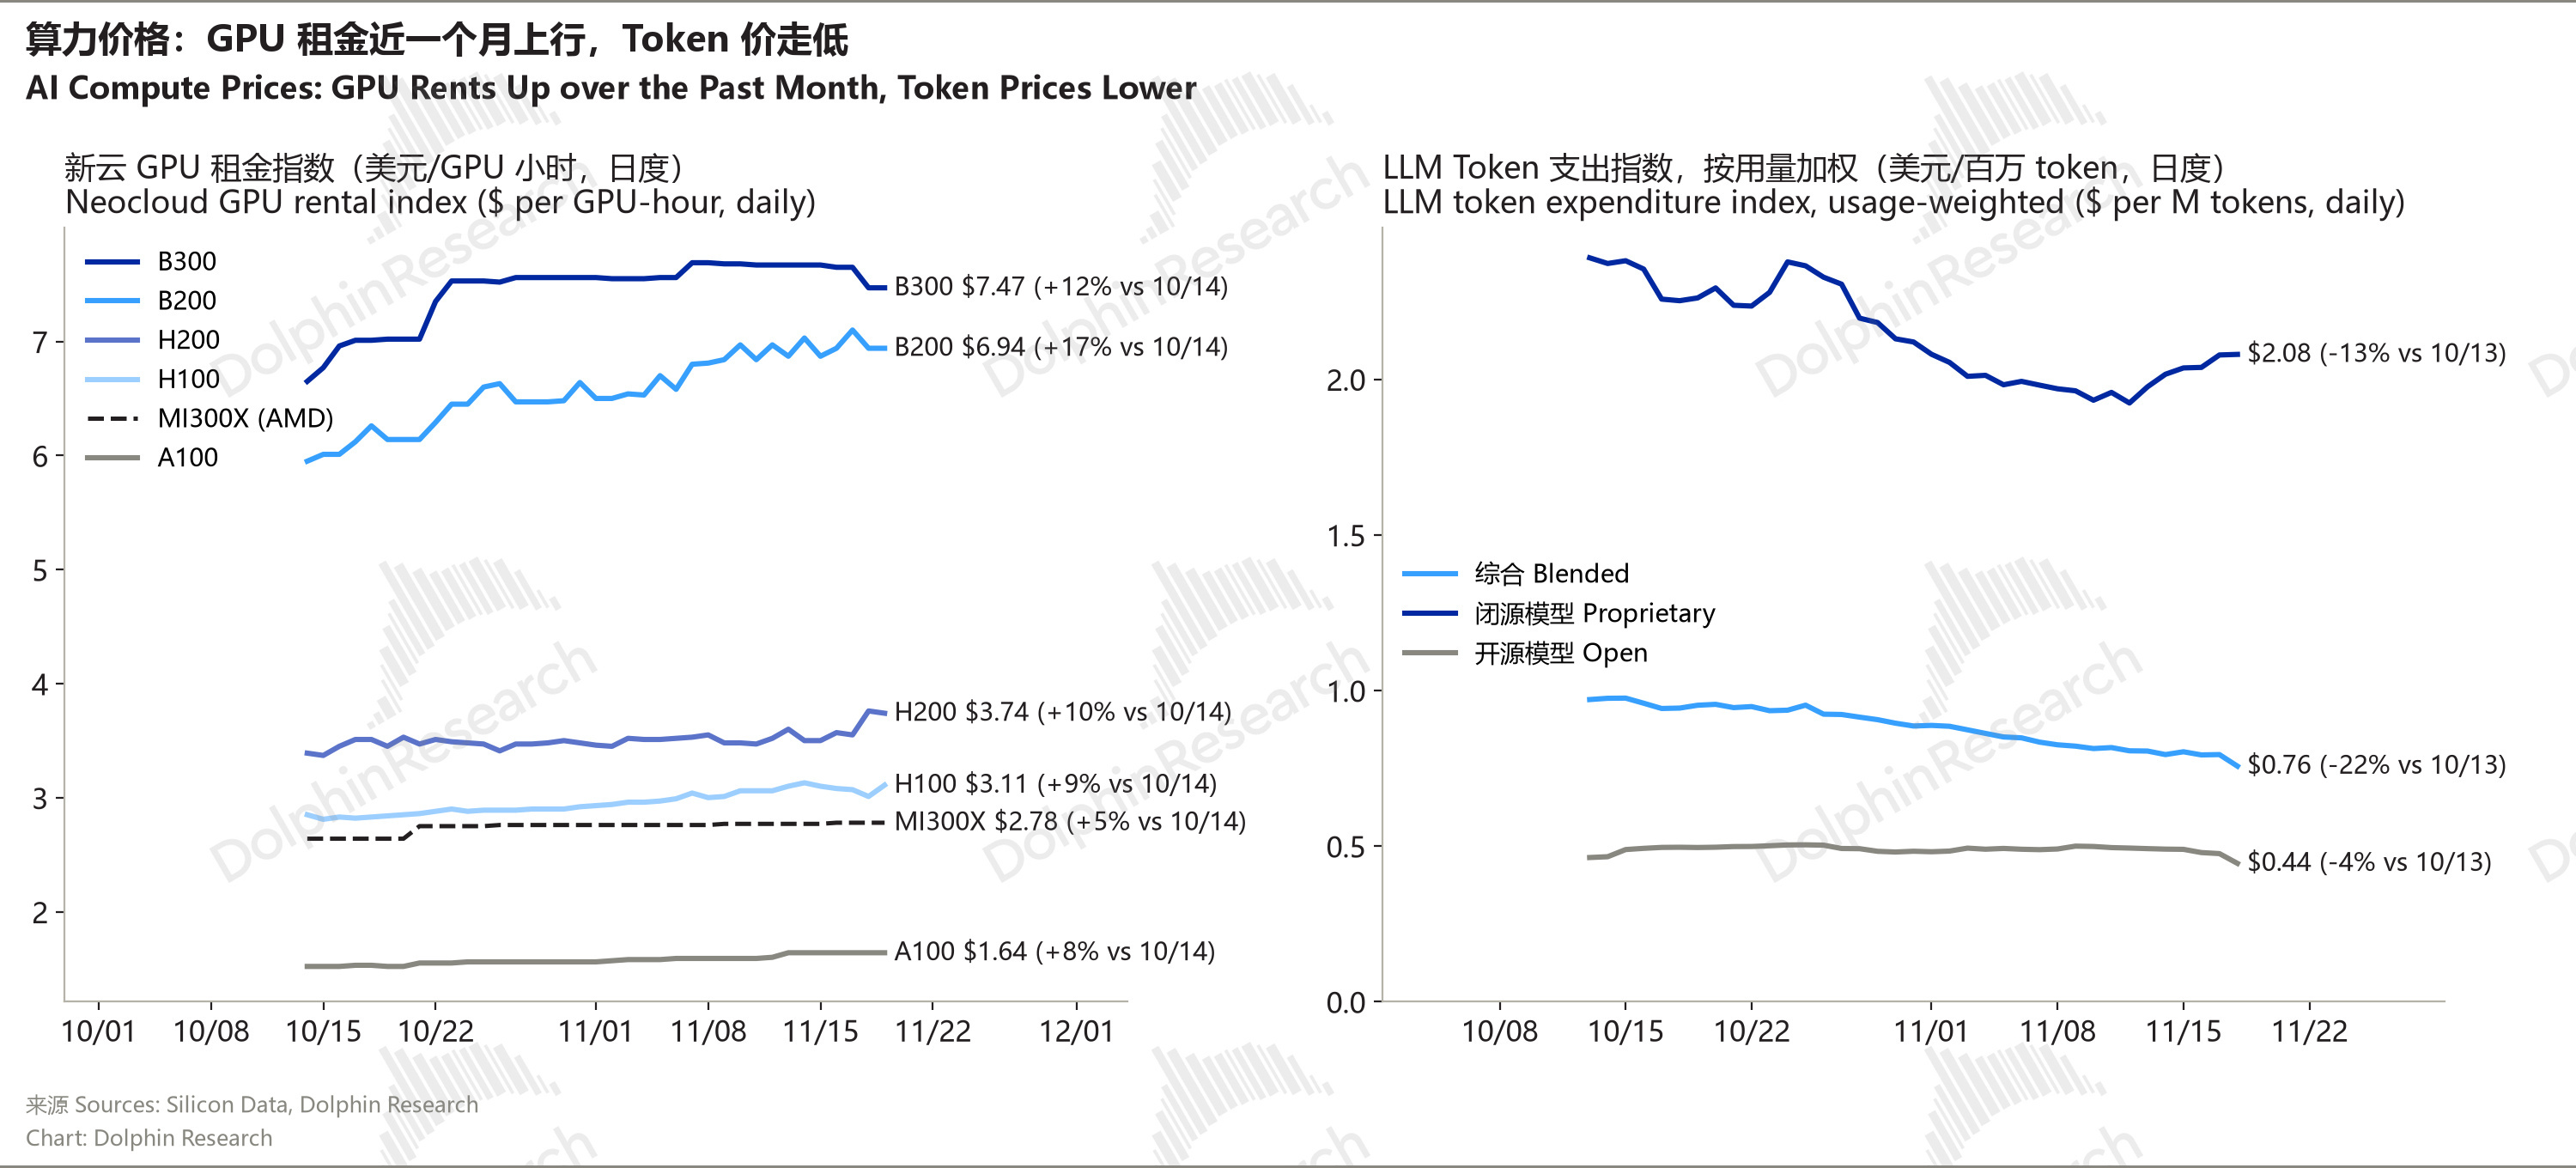
GPU rents: Silicon Data’s New-Cloud Rent Index on 11/19 showed B200 at $6.94/GPU-hr (+17% vs 10/14, -0.4% WoW), B300 $7.47 (+12%), H200 $3.74 (+10%), H100 $3.11 (+9%).
Token costs: Silicon Data’s LLM Token Spend Index (usage-weighted) ran at $0.76 per mn tokens on 11/18, -7.3% in 7 days and -22% vs 10/13; closed models $2.08 (+6.2% in 7 days), open-source $0.44 (-10.2%).
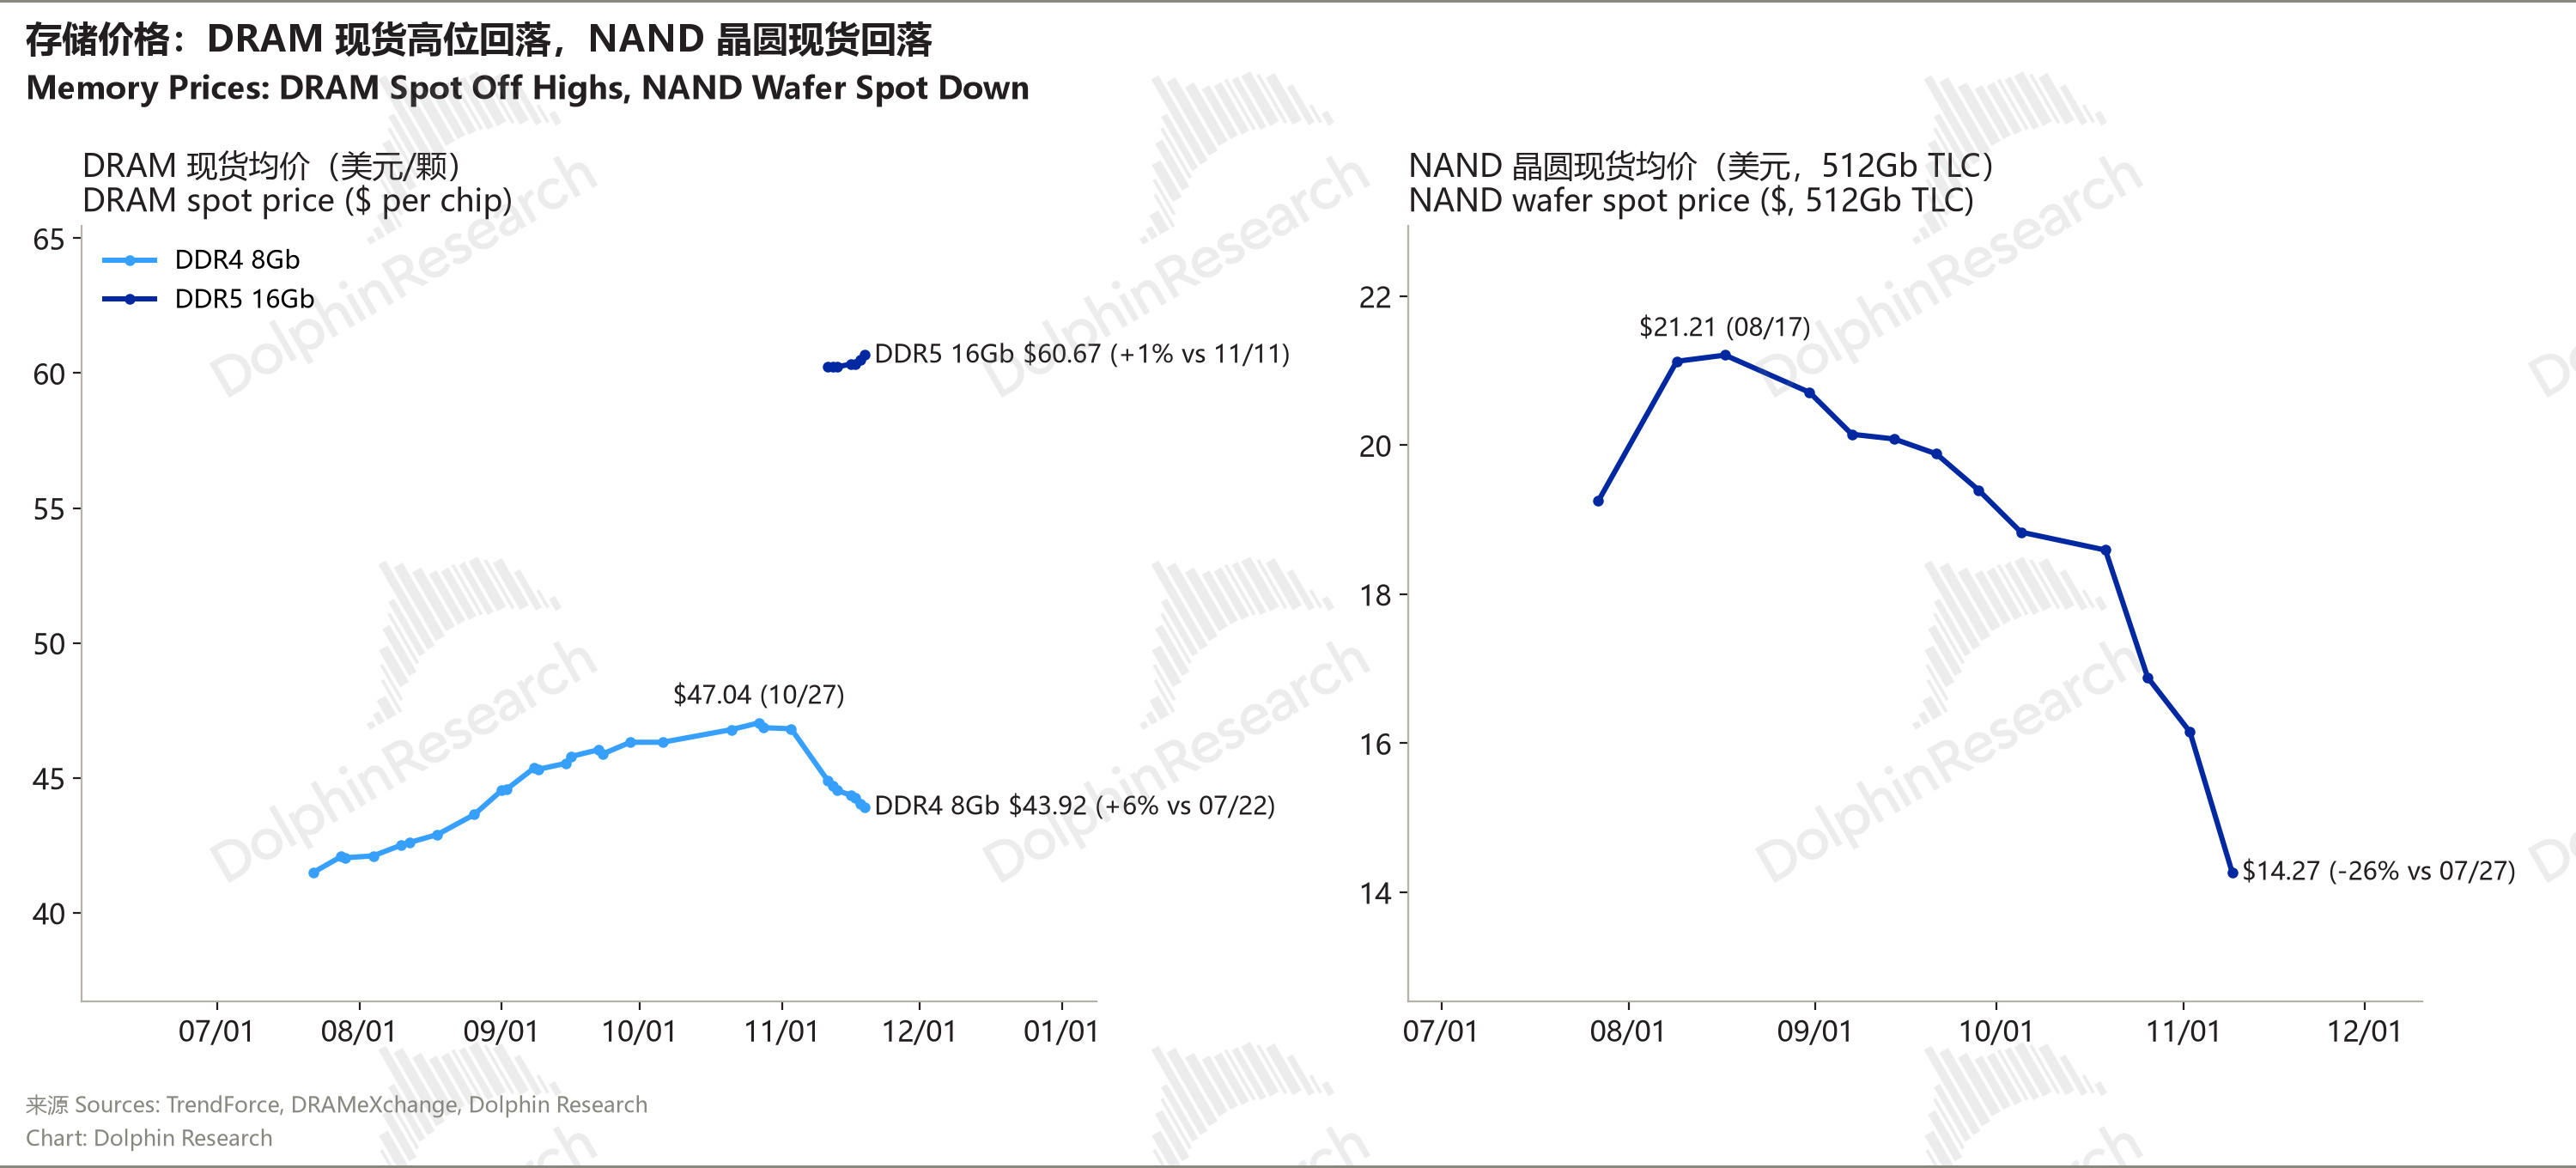
DRAM: DDR4 8Gb spot at $43.92, -6.6% from the 10/27 high and -1.8% WoW. NAND: 512Gb TLC wafer spot at $14.27, -33% from the 8/17 high.
NAND downcycle pulled forward: TrendForce (11/19) forecasts that China cloud’s cuts to 2027 enterprise SSD orders will outweigh US cloud’s incremental demand. NAND contract prices to decline from Q1 2027 (-0% to -5% QoQ), with all categories entering a downturn from Q2; 2027 global NAND capex is seen +26.7% to $29.9bn, bit supply +25%–30%.
SanDisk popped early, faded late: The CEO and CFO told the Morgan Stanley APAC Summit that SLC demand is now quantified at tens of EB. Every 1–1.5ppt mix shift to SLC lowers industry supply growth from ~20% to ~16%; customers are proactively negotiating 3-year contracts, though YMTC’s base case assumes it 'takes the China market'.
Within memory, only HDD names closed up, with Western Digital +3.0% and Seagate +1.1%.
4) Asia open and today’s setup (11/20)
Asia open: Nikkei 225 opened -1.4% and extended losses; KOSPI opened -4.1%, with Samsung -4% and SK Hynix -6%; MSCI Asia Pacific -1.1%.
US → Asia read-through:
Semis chain: With US semis sold to fund ANT and the SOX -2.4%, AI hardware in Taiwan/Korea should open weaker. Within memory, HDDs should hold up better than NAND.
China compute: Tighter foundry licenses under new rules imply further bifurcation across A-share GPU designers vs mfg. chains, with focus on SMIC and Hua Hong after yesterday’s rallies. BABA ADR fell only 1.3% while HK was already -5.5% yesterday, leaving room for a post-print bounce.


PDD | $122.4bn | +11.0%
Q3 revenue was RMB 108.3bn, roughly flat YoY and 6% below estimates, mainly as Temu stumbled in Europe and transaction services fell 11.7% YoY. Online marketing revenue was RMB 59.8bn (+12.1% vs +3.5% last quarter), with adj. OP of RMB 32.6bn beating by 17% and OPM at 30%.
S&M was RMB 25.3bn (-16.6% YoY), over RMB 6bn below market expectations. Mgmt cautioned single-quarter opex ratios are not extrapolative; the RMB 100bn support plan remains in strategic investment mode.
Dolphin take: With Temu forced to retrench and domestic monetization re-accelerating, plus limited spend on the new overseas 1P venture, PDD’s bottom looks set. At a 30% steady-state OPM, annual core OP is ~RMB 120bn, yet the market values it at ~6x PE; a re-rate to 8–10x implies 30%–60% upside, with >10x hinging on capital returns.
Risks: Tencent holds ~14% and has signaled asset sales to fund AI. (First Take)(Earnings Review)(Call Transcript)
WMT | ~$1.0tn | -1.0%
Q3 revenue was $188.8bn (+5.2% YoY), above the $187.2bn est. Adj. OP rose 5.5%, above the prior 2%–4% guide ceiling; FY adj. EPS guidance was raised to $2.84–$2.89; ads +37%, e-comm +23%.
But heavy price cuts since Jul did not accelerate US traffic (transactions +1.5%, flat vs Q2). Diesel and transport add over $2bn in costs this year, and implied Q4 OP growth of 4%–6% is below consensus.
Dolphin take: For a 44x PE name, the 'beat on profits, flat traffic, soft Q4 guide' combo is underwhelming. Still, down just 1% on an AI-led selloff day shows the retail bellwether acting as a haven. (First Take)(Earnings Review)(Call Transcript)
NTES | $67.2bn | -11.4%
Q3 game revenue posted a rare YoY decline and missed materially; implied gross billings fell 8% YoY. DPS was $0.585 per ADS (+22% QoQ) with minimal buybacks; 'Where Winds Meet' will launch globally across platforms on Jan 15, 2027.
Dolphin take: The gap phase is exacerbated by weak consumption and short-drama time cannibalization; evergreen titles provide a floor but not growth. At just over $70bn mkt cap, NTES trades at ~12x 2027 core net profit of RMB 41bn, near the low end of its historical range.
If sentiment keeps clearing, it nears a short-term entry, but as launch nears, watch 'underwhelming delivery' risk. (First Take)(Earnings Review)(Call Transcript)
Kuaishou 1024.HK
Q3 revenue was RMB 31.6bn (-11.1% YoY); ads -11% and worse than the -5% guide, and live-streaming -19%. Adj. net profit was RMB 0.79bn (-84% YoY), slightly above est.; Kling’s annualized revenue was not disclosed.
Mgmt said Q4 revenue and profit remain under pressure; it will shift to elastic compute via leasing and tighten costs, while maintaining buybacks and dividends.
Dolphin take: The inflection likely won’t come until mid-2027. Kling’s scarcity premium is diluted amid domestic model crowding, while short dramas siphon time from core.
Using net cash plus Kling stake at ~$15bn as an anchor vs a current mkt cap of $12.7bn, what’s missing is investor conviction. (Brief Review)(Call Transcript)

AAPL | $5.07tn | -0.9%
Bloomberg reported new Apple job posts indicate it is building a proprietary autonomous AI agent that can code, browse, and control apps/devices. This would enter a field contested by OpenAI, Anthropic, and Meta.
Lenovo 0992.HK
For the Sep quarter, revenue was $30.2bn (+48% YoY), beating the ~$27.6bn est. AI-related revenue was $10.8bn (+79%), 36% of total; Infrastructure Solutions (servers) revenue grew 178%, while PC units fell 22.4% YoY.

PANW +6.4% / OKTA +5.7% / CRWD +2.7%
Cybersecurity stocks rose against a broad selloff amid chatter of client data breaches at Visa, Mastercard, and JP Morgan. Palo Alto’s CEO Nikesh Arora said critical software vulnerabilities are being discovered at ~7x last year’s monthly pace, and patching workloads will remain heavy for at least 18 months; AI security product Prisma AIRS has reached nearly $170mn ARR five quarters post-launch.
Debate centers on Palo Alto’s $4.5bn acquisition of Applied Compute: bears call it defensive with new-cloud-like GPM that could dilute FCF and margins and lift capex; bulls see sound strategy with attractive optionality at a reasonable price.
Barclays said cybersecurity has evolved from an IT topic into a cross-sector investment theme; dedicated cyber funds’ AUM rose 24% QoQ in Q3.

NOK | $42.4bn | -1.2%
At Morgan Stanley’s Europe TMT, the CFO said AI/cloud orders reached €5.3bn YTD through Sep, nearly +300%. The company maintained 25%–30% growth for IP and Optical by 2027 and said 'supply largely dictates how much we can sell'.
San Jose Fab 2 will lift photonic chip capacity by 20–25x by H1 2028, with a new DSP sampling in H1 2027 and ramping in 2028.

VRT | $71.2bn | -4.9%
BofA removed Vertiv from its US1 list. Korea’s ET News said Midea, Gree and Haier are expanding DC cooling lines and overseas capacity for 2027–28; Midea has joined the NVDA MGX ecosystem.


| Date | Event | What to watch |
| 11/20 Fri | Japan Oct CPI (07:30); China Nov LPR (09:15) | Japan core CPI seen at 2.3% (prev 2.1%), key to BoJ’s Dec move; 1Y and 5Y+ LPR were 3.0% and 3.5% |
| 11/24 Tue | Dell, Xiaomi earnings | See previews below |
| 11/26 Thu | US Thanksgiving (11/27 half-day) | Liquidity thins before the holiday |
| 12/8–9 | FOMC | Hike 25bps or 50bps |
| 12/9 | Micron CHIPS Act curbs ease | MU says robust shareholder returns to begin |

Dell DELL | 11/24 US after-hours
Focus: With AI hardware under pressure, markets want to see if Dell can still post record AI orders and backlog, and whether GPM can hold amid storage price hikes.
Dolphin watchlist: AI new orders, AI backlog, AI server revenue, margins, and whether the $190–$194bn FY revenue guide is raised again, plus any early view on next FY.
Xiaomi 1810.HK | 11/24 HK after-hours
Focus: Memory price inflation continues to squeeze smartphone GPM, though TrendForce sees NAND turning down from Q1 next year. In autos, watch whether the range-extended SUV can pull deliveries toward the 550k FY target.
Dolphin watchlist: Whether smartphone GPM dips below 8%, timing for IoT stabilization, ASP and GPM in autos, and whether mgmt revises the 550k target.
<End here>
Recent Daily Recaps
2026-11-19: Daily | Earnings can’t revive a soulless NVDA; ANT soaks up $500bn; cyber surges
2026-11-18: Daily | Jensen offstage, new CEO becomes the savior; ANT nears listing, software hit by OAI
Risk disclosure and disclaimer: Dolphin Research Disclaimer and General Disclosures
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.