

09899

NetEase: The pipeline-gap hangover hits, but new “medicine” is coming
 I'm LongbridgeAI, I can summarize articles.
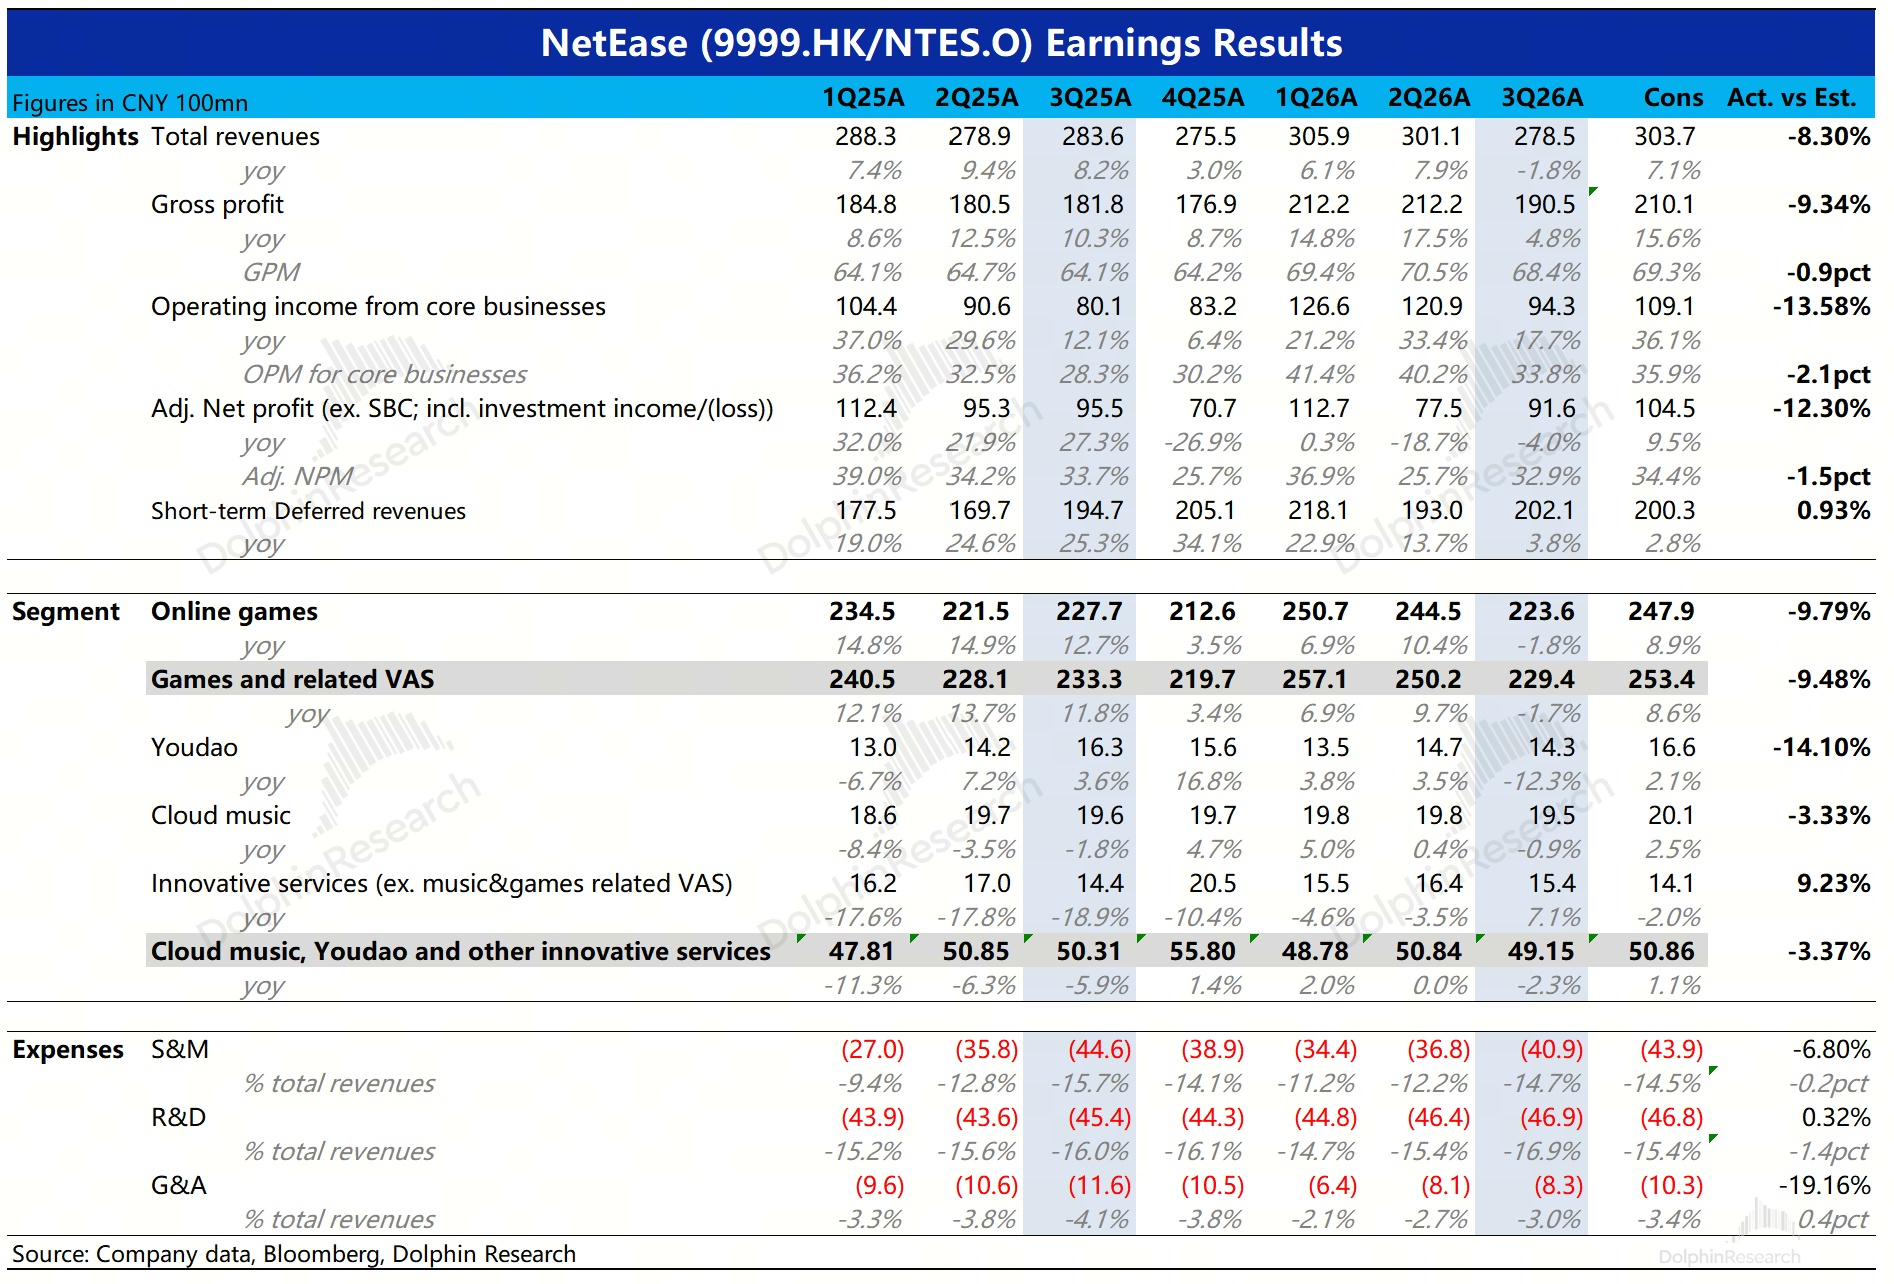
NetEase released its Q3 results after the Hong Kong close on Nov 19 Beijing time. Results were weak and missed clearly. The pipeline gap that we worried about last quarter was amplified by a worsening consumption backdrop and time cannibalization from short dramas, and evergreen titles alone could not carry the load.
Specifically:
I) Game revenue fell, and deferred revenue offered little help
Total revenue was RMB 27.9bn, down 1.8% YoY. Game revenue was RMB 22.4bn, also down 1.8% YoY and well below expectations.
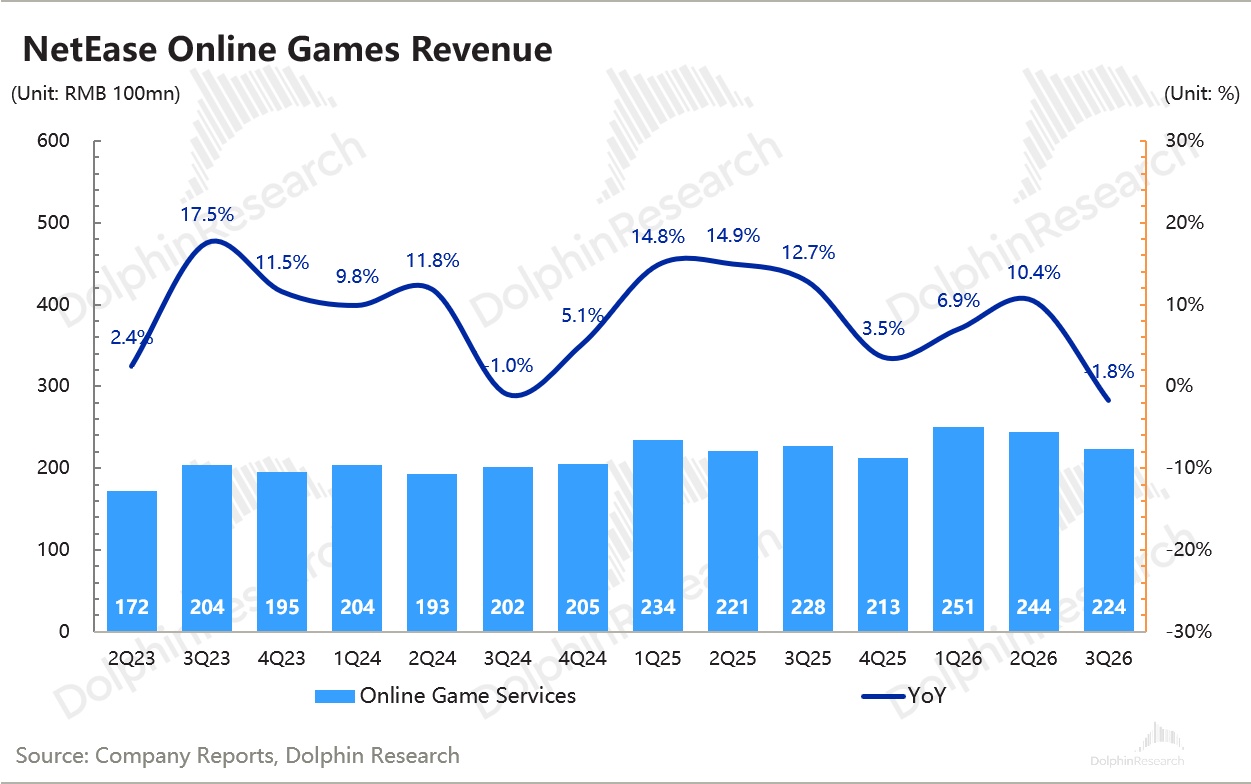
The low print was not a deferral timing issue. Deferred revenue grew only 4% QoQ, implying billings -8% YoY and +6% QoQ, and by seasonality this is the weakest 'summer peak effect' for NetEase in nearly five years.
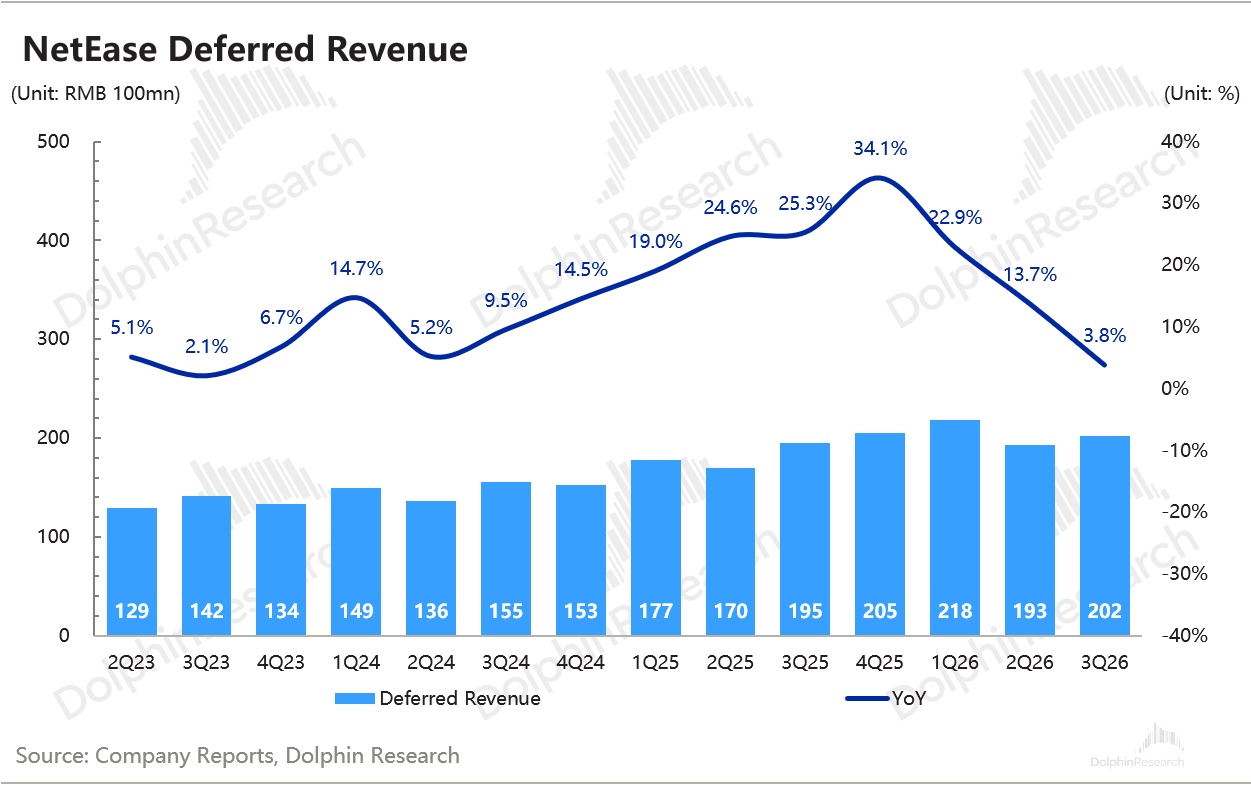
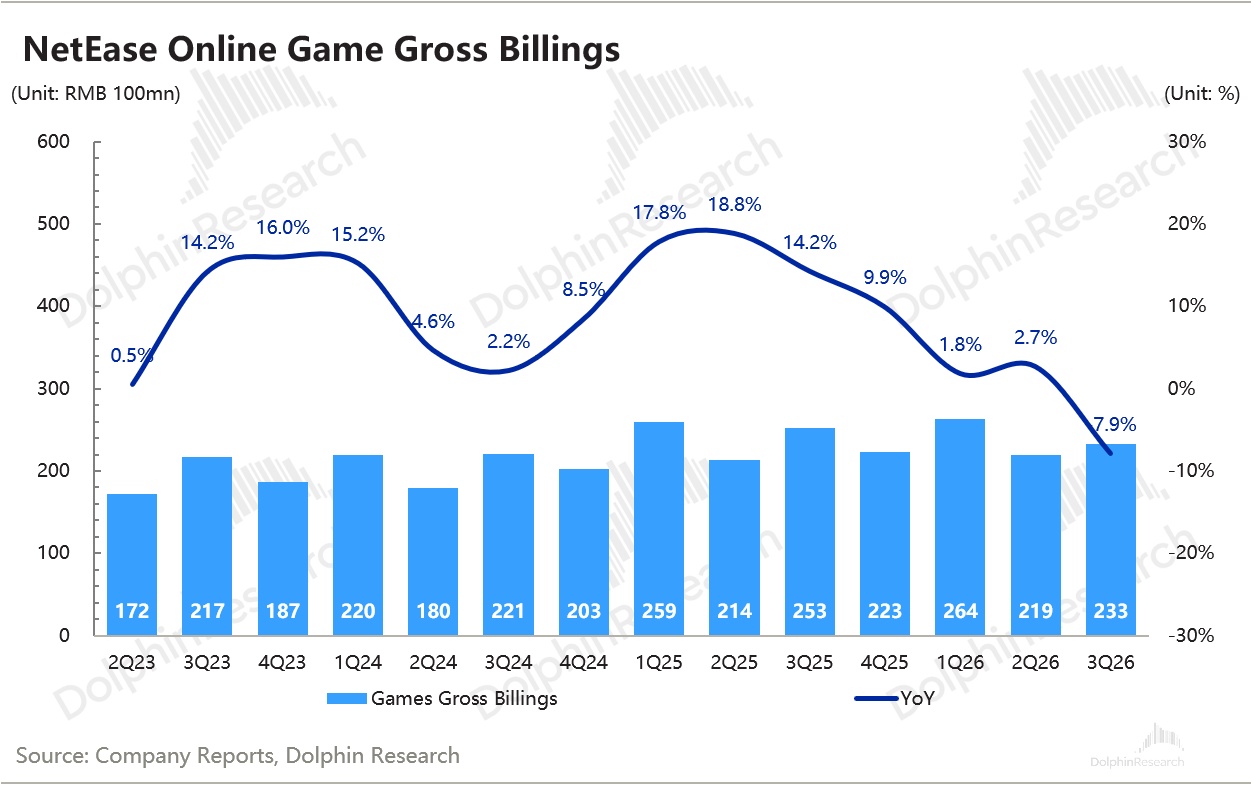
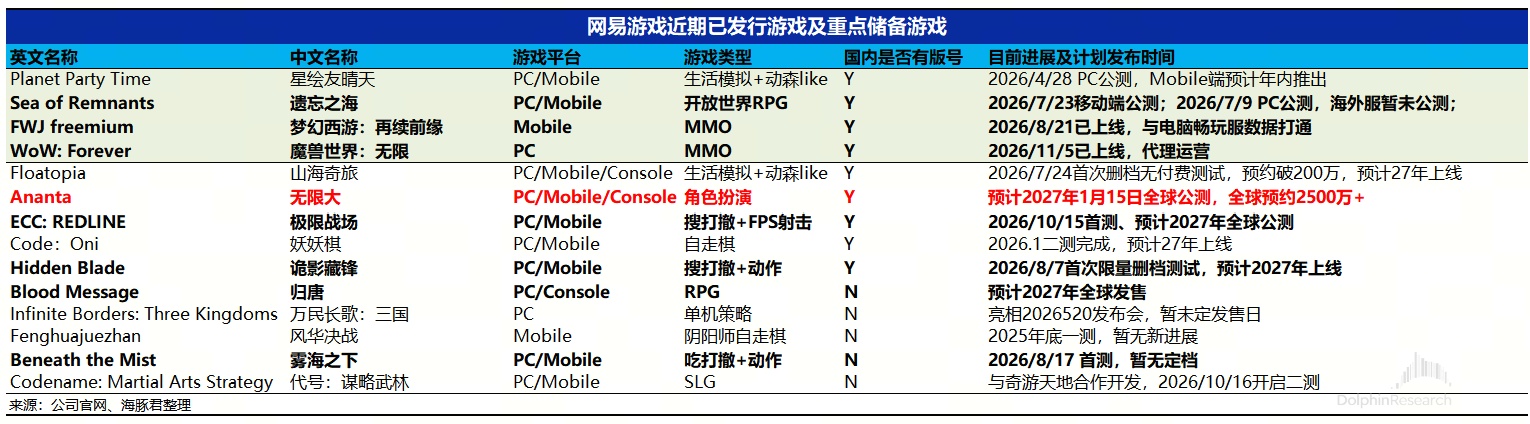
We also think the Street went in too high. With Sea of Remnants already a clear miss by Q2 and Q3 offering only a semi-new mobile title like Fantasy Westward Journey: Freeplay, the window was always tight, yet the market still penciled in high-single-digit growth, which was optimistic.
The only consolation is that a new product cycle starts in 2027, led by the much-anticipated Ananta. We have a preliminary pipeline list, and will watch the call for any updates.
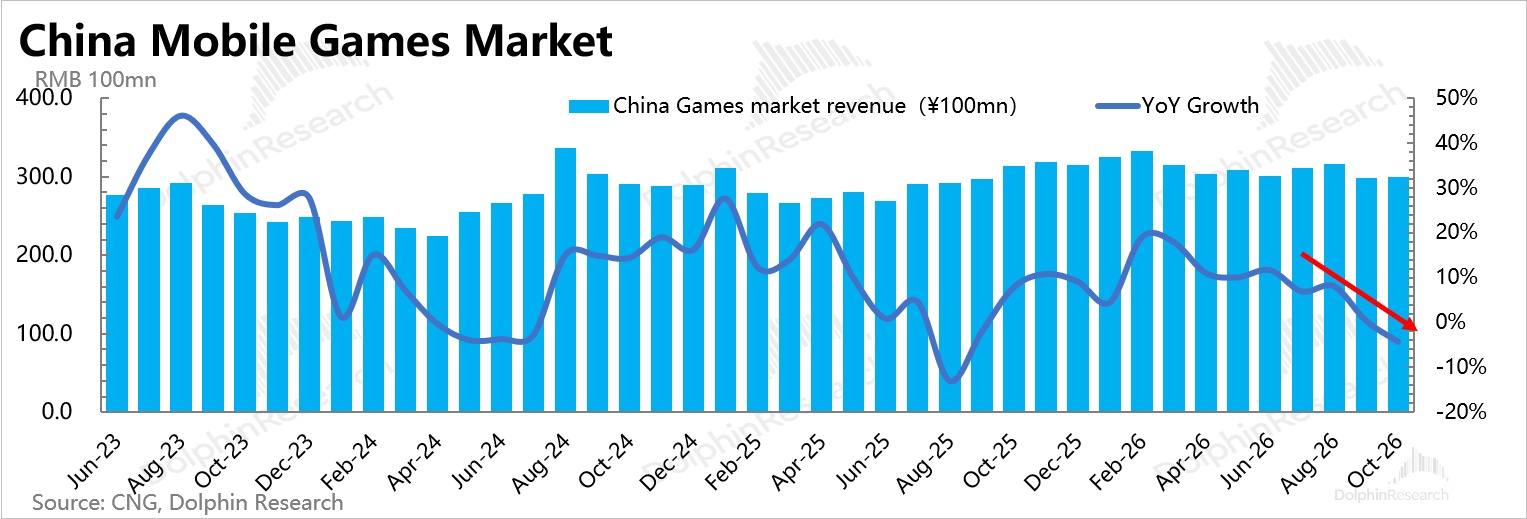
Comparing with Tencent and the broader game market, we see a softening trend since H2. A high base is part of it, but short dramas have exploded alongside AI-driven productivity, and as adjacent entertainment formats, it is hard to argue there is no overlap or cannibalization.
On top of that is a further deterioration in macro consumption. Games are less macro-sensitive and more tied to product cycles, but if AI’s impact on productivity extends deeper into gaming, long-term winners likely remain evergreen titles and distribution channels.
II) Games cooled, margins came under pressure
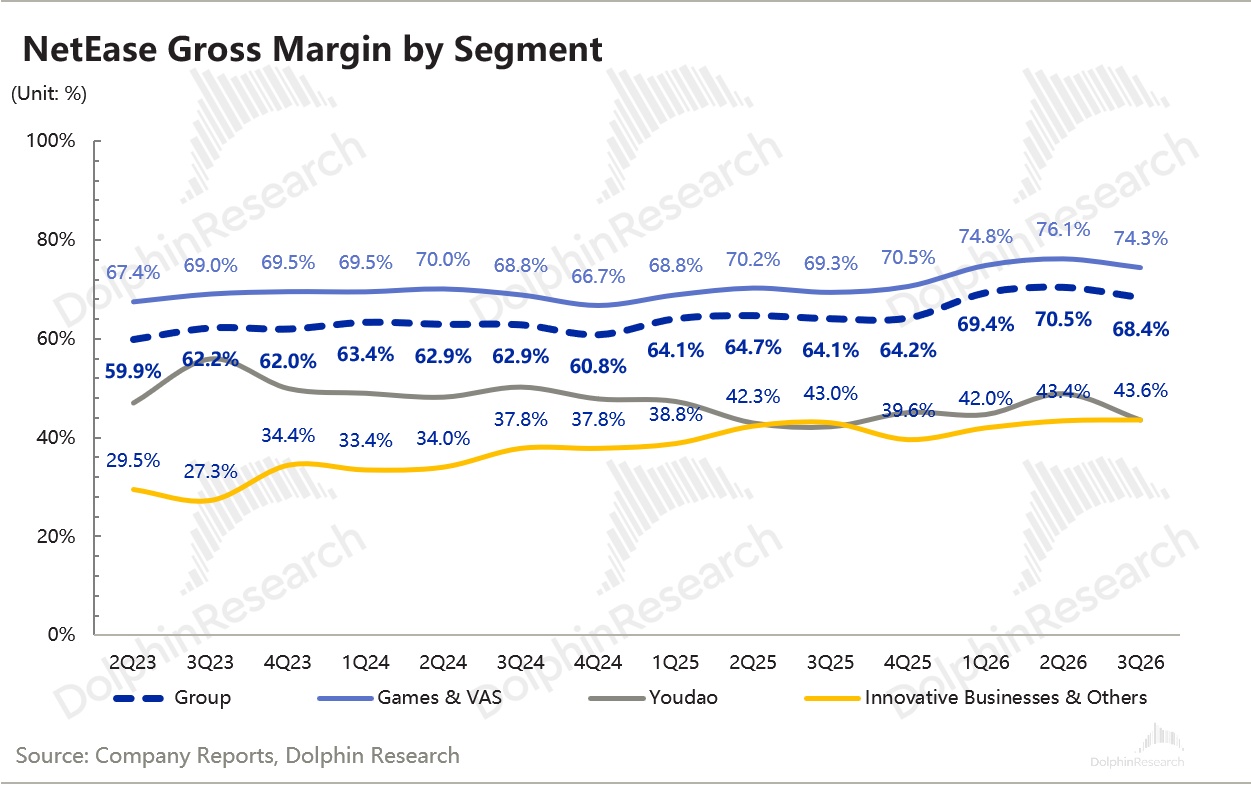
With high-margin games underperforming, GPM fell 200bps QoQ to 69%. Other segments like Youdao and Cloud Music dragged rather than helped.
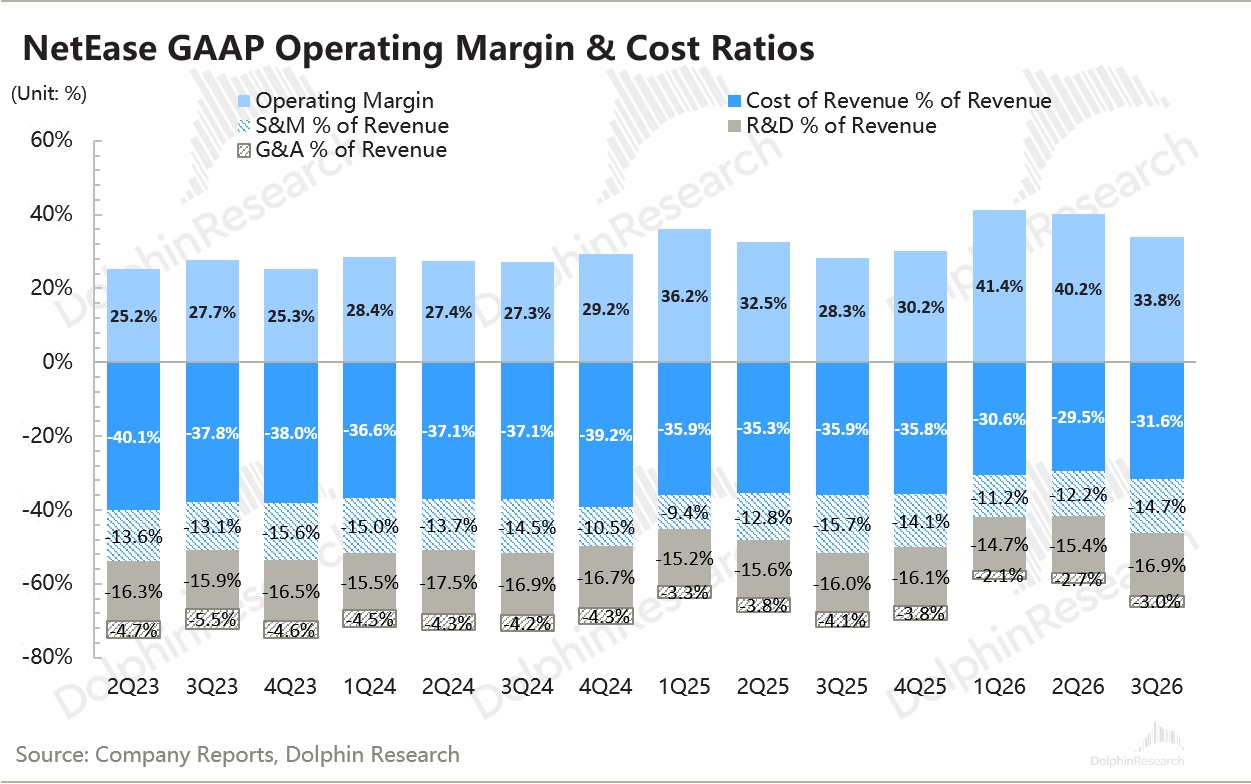
Opex fell 5% overall, mainly on lower S&M and G&A as fewer new launches cut marketing and pay cuts flowed through for admin/ops staff. The opex ratio was stable YoY and edged up QoQ.
III) Shareholder returns look attractive mostly on pullbacks
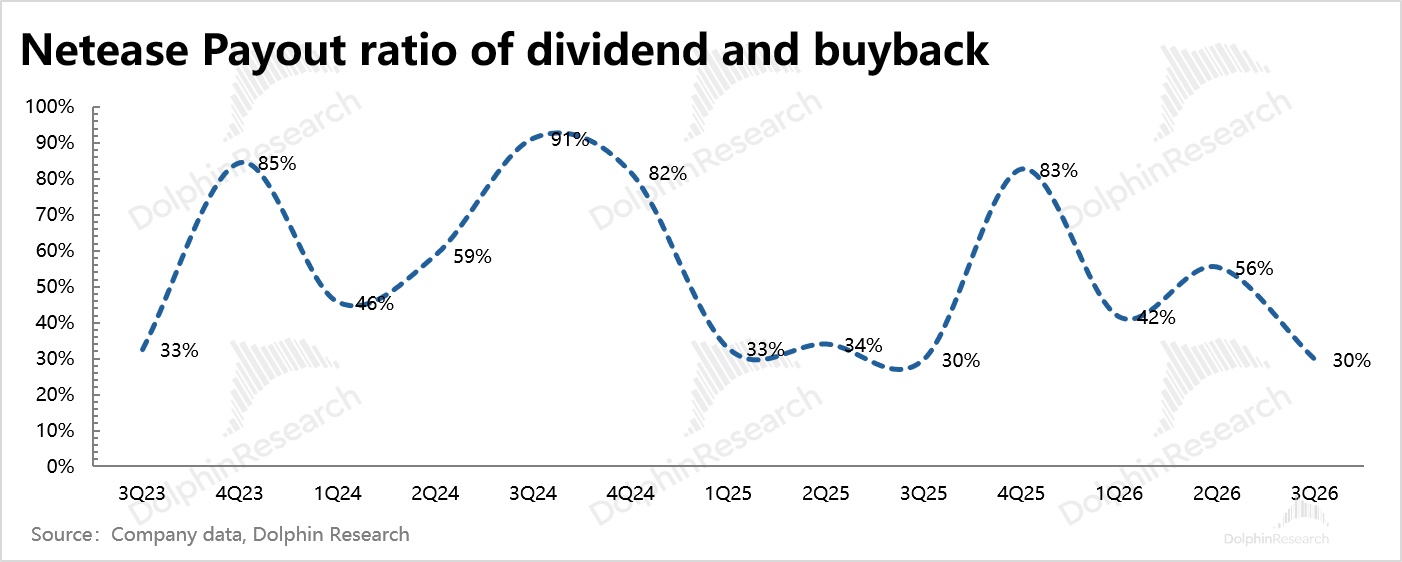
The quarterly dividend rose to $0.585 per ADS, +22% QoQ, keeping a 30% payout ratio. Year-end usually brings a special, implying a ~40% full-year payout, or roughly RMB 14.0bn (~$2.0bn) in dividends for 2026.
Buybacks were near zero in Q3. NetEase tends to repurchase flexibly with market cap, and $2.7bn remains authorized through Jan 2029, which implies an annualized pace under $0.7bn if spread linearly.
Dividends plus buybacks total about $2.7bn. Against a $75bn market cap, implied shareholder yield is under 4%, which is modest.
Cash at Q3-end was RMB 175.2bn (~$26.1bn), which in theory can support sustained buybacks. Operating cash inflow was RMB 10.5bn for the quarter, and the cash-cow nature is intact.
NetEase earnings call transcript: 'NetEase (Trans): 'Yihuan' slated for Jan 5 next yr; skins monetization is a long-term play'
Dolphin Research Overall View
Last quarter we flagged the pressure from a window gap. While we trusted the support from evergreen titles, with valuation neutral at the time we suggested waiting for a pullback for better odds.
Looking past expectations, Q3 gaming pressure was indeed material. Evergreen titles such as Eggy Party still delivered, but going too long without new launches is hard, as evergreen can backstop but not ensure growth.
The miss should trigger some downside, but the upcoming new cycle and a ‘light AI spend’ label suggest there may be buyers on weakness.
(1) A 2027 new product cycle is imminent, led by Ananta. We think if the earnings-driven sell-off is sizeable, some capital may step in, but near mid-Jan when Ananta launches, one should manage the risk of a potential performance miss.
(2) On trading, the stock has been more resilient vs. China ADR peers, as some funds favor NetEase’s AI-hedge label (lighter AI spend and resilient near-term cash flows) rather than purely betting on fundamentals.
After a 5.5% pre-mkt drop, market cap is just above $70bn. On 2027 core net profit est. of RMB 41.0bn at a 17% effective tax rate, excluding investment gains, interest and FX, the implied P/E is ~12x, near the lower end of its historical range.
In other words, much of the downside has been priced after the recent pullback. If sentiment keeps pushing lower, a near-term entry opportunity may be approaching.
<End here>
Dolphin Research historical on ‘NetEase’:
Earnings season (past year)
20 Aug 2026 Call ‘NetEase (Trans): Rich post-launch content for Sea of Remnants with ongoing UX optimization’
20 Aug 2026 Earnings take ‘NetEase: Still milking the legacy, but the balance sheet stays thick’
21 May 2026 Call ‘NetEase (Trans): For Ananta, willing to trade time for quality’
21 May 2026 Earnings take ‘NetEase: Window gap but still delivering, with veteran game-making prowess’
11 Feb 2026 Call ‘NetEase (Trans): Sea of Remnants delayed to Q3, Ananta still in polish’
11 Feb 2026 Earnings take ‘NetEase: The ‘Pig Farm’ must endure’
Deep dives
25 Jun 2021 ‘NetEase: The Pig Farm’s super ‘cycle’ | Dolphin Research’
Hot topics
27 Jul 2021 ‘NetEase maintains a long-term $115–141 target price’
Risk disclosure and statement for this article: Dolphin Research disclaimer and general disclosure
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.