

1179

H World: Same-Store Lags, Profits Soar — Is the “Asset-Light Cash Machine” Firing on All Cylinders?
 I'm LongbridgeAI, I can summarize articles.
Before the U.S. market open on Nov 16, 2026 (Beijing time), H World released its Q3 2026 results. $HWORLD-S(01179.HK) , $H World(HTHT.US)
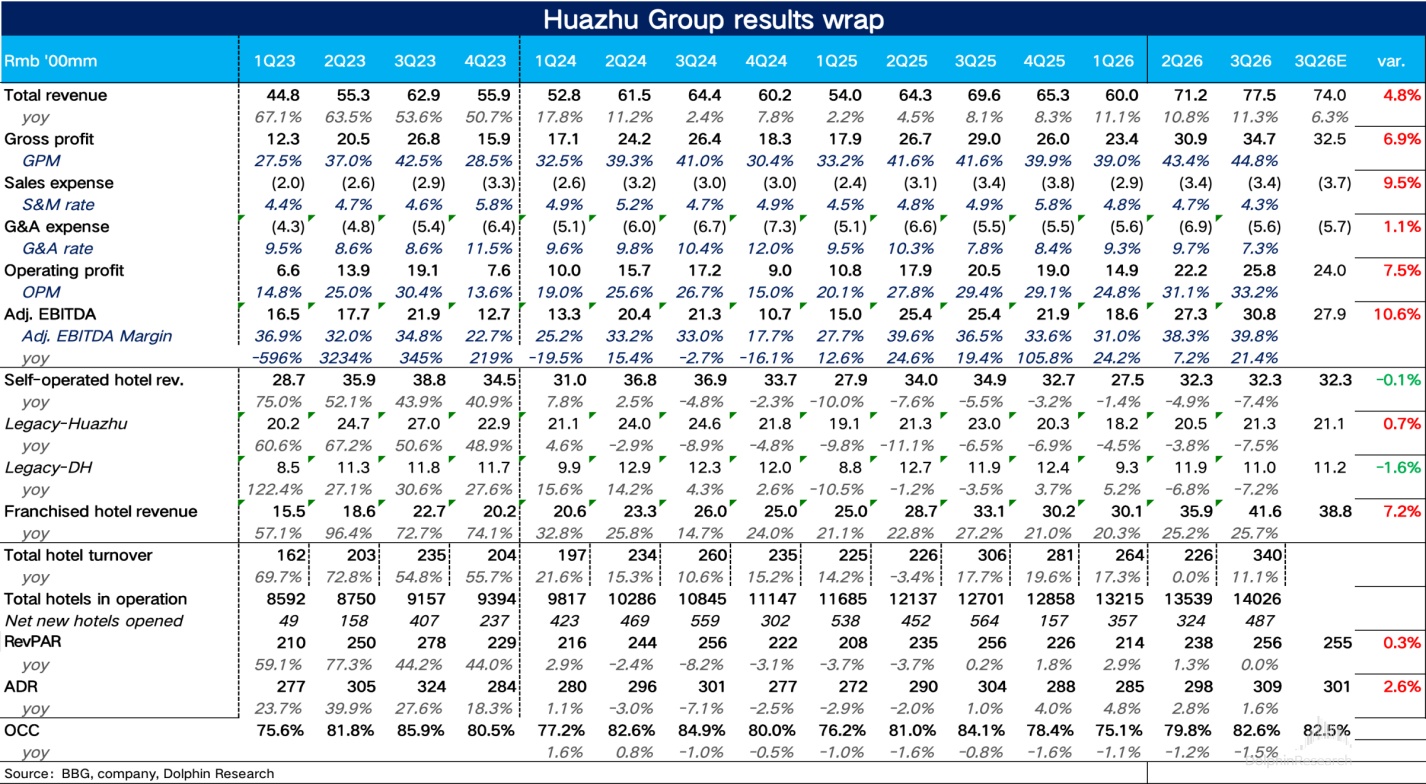
Overall, Q3 was a broad beat across the board: revenue and profit both came in well above the Street, and full-year guidance was raised sharply again. The only blemish was that same-store RevPAR decline for mature hotels widened vs. Q2, with key details below.
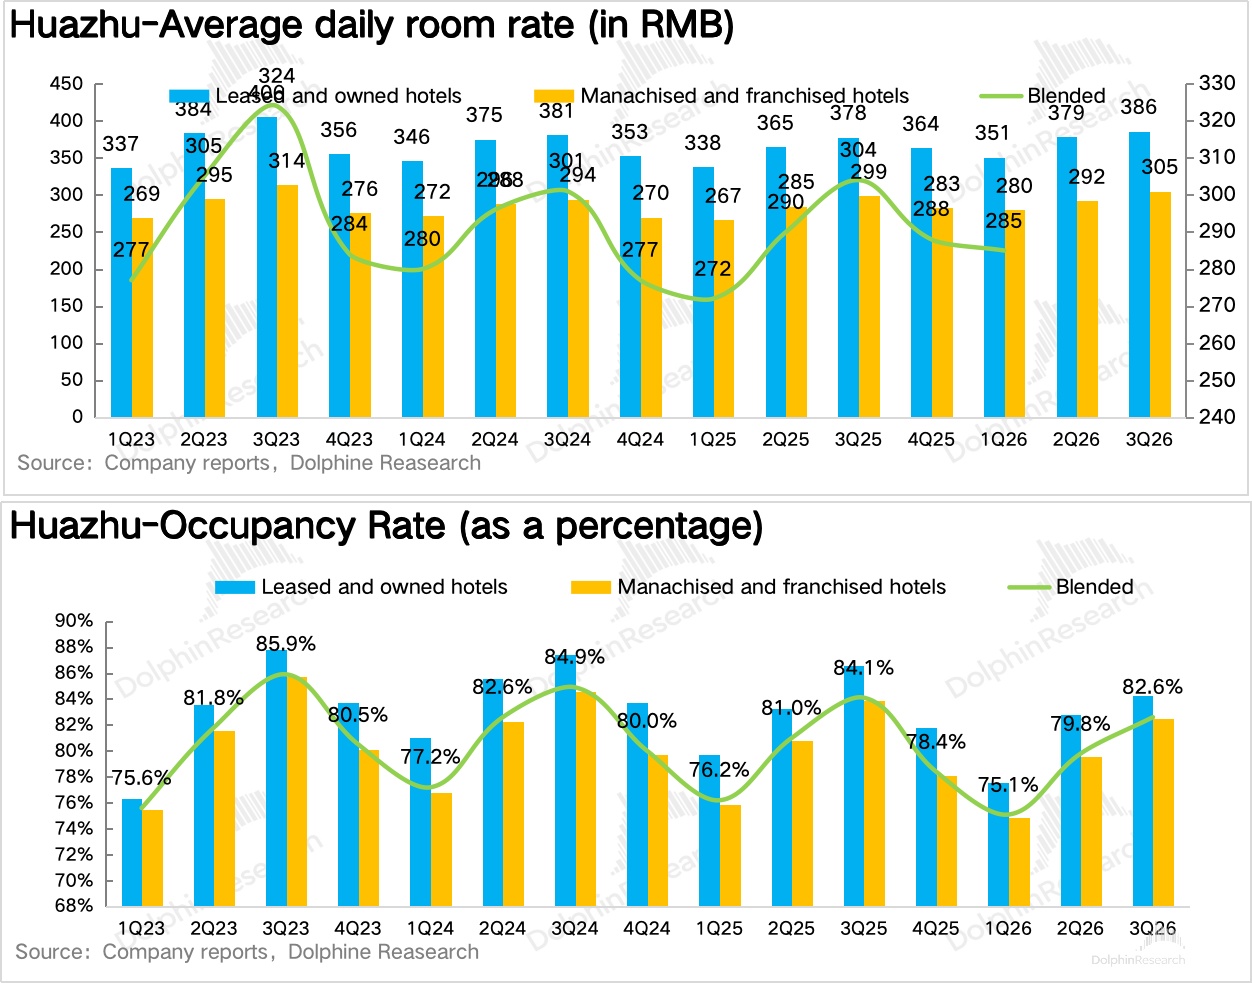
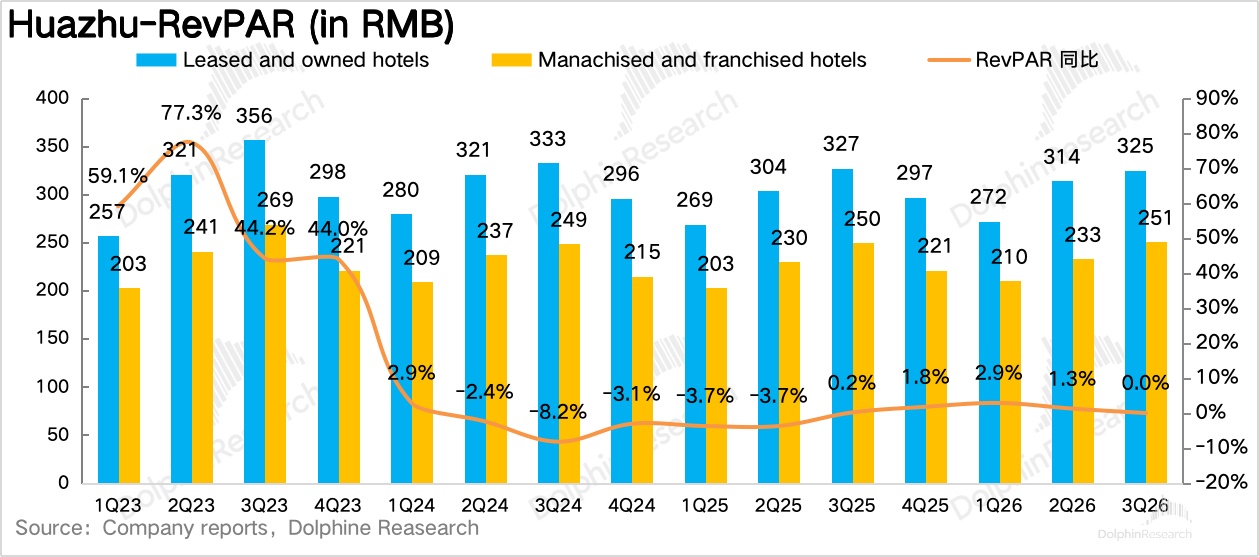
1. Domestic RevPAR was flat, with a wider same-store decline. On the core operating metric RevPAR, H World China delivered RMB 256/room-night in Q3, up 0.1% YoY. This barely extended the streak to a fifth straight quarter of positive growth, but growth slowed further from +1.1% in Q2.
By component, ADR rose 1.8% YoY to RMB 309/room-night, the only positive driver, helped by mix upgrades from new versions of Hanting and All Seasons (Quanjing) and better yield management. OCC was 82.6%, down 140bps YoY, with a slightly larger decline than in Q2.
Note that for mature hotels: same-store RevPAR (stores open ≥18 months) fell 4.4% YoY, widening from -3.0% in Q2. Same-store ADR fell 1.3% YoY and OCC fell 270bps YoY, implying pressure on both price and volume, with similar declines across economy and mid-to-upscale. This suggests weaker summer peak demand and pricing pressure industry-wide, while H World’s blended portfolio held up mainly via new openings and product upgrades.
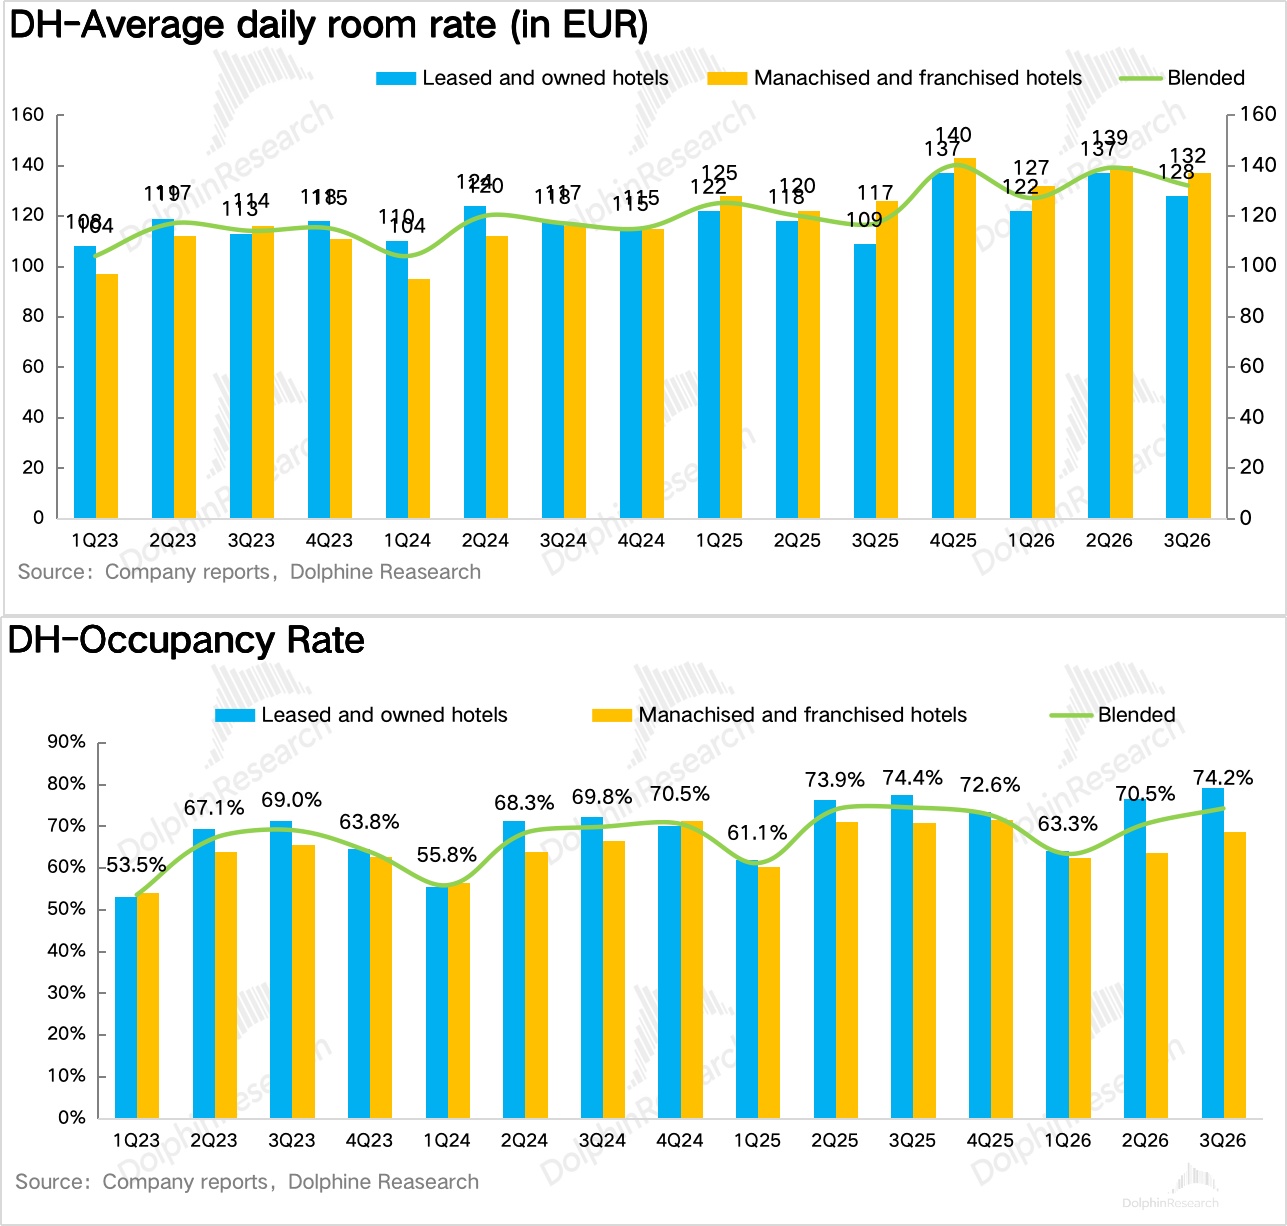
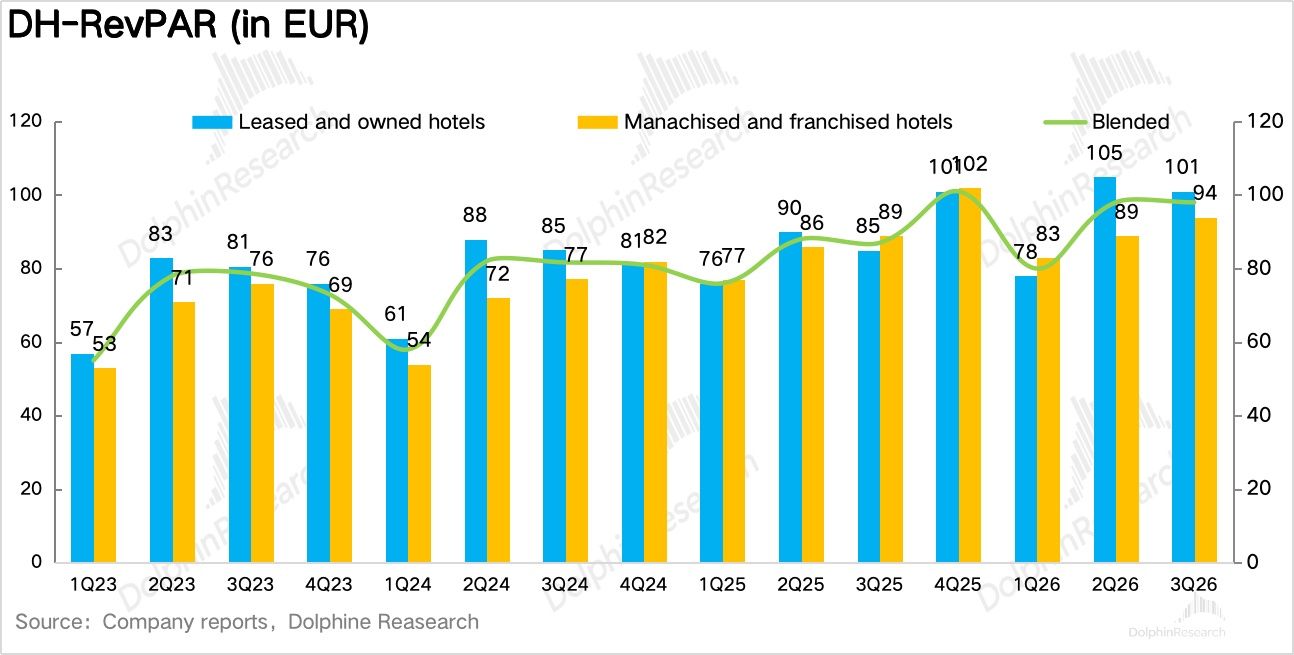
Overseas, international RevPAR was roughly flat YoY in Q3, a notable improvement from -3.8% in Q2. Revenue fell 7.7% YoY due to closing some leased hotels in Europe, but Adj. EBITDA doubled YoY, reflecting tangible cost-out and efficiency gains.
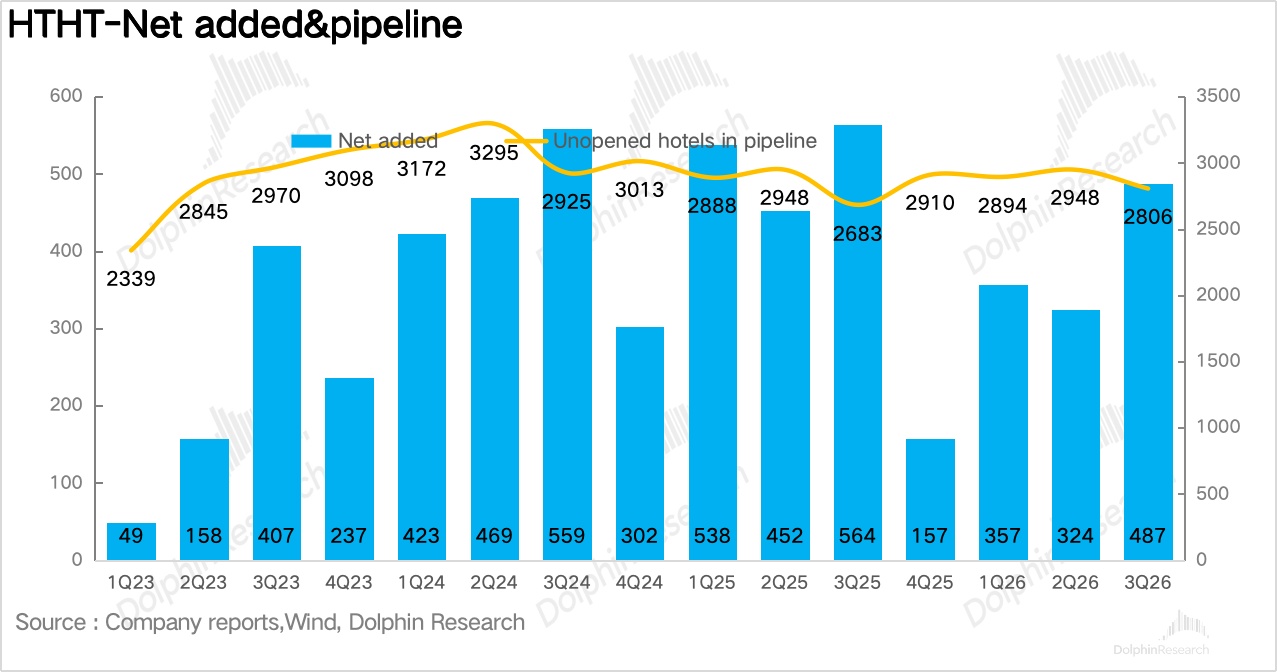
2. Openings accelerated, but the pipeline declined. In China, net adds were 489 hotels in Q3 (664 openings, 175 closures), a faster pace vs. 501 in Q2, bringing YTD openings to 1,700. However, the end-Q3 pipeline stood at 2,806 hotels, down from 3,054 at end-Q2, indicating faster openings are drawing down the pipeline while new signings slowed.
Dolphin Research estimates that with same-store declines persisting and single-hotel payback periods lengthening, franchisees’ funding appetite is weakening at the margin.
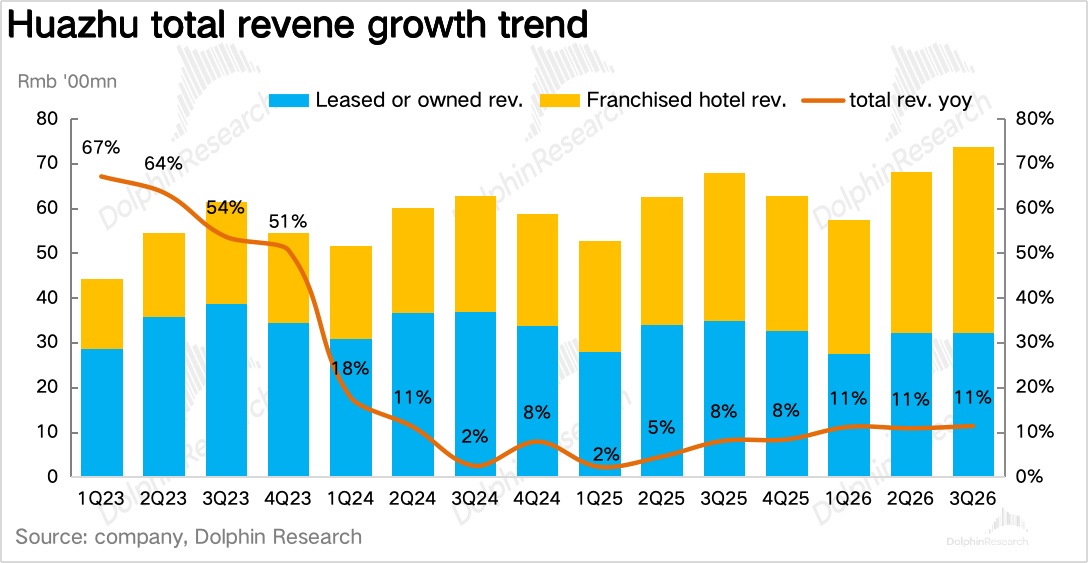
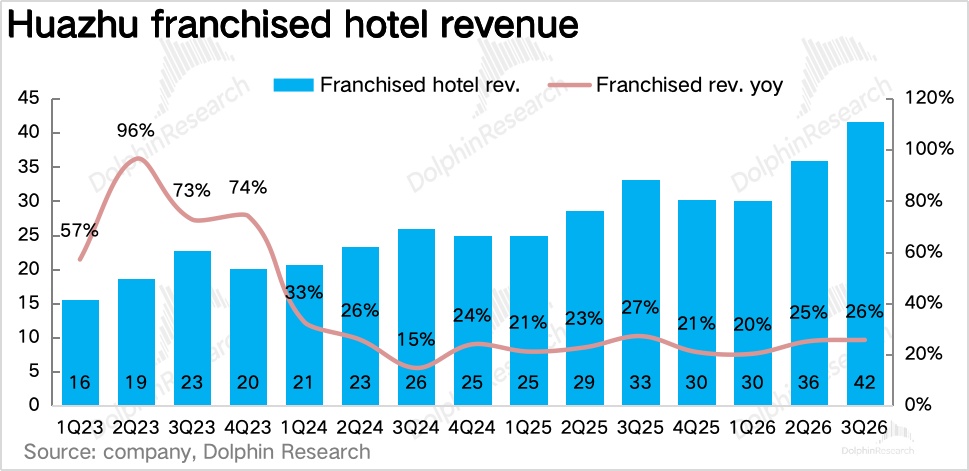
3. Revenue beat, with franchise as the clear engine. Group revenue reached RMB 7.75bn in Q3, up 11.3% YoY and accelerating QoQ, beating market expectations. Franchise revenue was RMB 4.16bn, up 25.7% YoY, further accelerating vs. Q2 and serving as the core driver.
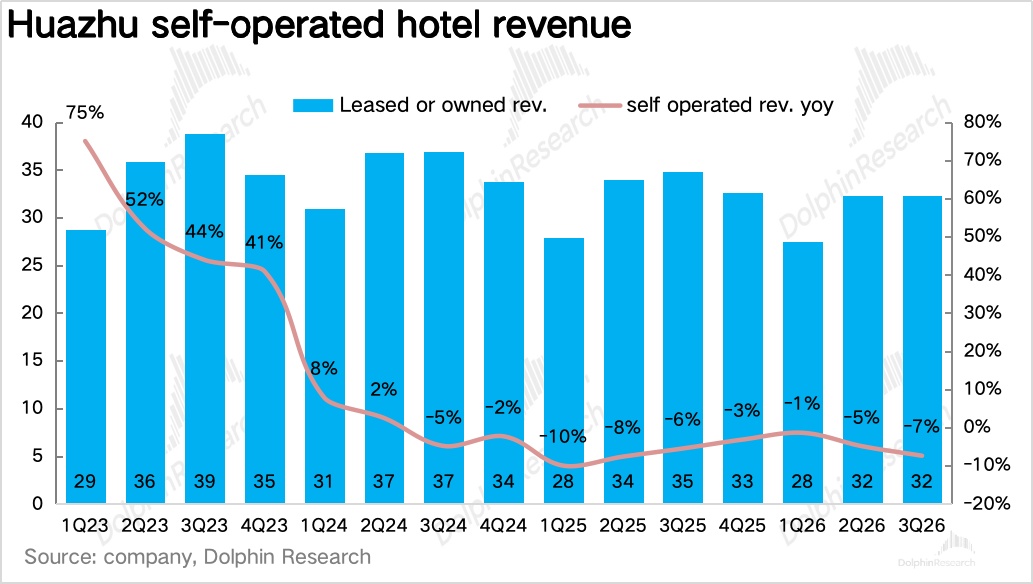
Importantly, China franchise room count grew only about 12.5% and franchise RevPAR was roughly flat. The much faster franchise revenue growth vs. room count came mainly from higher fee take rates and more fee items per hotel. Owned/leased revenue was RMB 3.2bn, down 7.4% YoY, primarily due to continued exits from domestic leased hotels and European closures.
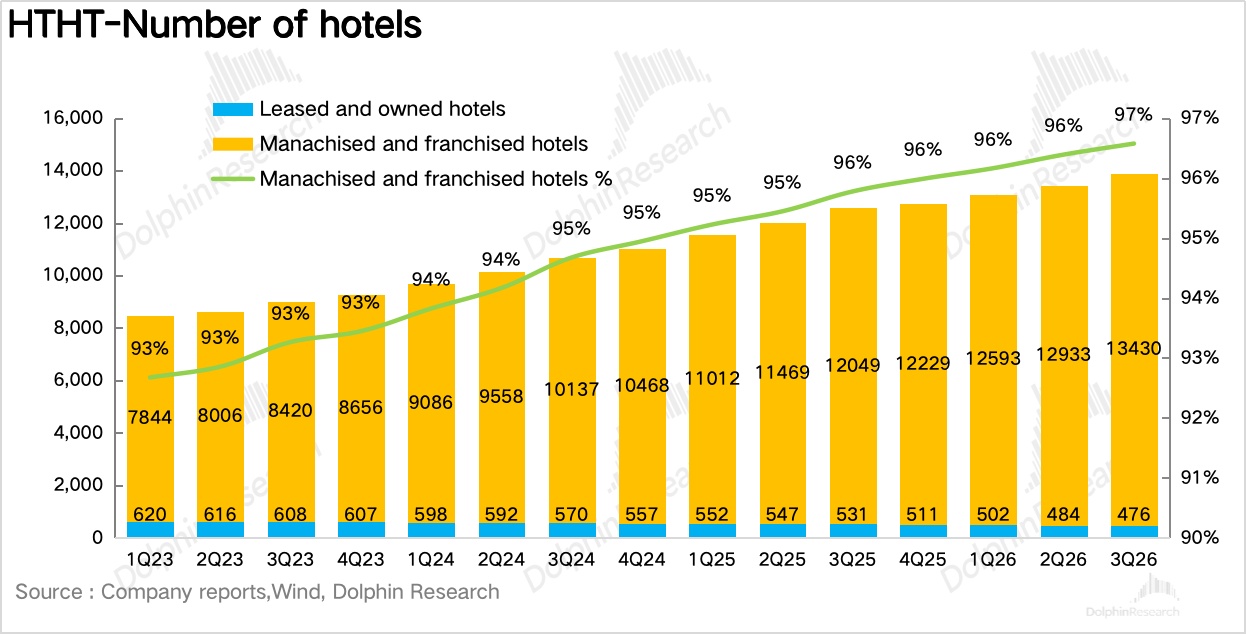
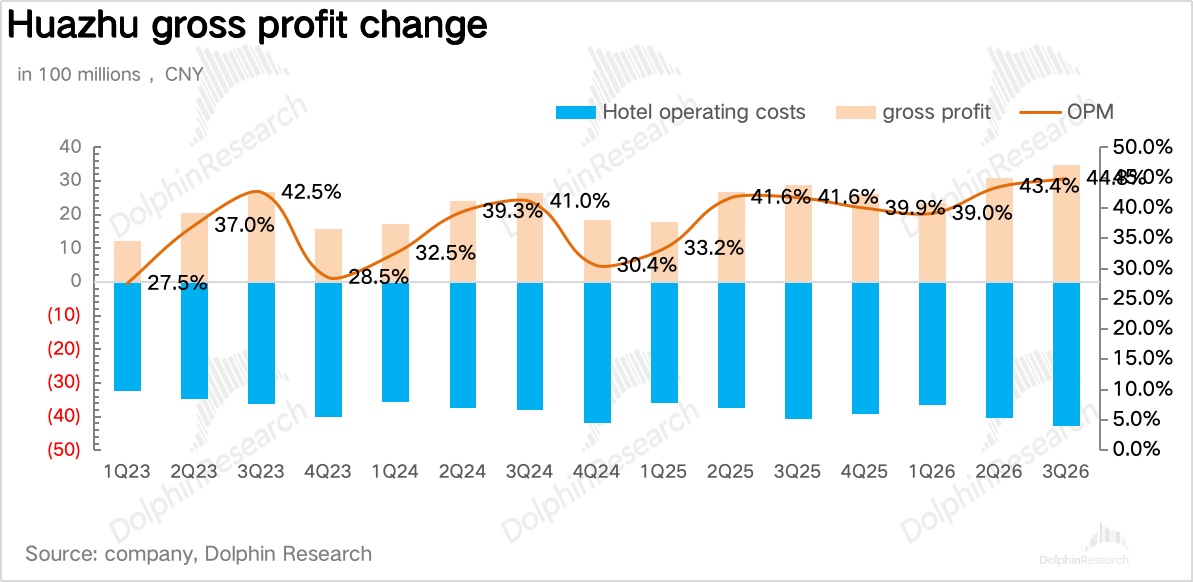
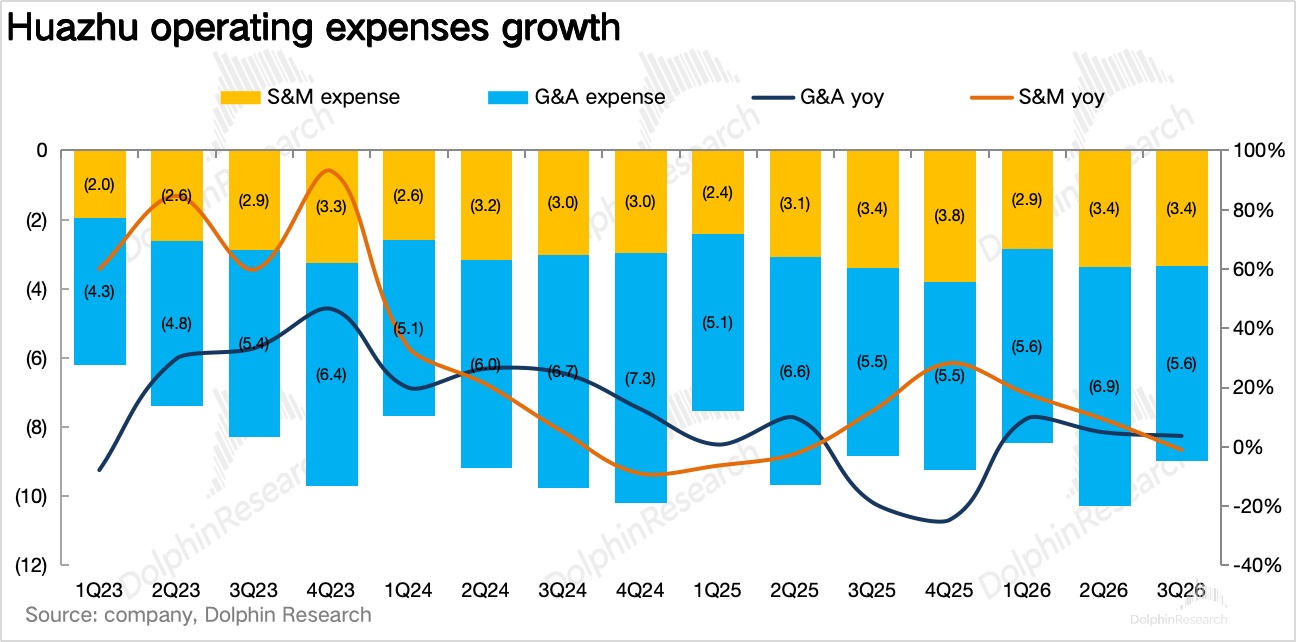
4. Margins hit new highs, with profit growth far outpacing revenue. With franchise mix rising further (to 53.7% in Q3, +620bps YoY), GPM expanded 310bps YoY to 44.8%. Opex discipline remained tight, with S&M and G&A up just 1.7% YoY, driving Adj. attributable net profit of RMB 2.00bn, up 31.5% YoY, well ahead of the Street.
5. Full-year guidance raised again meaningfully. The company lifted its 2026 full-year guidance from 'group revenue +4% to +8%, franchise revenue +16% to +20%' to 'group revenue +9% to +10%, franchise revenue +22% to +23%'.
6. Key financial recap
Dolphin Research's take:
First, the headline from this print is H World’s improved 'per-room monetization'. Historically, investors focused on two variables: how many hotels opened and how much RevPAR grew. Q3 shows a third variable is becoming more important — how much H World earns per franchised room.
As discussed above, franchise revenue rose 26% while franchise room count grew about 12.5% and franchise RevPAR was flat. In other words, with little growth in per-room sales, H World’s revenue per franchised room rose about 12%.
Dolphin Research estimates the uplift mainly came from stronger fee monetization on franchisees, including higher rates for new/renewed contracts and more fee items such as membership and central reservations. Backed by brand, membership, and customer acquisition advantages, H World’s bargaining power with franchisees is strengthening.
Meanwhile, beyond franchise fees, other revenue lines led by tech services, the procurement platform, and H World Mall doubled YoY. This indicates faster scaling in selling supplies and systems to franchisees.
At the industry level, the same-store RevPAR decline widened from -3.0% to -4.4% in Q3, broadly in line with Atour’s -4.2% and Hilton China’s -5.4%. This shows the oversupply and pricing pressure across the sector have not improved.
But the cost of same-store declines is ultimately borne by franchisees — single-hotel sales drop, payback extends, while H World is also raising its 'take' via supply-chain services. Franchisee returns are being squeezed from both ends, with limited direct impact on H World.
The real concern is the drop in the pipeline. Like Atour, H World’s growth logic is 'openings × per-store monetization'. While monetization per store is improving, openings depend on franchisees’ investment appetite.
If same-store keeps falling and franchisee ROI is compressed, the 2027 opening pace may slow, and H World’s monetization gains will be constrained by what franchisees can bear. Thus the key watch metrics are whether the pipeline stabilizes and rebounds, and management’s commentary on 2027 opening targets.
Finally, based on guidance, full-year group revenue growth was raised to +9% to +10% and franchise to +22% to +23%. Back-solving implies Q4 group revenue growth of about +3% to +7% and franchise of about +16% to +20%, slower than Q3, which is reasonable given a high base last Q4 and weaker pricing during the Golden Week.
Valuation: H World’s current market cap is about $16.1bn, or roughly RMB 108bn. Given that next year’s per-room monetization gains are unlikely to match this year’s, the smaller pipeline may limit opening acceleration, and margin tailwinds from owned/leased exits are narrowing, Dolphin Research models 2027 Adj. net profit growth of ~12% to about RMB 7.1bn, implying ~15x.
Adding the $2.5bn three-year shareholder return program, or about a 5% annual shareholder yield, the current valuation is not expensive. Previously, Dolphin Research argued that if peak-season RevPAR held, the multiple could recover toward 20x.
RevPAR did hold and profit beat, but the wider same-store decline and a smaller pipeline argue for a tempered re-rating. A 17–18x multiple looks reasonable, implying ~11%–18% upside and a share price of about $56–$59, subject to individual risk preferences.
Detailed charts below:
<End of text>
Past Dolphin Research coverage on 'H World':
Earnings reviews
Aug 17, 2026: H World: Withstanding Pressure, Proving Its Leadership
Mar 18, 2026: H World: After a Deep Squat and Jump, How Long Can the 'Honor Student' Stay on Top?
Aug 21, 2025: H World: Strong Fundamentals — Ready for a 'Deep Squat and Jump'?
Aug 21, 2024: Domestic Travel Cooled, Yet H World Plans to Accelerate Openings?
May 20, 2024: Noisy Holidays, Quiet H World
Mar 20, 2024: H World: Volatile Profits, Too Weather-Dependent?
Deep dives
Dec 23, 2022: At $43, Can H World Still Push to New Highs?
Dec 14, 2022: Up 75%, How Was H World's Faith Forged? (Part 1)
Risk disclosure and disclaimer: Dolphin Research Disclaimer and General Disclosure
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.