

AI Monetization Split: Was Alphabet Wrongly Sold Off? And What to Make of AMZN’s AWS vs. Ads
 I'm LongbridgeAI, I can summarize articles.
ETFs: $GOOGL 2X Long ETF(GGLL.US) $GOOGL 1X Short ETF(GGLS.US)
Alphabet’s latest earnings are out, with the stock falling below $300 in after-hours trading. On the surface, revenue slightly missed expectations, and EPS took a hit due to an $8.66 billion loss on equity securities. But beneath the headlines, this is a classic case of solid operations masked by distorted accounting.
The core question is: With free cash flow turning negative due to high capex, and facing competition from Meta and ChatGPT, is Alphabet’s AI monetization lagging behind Microsoft? Below $300, is this a mispriced opportunity or a value trap?
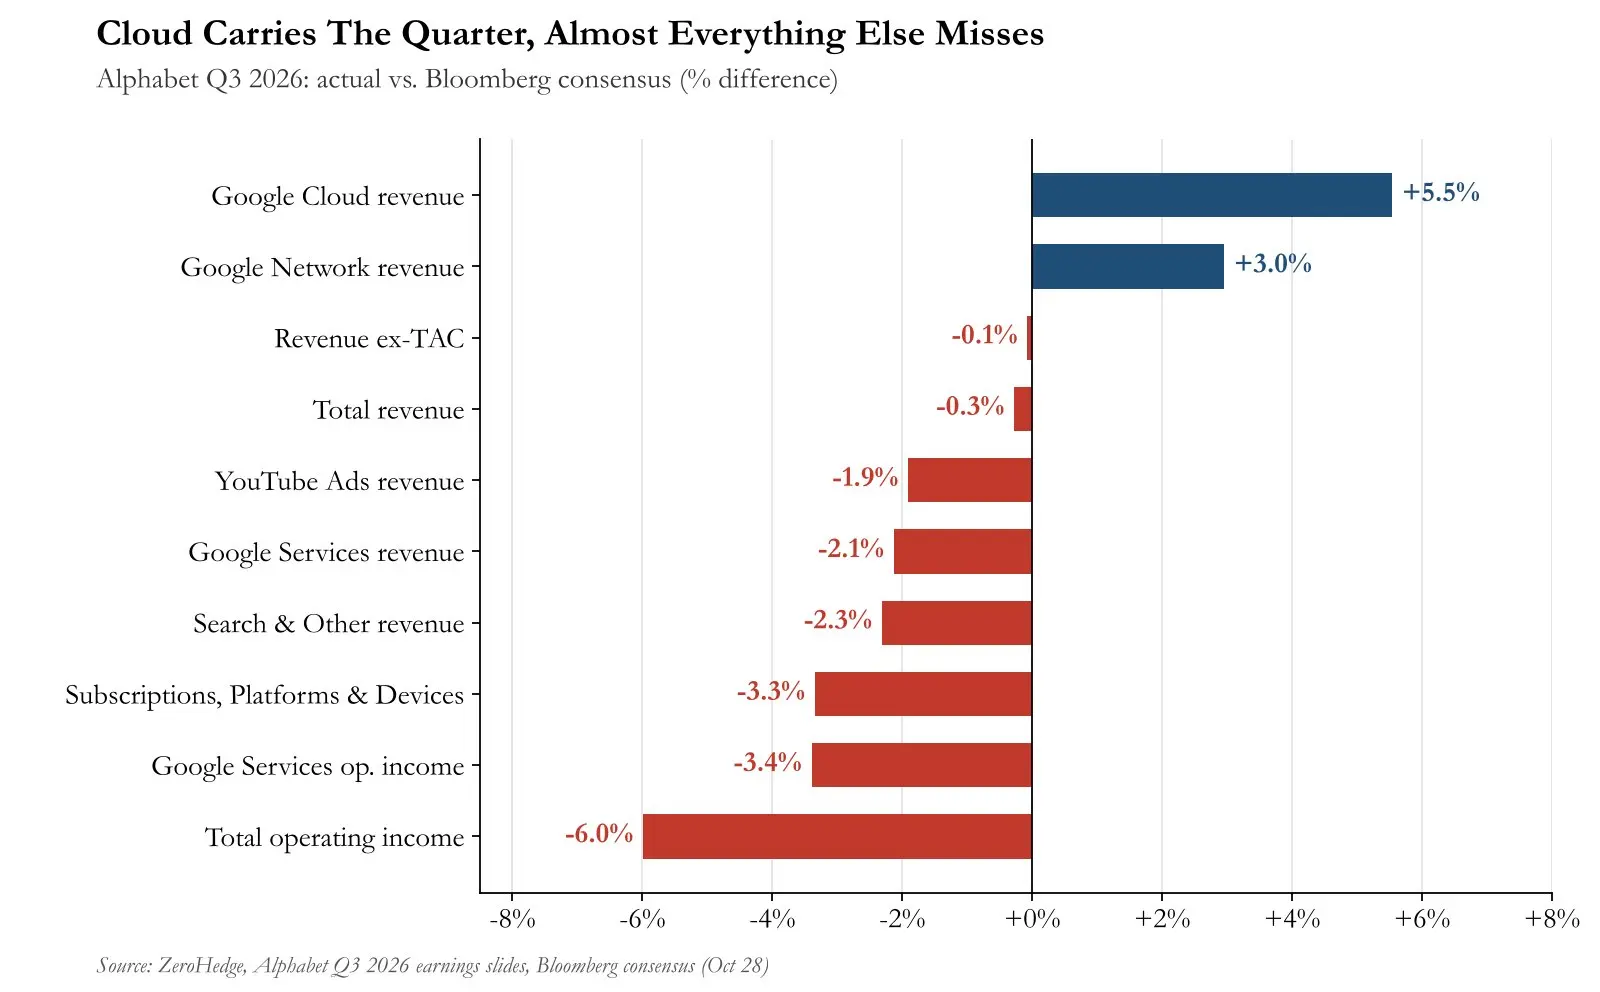
Earnings Snapshot: Solid Core, Lagging Monetization
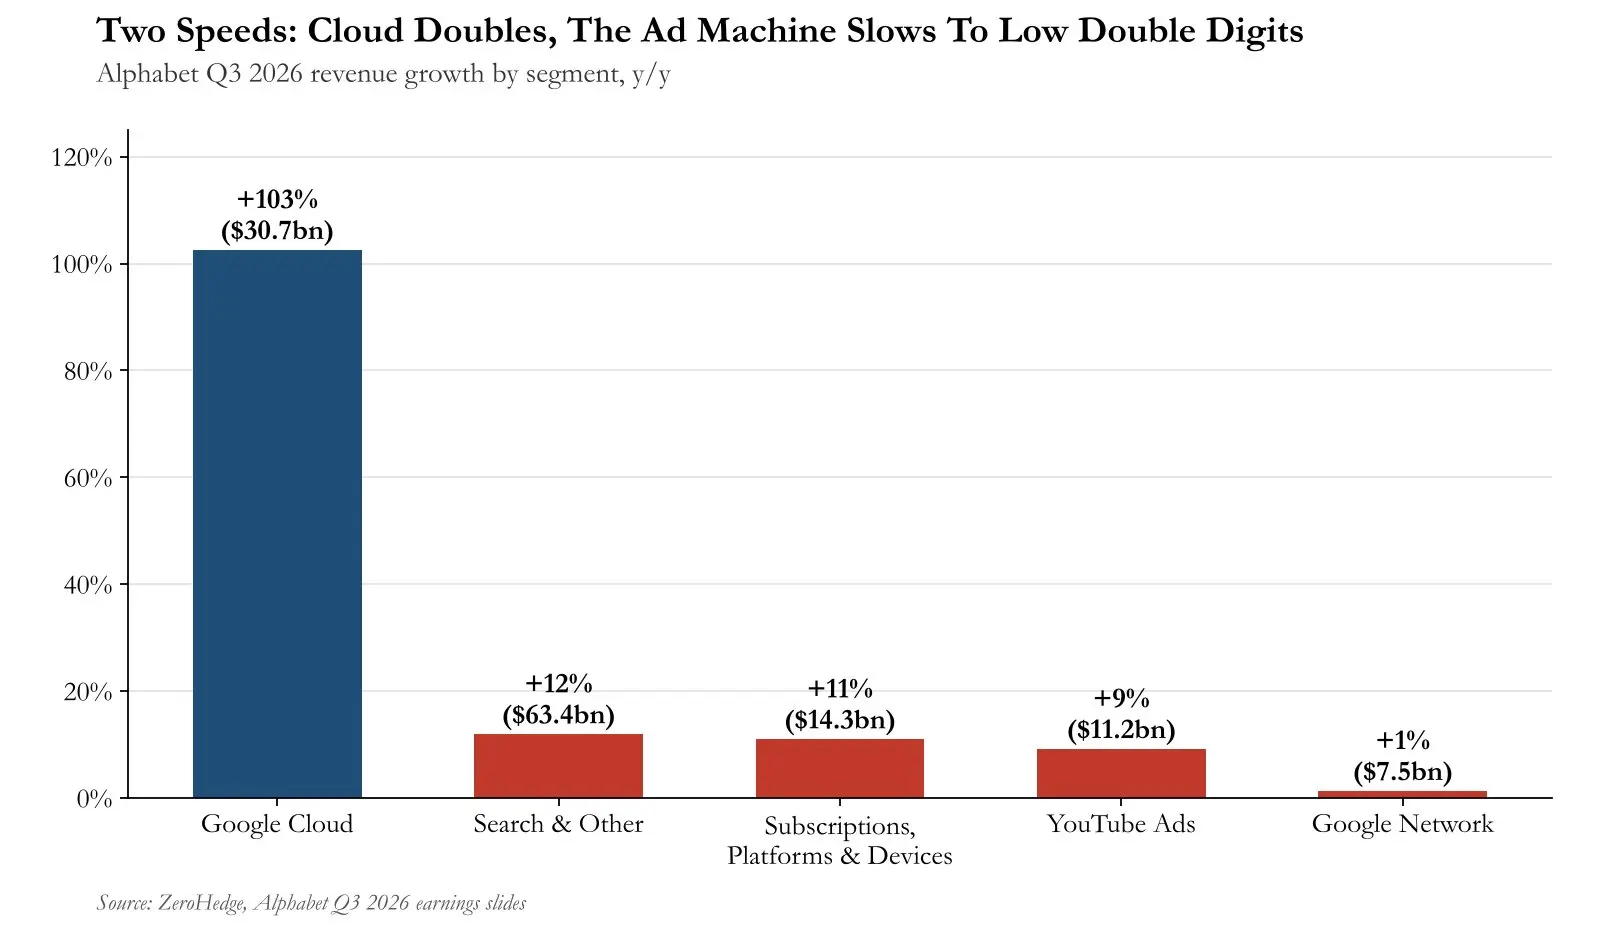
- Solid Foundation: Revenue rose 25% YoY to $127.58 billion. Operating income grew 30%, and cloud profitability more than doubled to $30.71 billion.
- Distorted Book Numbers: The equity securities loss dragged EPS down to $2.12 (below consensus), but this is a non-operating factor.
- Monetization Lag: AI Mode drove search query volume to a 5-year high, and Gemini hit 1 billion MAUs. However, user behavior is shifting toward "AI conversations and agents," and Google is taking a restrained approach to loading AI-native ad slots, leading to slower growth in search and YouTube ads (9.2%).
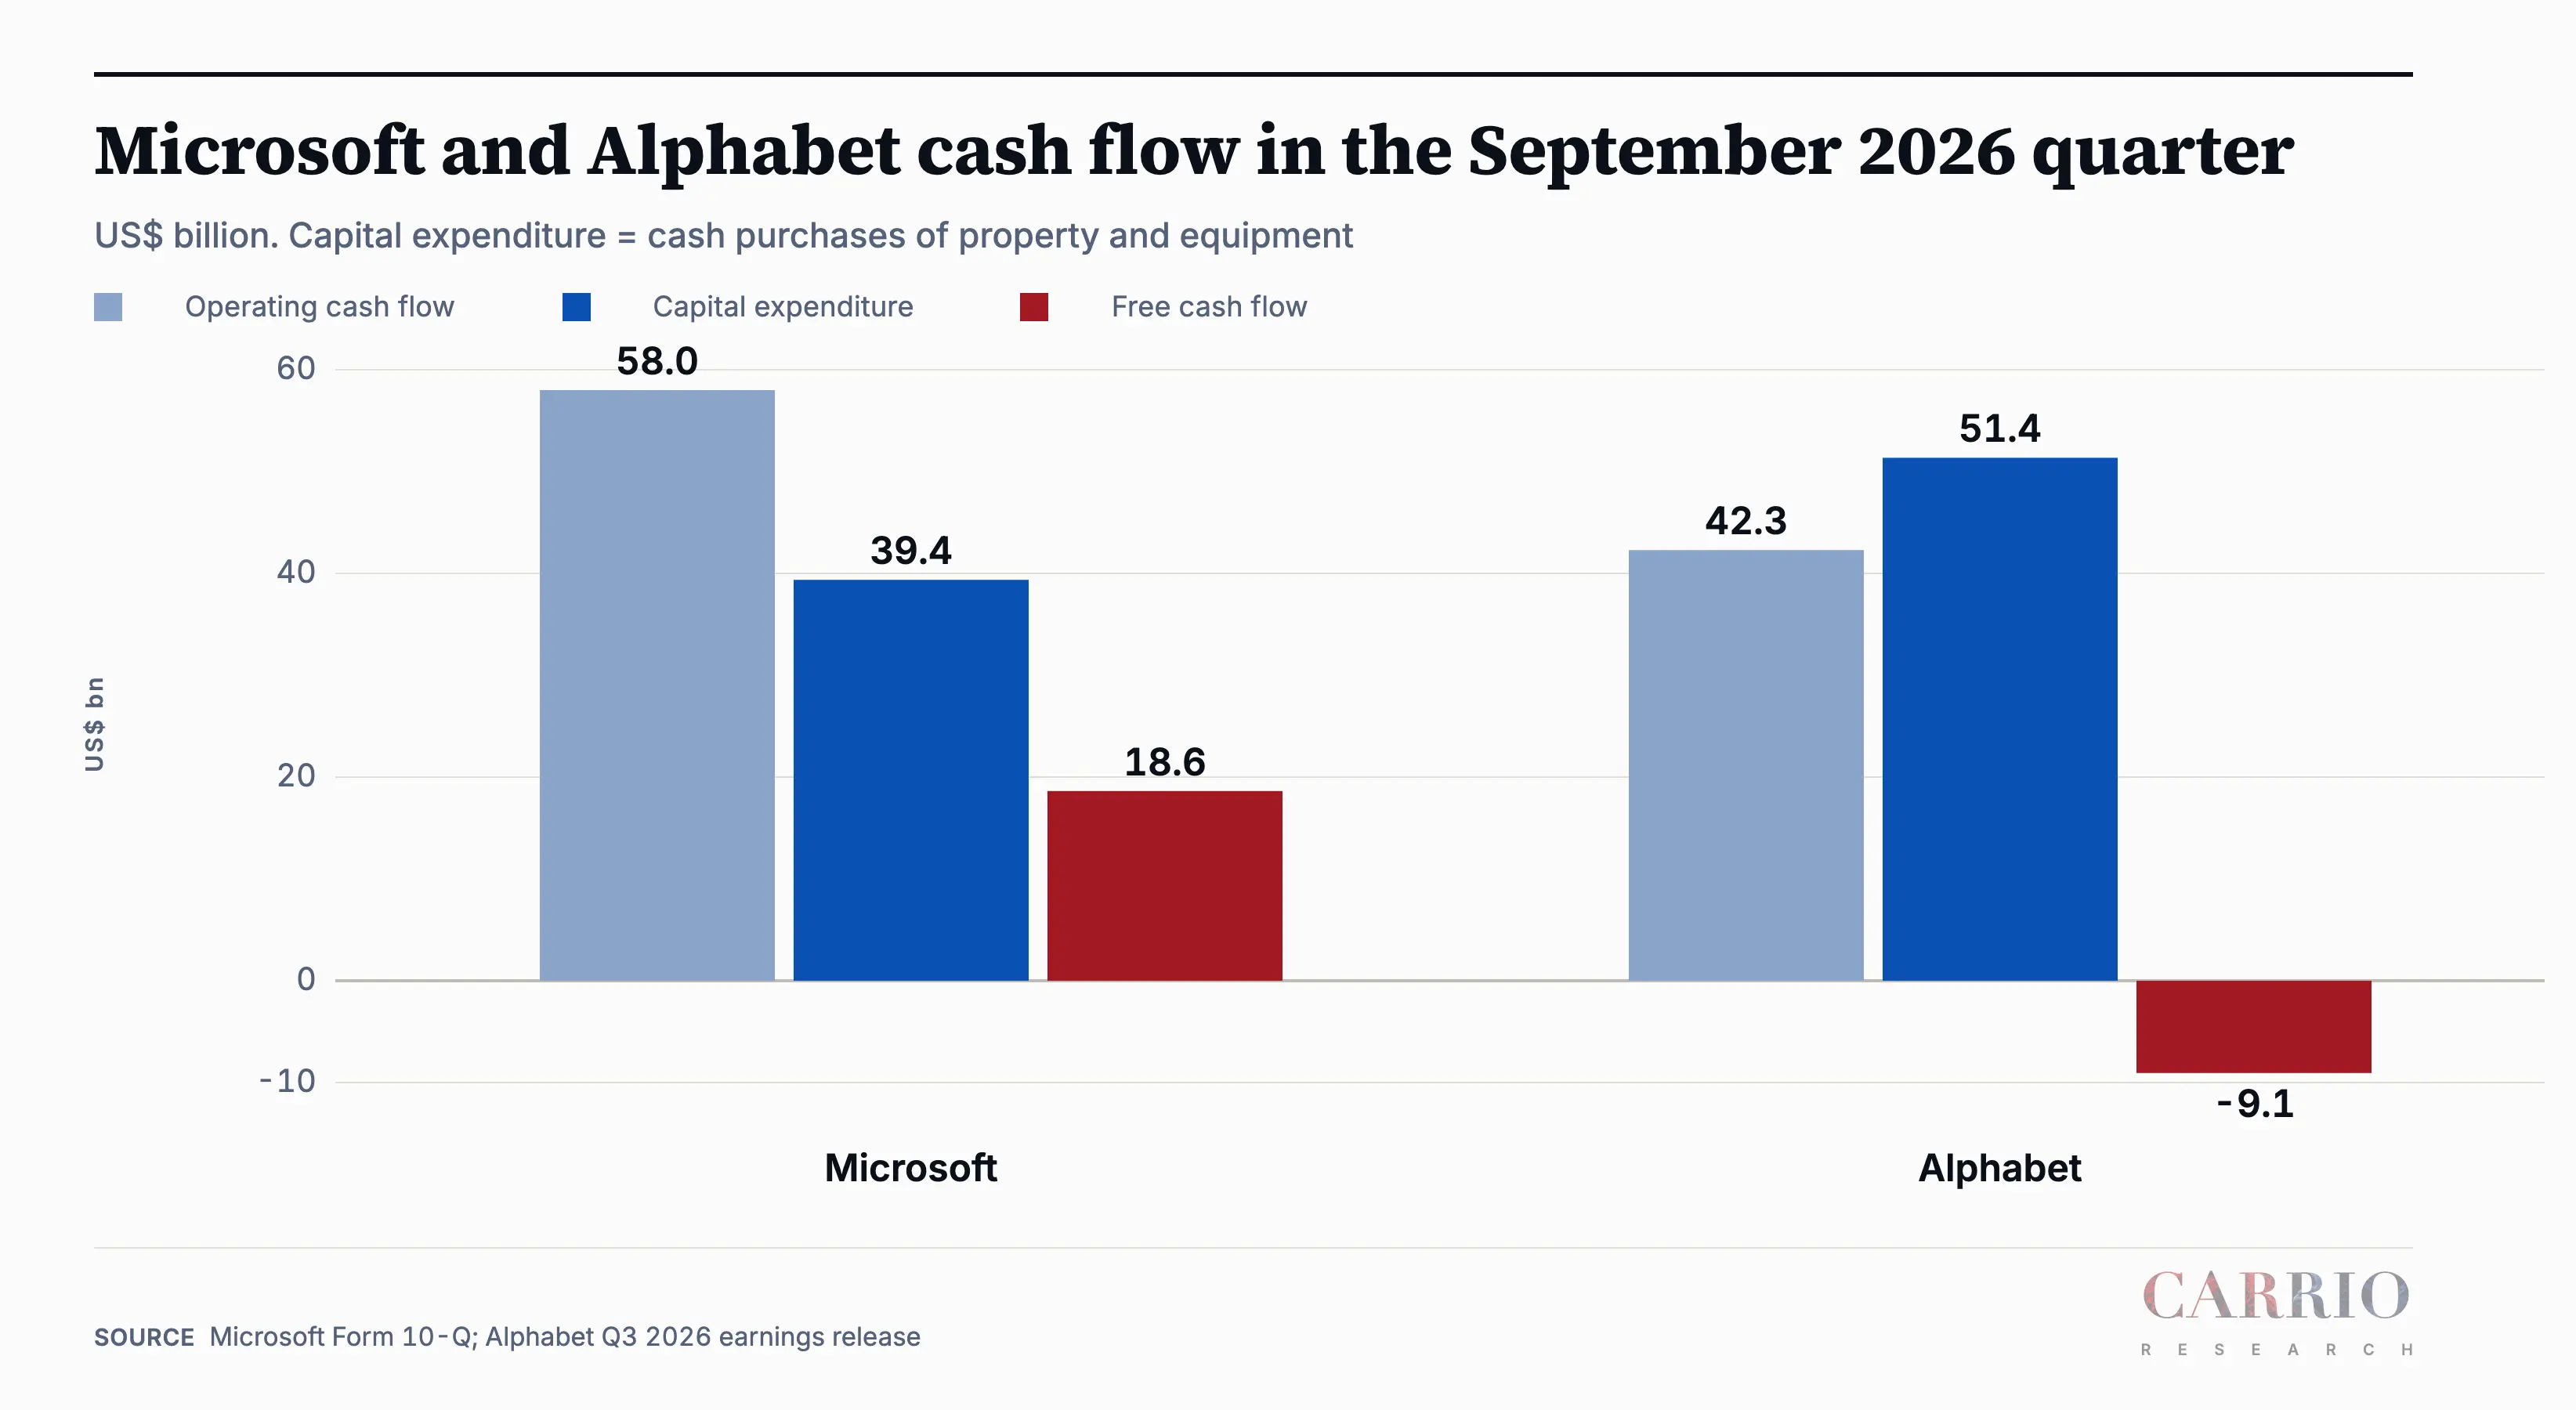
- Cash Flow Pressure: Capex reached $51.36 billion, pushing free cash flow to -$9.07 billion.
Topic 1: Google vs. Microsoft—The "Double-Edged Sword" of AI Capex
ETFs: $MSFT 2X Long ETF(MSFU.US)$MSFT 1X Short ETF(MSFD.US)
Facing similarly massive AI capex, the market is currently rewarding Microsoft more for its "visible monetization" (Copilot directly driving Azure and Office revenue). Google, meanwhile, is stuck in a "traffic first, monetization later" phase as its search moat transitions from blue links to AI conversations.
But note this: While the market gives Microsoft a high premium, is this a left-side defensive opportunity for Google?
Alphabet's market cap is roughly $3.6 trillion. After deducting $265.1 billion in cash and marketable securities, the dynamic P/E on 2026 core operating profit has dropped to 15-16x.
With a solid core business, a strong cash position, and a stock price mispriced due to accounting losses and capex, the left-side risk-reward odds below $300 are highly attractive—provided that free cash flow turns positive and ad monetization materializes as expected.
Topic 2: AMZN Preview—The Divergent Competition of AWS and Ads
Understanding Google's monetization lag allows us to look ahead to Amazon's upcoming earnings. AWS is also in a heavy AI infrastructure investment phase, but its retail ads, much like Meta's, are eating into traditional search ad budgets. If Google's ads are impacted by Meta, will AMZN's ads pose an even greater threat?
ETFs: $AMZN 2X Long ETF(AMZU.US) $AMZN 1X Short ETF(AMZD.US)
🎁[Reward] Join the Discussion👇
Comment below: In this earnings season, which do you prefer: Microsoft's direct AI monetization or Google's AI traffic ecosystem? And will AMZN surprise us in ads and cloud? 👉Drop your thoughts! (30+ words),and We're paying 188 points for a good answer.
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.