
ContextAmazon is transitioning from a traditional e-commerce giant into a leading global AI infrastructure powerhouse. W…
Context
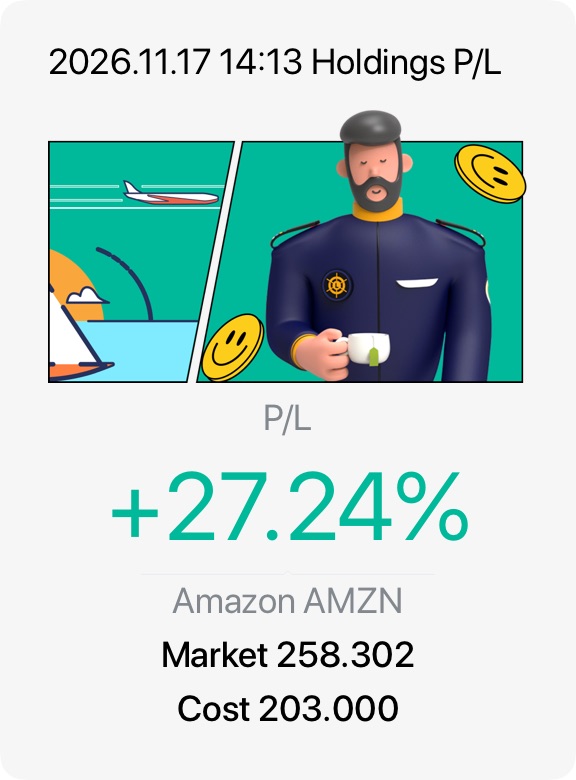
Amazon is transitioning from a traditional e-commerce giant into a leading global AI infrastructure powerhouse. While headline numbers for Q3 2026 slightly missed estimates, underlying metrics show Amazon Web Services (AWS) accelerated to a massive 39% revenue growth rate, marking its fastest expansion in nearly five years. Short-term headwind pressures from a recent 40-satellite launch failure and tightening U.S. AI chip export restrictions have dropped the stock to $257.75, presenting a highly strategic pullback entry point.
My trade
• Action: Accumulate shares on current pullback dips below $260.
• Stop Loss: Strict execution close under $230 (the post-earnings structural support floor).
• Target 1: $287 (testing the previous 52-week structural high resistance).
• Target 2: $322 (aligning with the current 12-month average analyst price target).
Takeaway
The structural thesis for Amazon remains fully intact because you want to own the digital landlord that everyone else must rent computing power from. Near-term news regarding satellite deployment delays provides a tactical entry to buy institutional-grade cloud acceleration at a discounted multiple. Monitor the upcoming Nvidia earnings and Anthropic IPO momentum to gauge immediate sector volatility.
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.