
NVIDIA (NVDA) is caught between explosive operational growth and severe leadership and regulatory turmoil, trading near …
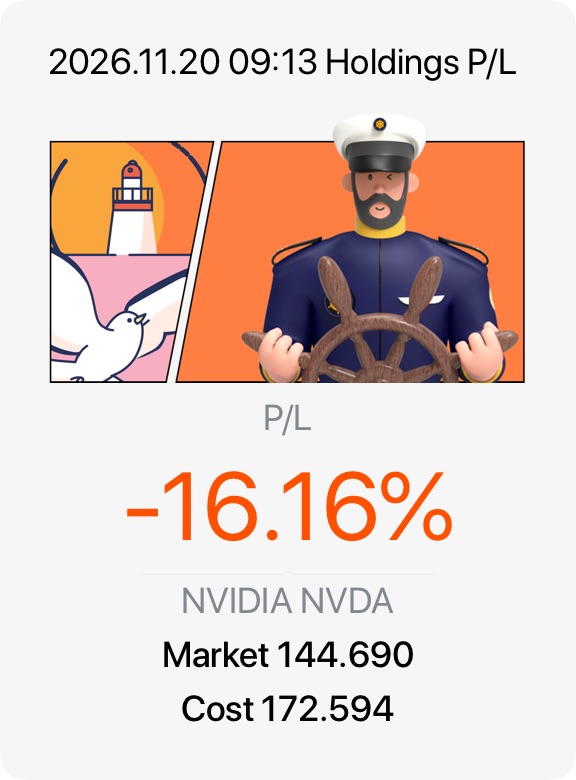
NVIDIA (NVDA) is caught between explosive operational growth and severe leadership and regulatory turmoil, trading near its 52-week low despite record earnings.
Bull Case (Fundamentals & Valuation)
• Record Q3 FY27 Results. On November 17, 2026, NVIDIA reported revenue of $115.8 billion (up 103% year-over-year) and non-GAAP EPS of $2.68, beating estimates.
• Strong Outlook & Product Ramp. Management guided Q4 revenue to ~$130 billion, fueled by the new Vera Rubin platform generating nearly $20 billion in its first shipping quarter—the fastest ramp in company history.
• Compressed Valuation. Following a ~40% pullback from its October peak of $243.37, NVDA trades at a trailing P/E under 16x and carries a fresh $150 billion share buyback authorization. Wall Street maintains a “Moderate Buy” consensus with an average price target above $243.
Bear Case (Governance & Macro Risks)
• CEO Departure & Probes. Co-founder Jensen Huang abruptly resigned on November 12 amid reports of a foreign intelligence inquiry, leaving CFO Colette Kress as interim CEO. The board confirmed Huang will not be reinstated, while SEC and state probes add legal exposure.
• Margin & Macro Pressure. Q4 gross margins are guided slightly lower to 71%–72% with zero China data-center revenue assumed. Rising 10-year Treasury yields above 5% and potential Fed rate hikes further compress tech multiples.
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.