D
 +4
PDD: A Rare Comeback Amid China Tech’s Earnings Rout
Temu’s scale-back is unlocking profits.
PDD’s bottom appears in place.+4
Temu’s scale-back is unlocking profits.
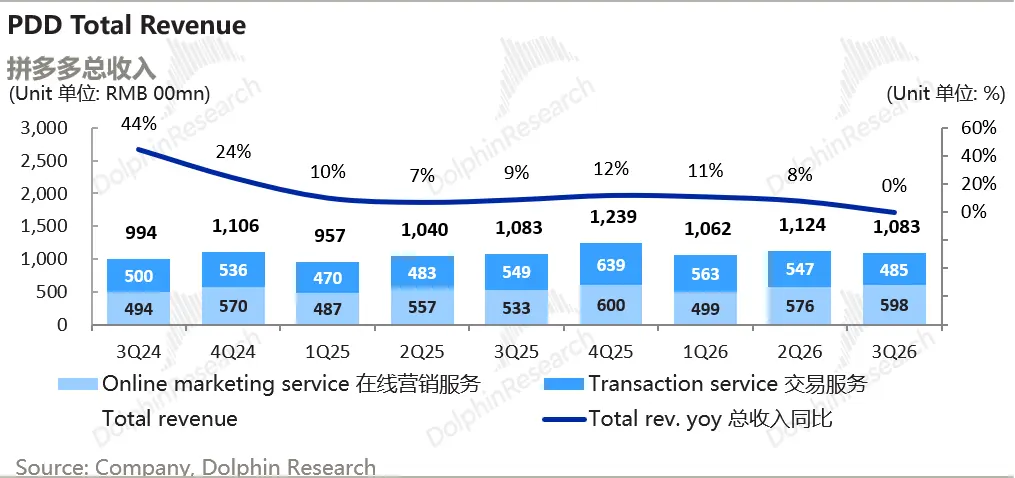
PDD’s bottom appears in place.+4Q3 revenue was RMB 108.3bn, flat YoY. The Non-GAAP opex ratio fell 400bps YoY to 28%.
However, management cautioned that a single-quarter expense ratio should not be extrapolated, and the RMB 100bn support program remains in the strategic investment phase. With overseas trade and tax rules shifting, they plan to step up local fulfillment and supply-chain capabilities.
PDD, also in its 'aging-up' phase, released Q2 2026 results pre-market on Aug 24. Overall, results were better than the very low bar. The rebound was driven by ad revenue and a meaningful recovery in core marketplace profitability.
Specifically: 1) Revenue miss? Ad revenue rebounded.
Total revenue rose 8% YoY, below Bloomberg consensus of ~11% (bulge-bracket houses were even lower), and growth further slowed QoQ. At first glance, it looked like another growth bomb, briefly rattling the market pre-open...
Q2 revenue was RMB 112.4bn (+8% YoY).
Spend under the RMB 100bn support initiative and ongoing platform governance compressed attributable net income to RMB 27.2bn (-12% YoY), while R&D expense rose 40% YoY.Management acknowledged the early rollout of self-operated brands was slower than expected, explicitly exited on-demand retail, and provided no guidance on full-year consumption or platform revenue.This week, $PDD(PDD.US) posted disappointing results, sending the stock down nearly 15%.
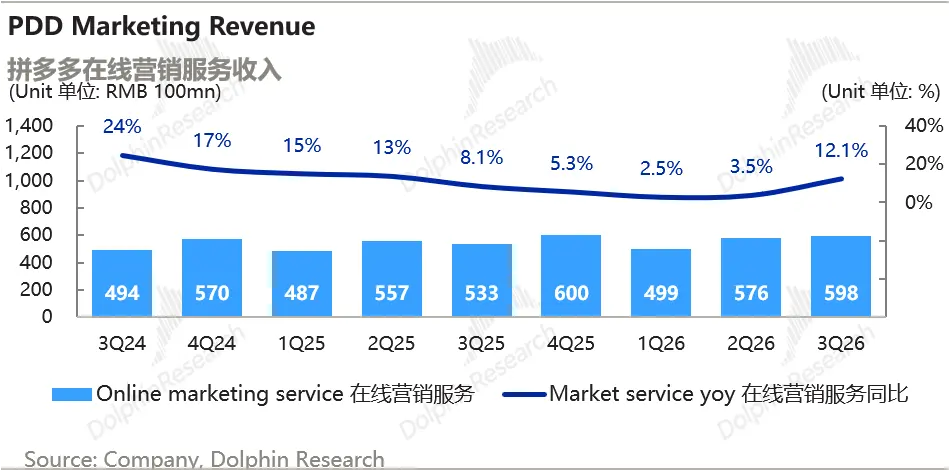
For a detailed take, see 'PDD: Old and Arrogant, Now Universally Disliked'. The most glaring issue: ad revenue grew just 2.5% YoY. Despite sector-wide improvement vs. Q4 last year, PDD's ad growth declined QoQ, making it the laggard among e-commerce peers...Below is Dolphin Research's Trans of $PDD(PDD.US) FY1Q26 earnings call (qtr ended Mar 31, 2026). For our take, see 'PDD: Old and arrogant, disliked by everyone'.
I. Core earnings takeaways: 1) Shareholder returns: management mentioned no dividend or buyback plans this quarter.2) Guidance: management gave no specific revenue/profit guidance for next qtr or the full year. They repeatedly cited seasonality and the pace of investment.$PDD(PDD.US) Pre-mkt on May 27, released Q1 2026 results, with both revenue and profit missing expectations, making it the worst performer in the e-com group.
1) Growth weakened against the trend: unlike the sector and peers that showed QoQ improvement, PDD’s revenue growth slowed vs. last quarter. Total revenue rose 11% YoY, below the 13.5% consensus and lower than Q4’s 12%.More notably, the shortfall was in ad revenue, up only 2.5%...Below is Dolphin Research's summary of the FY25 Q4 earnings call for $PDD(PDD.US).
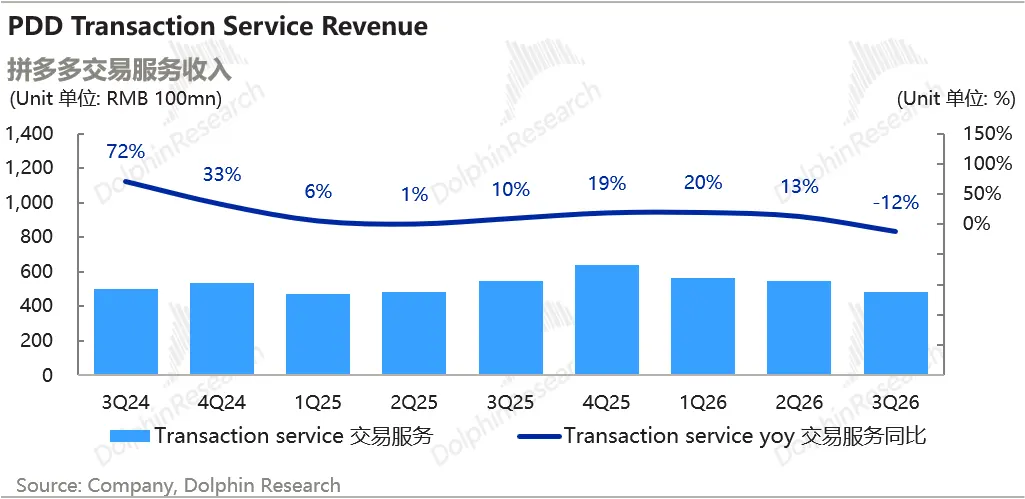
For our earnings take, please see 'PDD: Has the 'maniac' turned 'mediocre'?'.1) Slower topline growth: Q4 revenue RMB 123.9bn (+12% YoY); FY revenue RMB 431.8bn (+10% YoY). Within that, online marketing services were up just 5% YoY in Q4, while transaction services rose 19% YoY.2) Margin pressure. Q4 non-GAAP OP was RMB 29.5bn (OPM 24%...)Pre-market tonight (Mar 25), $PDD(PDD.US) released Q4 2025 results. Once the year's wild card on earnings, the company has now delivered two straight quarters broadly in line with the Street. PDD is now arguably the most focused, pure-play, value-driven e-commerce player in China.
In detail: 1) Total revenue growth showed some recovery, weak at home and strong overseas. Revenue came in at approx. RMB 123.9bn (+12% YoY), roughly in line with expectations. Growth accelerated vs. last quarter, with a softer domestic contribution (Q4 was weak across e-com) ...
The following are the Minutes of the 3Q25 conference call for $PDD(PDD.US) organized by Dolphin Research. For the financial report commentary, please see "Pinduoduo's Embarrassment: Rapid 'Aging,' but No Buyback." I. Review of Core Financial Information 1. The company's total revenue for this quarter increased by 9% year-on-year to RMB 108.3 billion, mainly driven by growth in online marketing services and transaction services. 2. Revenue from online marketing services and other businesses reached RMB 53.3 billion, up 8% year-on-year; transaction service revenue was RMB 54.9 billion, up 10%...