

XPeng: VW Windfall Fades, Car Sales Near a Turning Point?
 I'm LongbridgeAI, I can summarize articles.
XPeng released Q3 results after HK close and before US open on Nov 16, 2026 Beijing time. Headline beats were clear: revenue, vehicle GPM, and net loss all came in better than expected. Most importantly, Q4 guidance midpoint for deliveries and revenue topped the Street. Specifically: $XPeng(XPEV.US) , $XPENG-W(09868.HK)
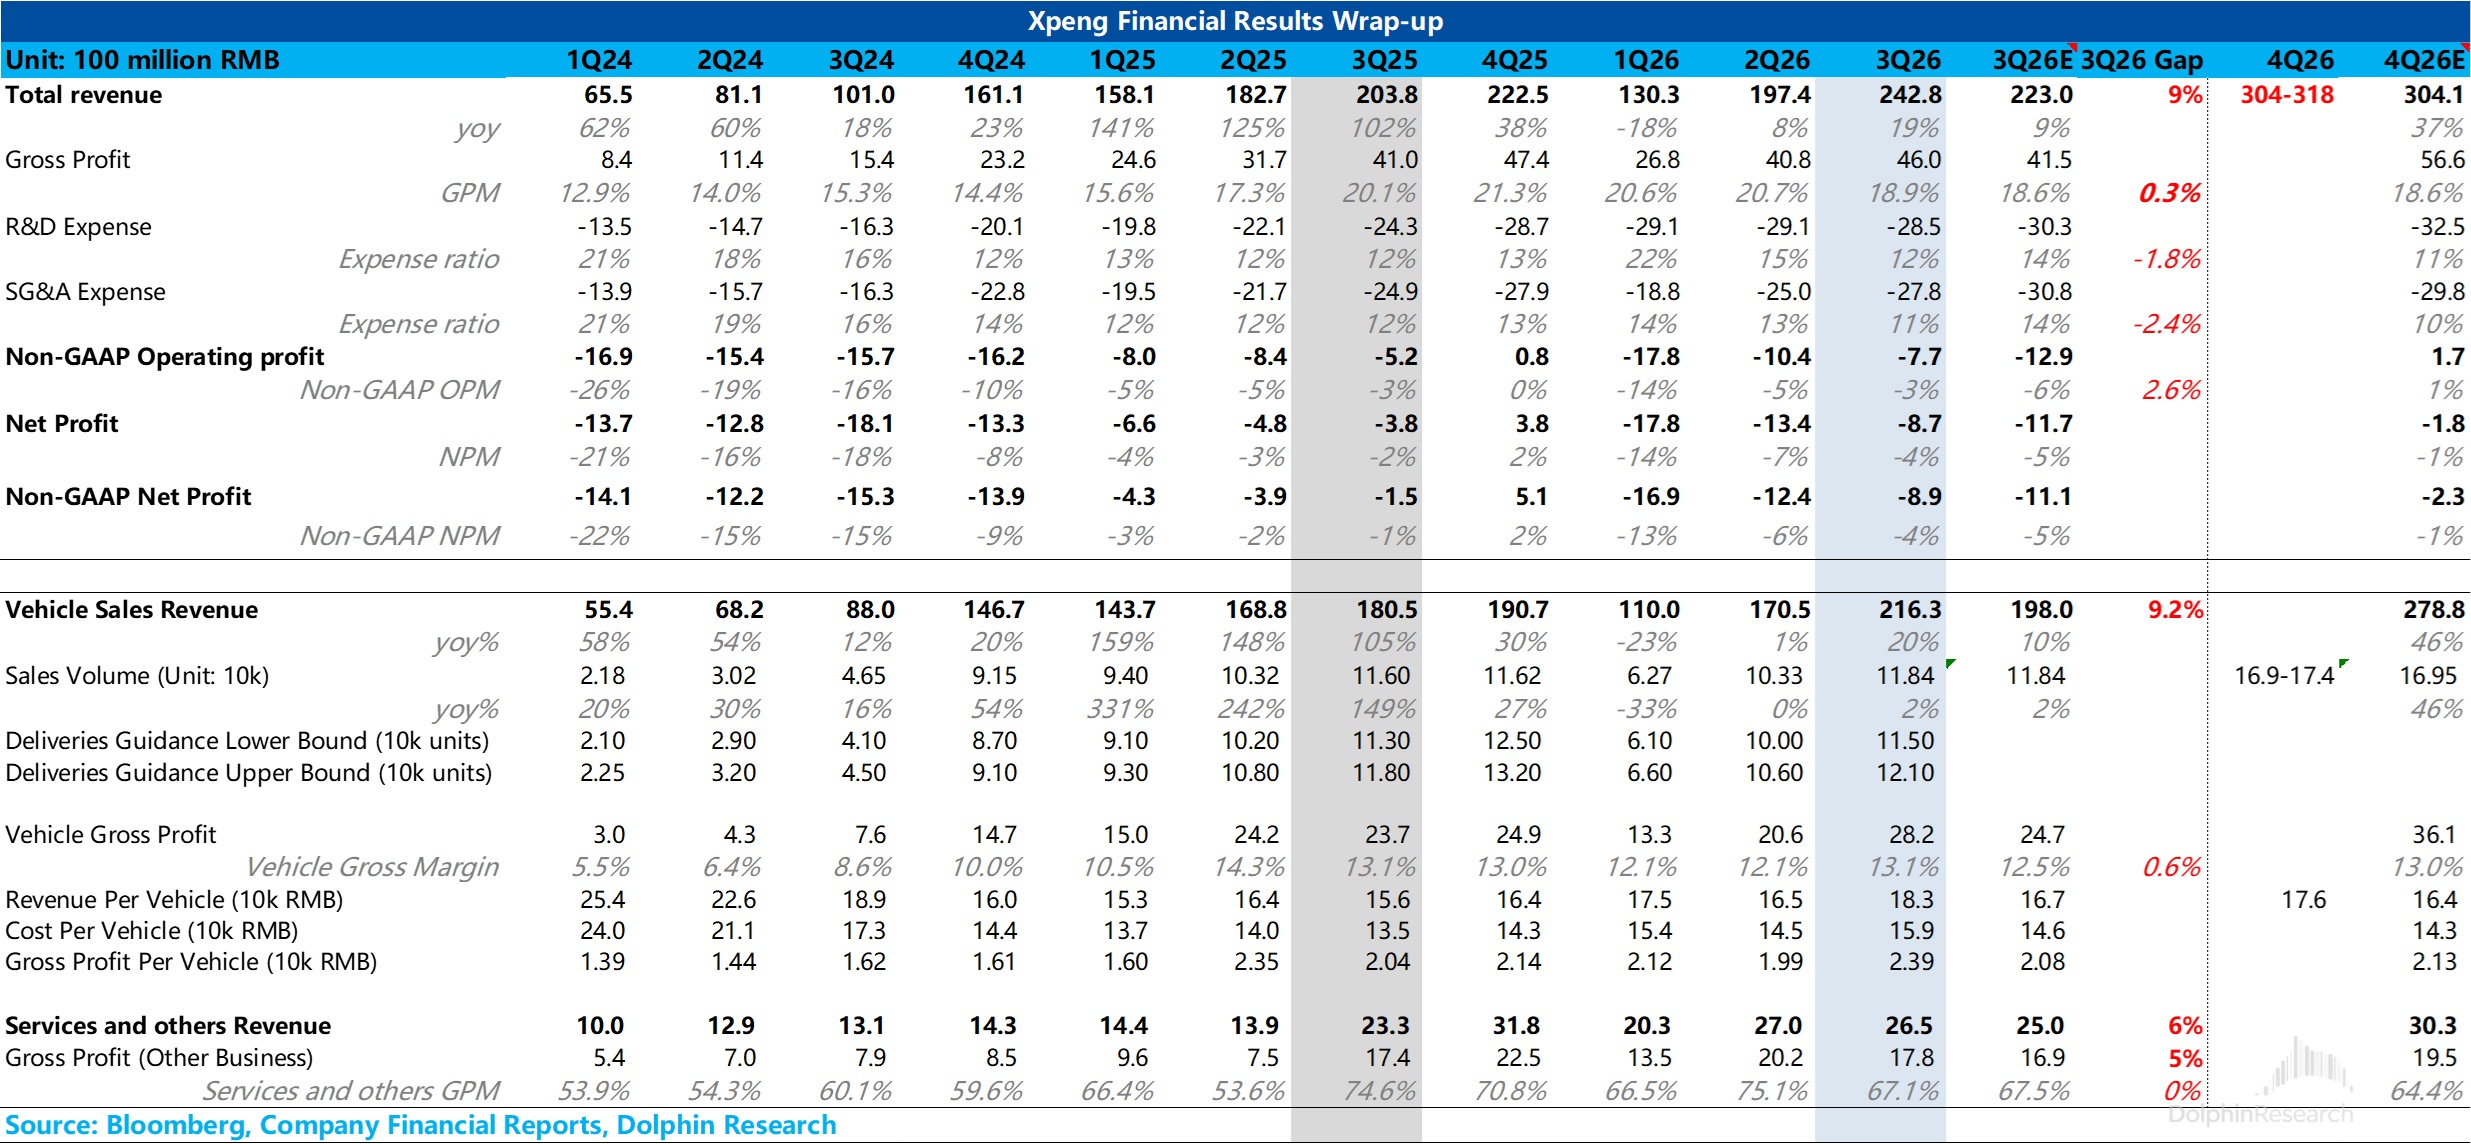
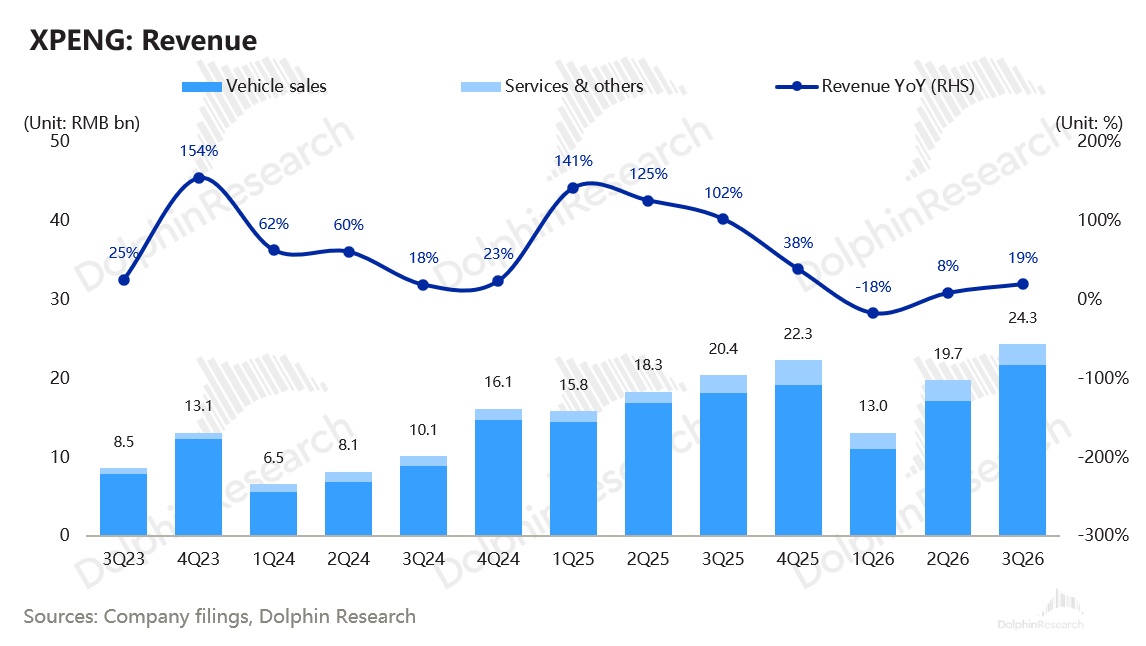
1) Total revenue beat: Q3 revenue was RMB 24.28 bn, up 19% YoY, about 7% above the Street at RMB 22.7 bn. It also exceeded the high end of company guidance (RMB 21.7–23.4 bn).
Service and other revenue was RMB 2.65 bn, down just RMB 50 mn QoQ and ahead of market expectations of RMB 2.50 bn. Milestone revenue from the VW tech R&D partnership moderated, but carbon credit income increased and partly filled the gap.
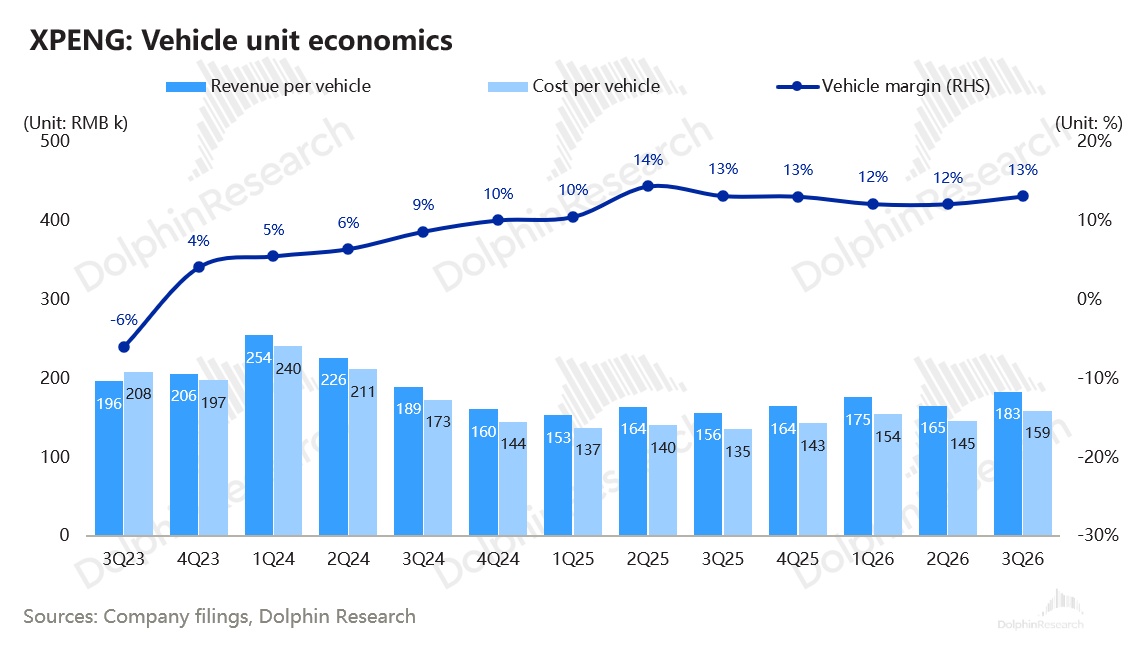
2) Auto revenue and ASP rebounded sharply: Vehicle sales revenue was RMB 21.63 bn (+20% YoY), about 9% above the Street at RMB 19.8 bn. ASP reached RMB 183k, up RMB 18k QoQ and well above the RMB 168k market expectation.
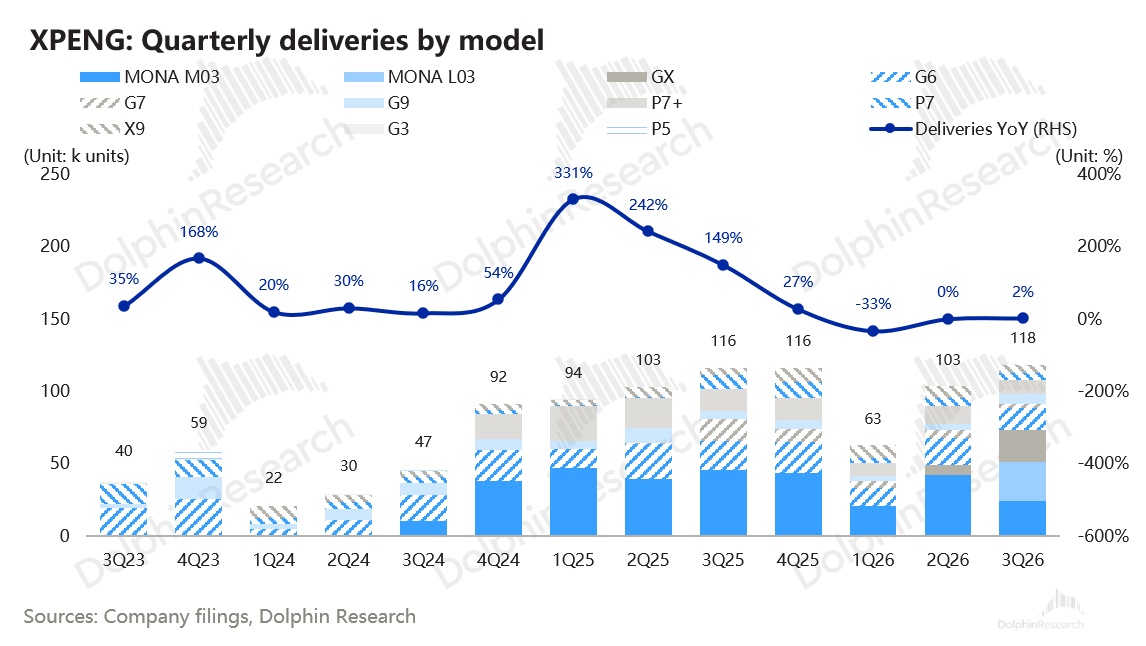
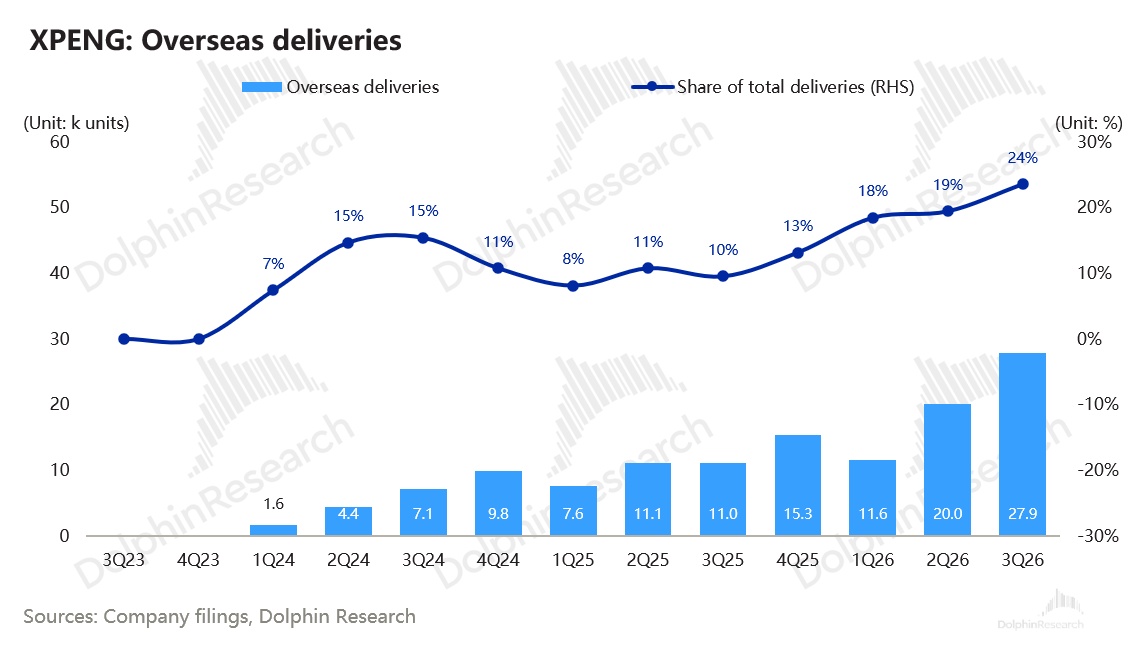
The ASP uptick was mix-driven: higher-priced GX entered a full delivery quarter, lifting mix from ~7% in Q2 to ~18%. Exports also rose from ~19% to ~24%. While lower-priced Mona mix increased, the drag was outweighed by premium models.
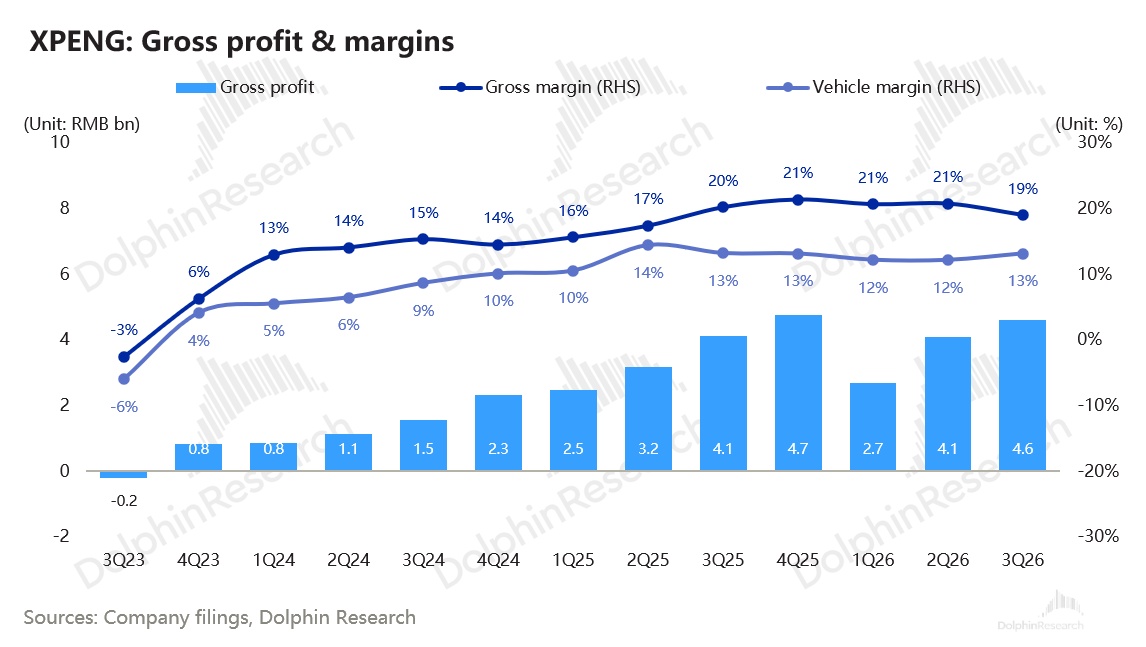
3) Vehicle GPM continued to recover and beat: Q3 vehicle GPM was 13.1%, +100 bps QoQ, above the Street at 12.5% and flat YoY.
Unit cost was RMB 159k, up RMB 14k QoQ, mainly due to mix shift toward higher-priced models. But cost rose less than ASP, as scale benefits (deliveries +15% QoQ) and lower cost from in-house Turing chips offset higher memory, battery and other materials, plus L03 ramp costs.
As a result, unit GP rose to ~RMB 24k, up ~RMB 4k QoQ, the highest in recent quarters.
4) Blended GPM dipped as VW service 'red envelope' faded: Blended GPM was 18.9%, down 180 bps QoQ but slightly above the Street at 18.6%.
The decline was mainly from services: recognition of high-margin tech R&D services fell, with service GPM down from 75.1% to 67.1%. Service GP was down by ~RMB 250 mn QoQ, partially offset by the vehicle GPM recovery.
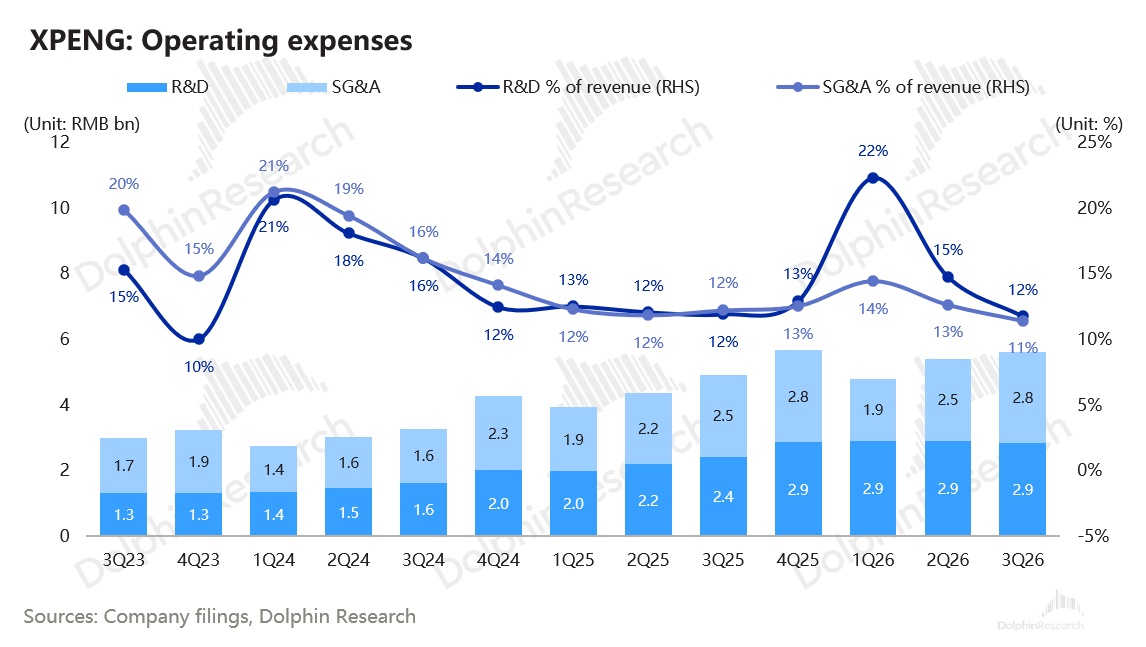
5) R&D down QoQ; S&M up on new launches: R&D was RMB 2.85 bn, down 2.1% QoQ and below the Street at RMB 3.03 bn, with R&D ratio down from 14.8% to 11.8%.
S&M was RMB 2.78 bn, up ~RMB 280 mn QoQ, driven by higher commissions to franchise stores on rising volume and marketing for G9L and Mona L05 launches.
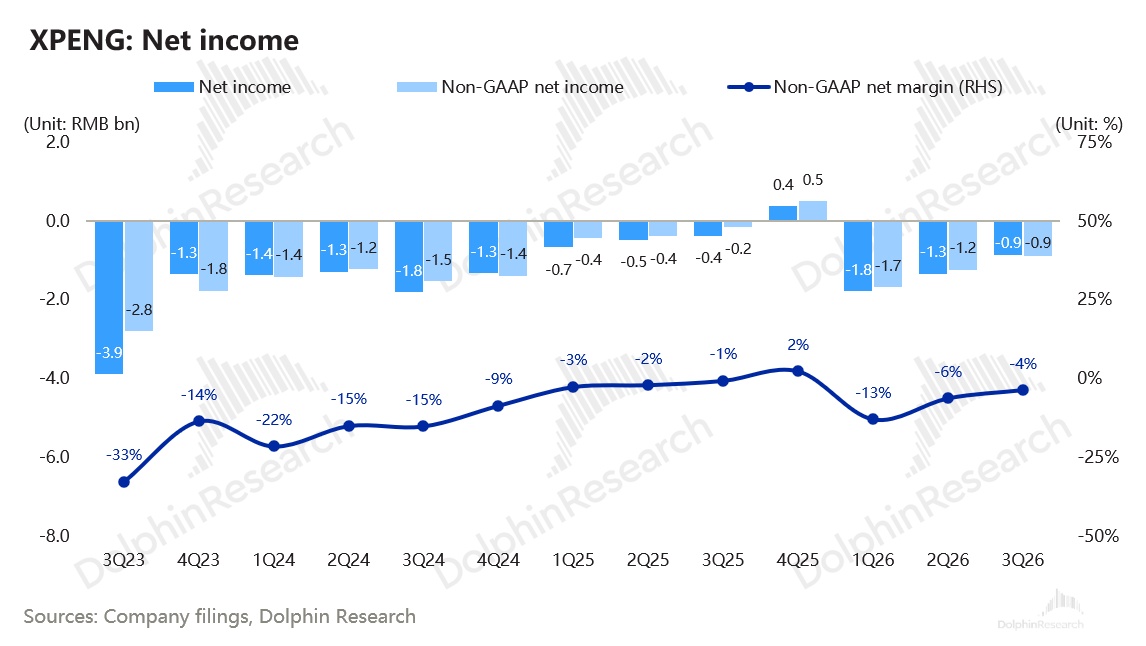
6) Narrower loss: Q3 net loss was RMB 870 mn, narrowing ~RMB 470 mn QoQ and beating the Street at RMB 1.17 bn. The improvement mainly came from ~RMB 770 mn higher vehicle GP, offsetting lower service GP and higher S&M.
Dolphin Research view:
Overall, XPeng delivered a clear beat this quarter, with Q4 guidance also above market expectations.
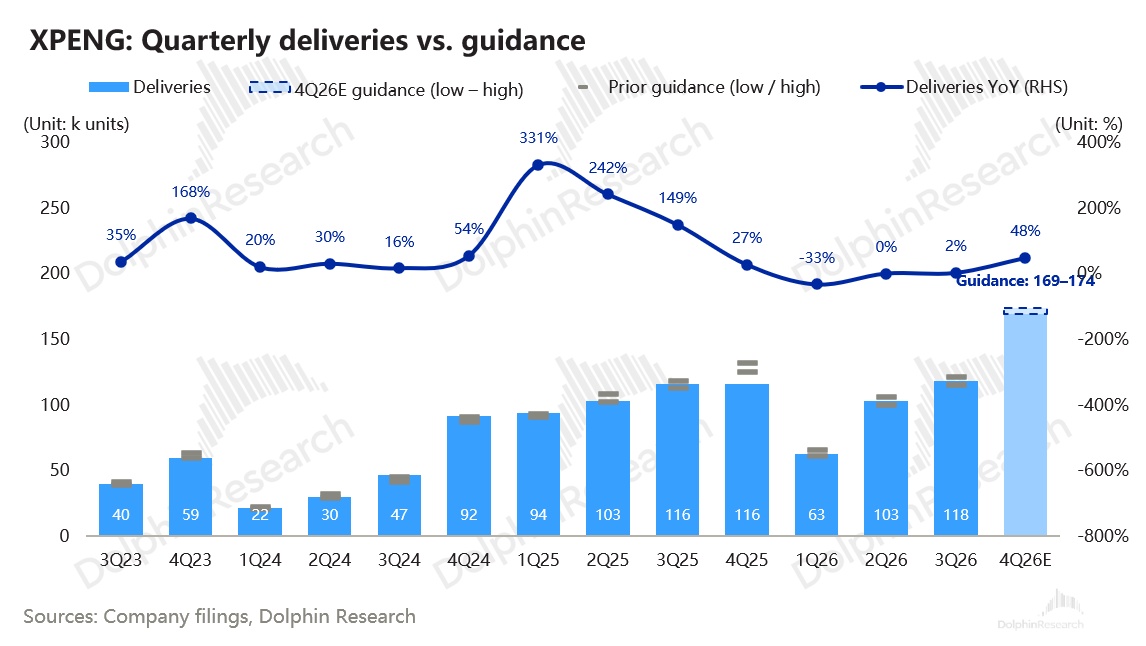
Since Q3 deliveries (118k units) were pre-announced, the focus this print was GPM and guidance.
The market had expected lower blended GPM from fading VW services, from 20.7% to 18.6%. Vehicle GPM was seen only slightly up to 12.5% on GX mix, constrained by pricier memory chips and commodities.
In reality, both came in better, and the upside was mainly from the core auto biz. The impact from lower services matched expectations, while GX-led mix, scale, and in-house chip savings offset raw material inflation.
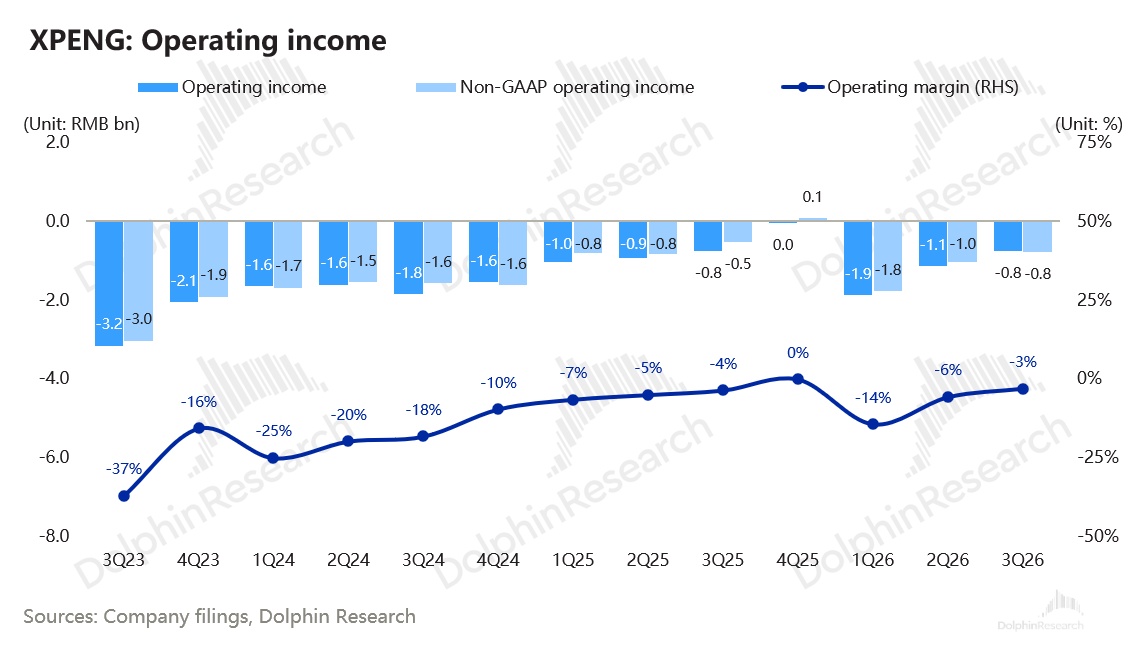
On profit, service GP fell ~RMB 250 mn and S&M rose ~RMB 280 mn, but auto GP rose ~RMB 770 mn. Core OP loss narrowed from RMB 1.33 bn to RMB 1.03 bn.
This shows that as the 'service-supported margin' fades, the auto biz is improving on its own profitability. That is the most important signal this quarter.
On the pivotal Q4 guidance:
1) Deliveries beat: Q4 guidance is 169–174k units, with midpoint above the Street at 169.5k. With 50k delivered in Oct, the implied Nov–Dec monthly run-rate is 59–62k, consistent with management's prior '60k+ per month' comment.
Upside drivers include L03 supply improvement (from Oct, ~20k/month potential), G9L's first full delivery quarter, Mona L05 launched on Oct 29, and L03 starting exports.
However, lead times remain long at 17–22 weeks for L03 BEV and 11–16 weeks for the EREV. Memory and in-house Turing chip supply remain bottlenecks. The 'around 60k/month' delivery guide suggests continued supply constraints.
2) Revenue guidance also beats: Q4 revenue guidance is RMB 30.4–31.8 bn, with the low end at Street. Assuming services at ~RMB 2.65 bn, implied ASP is ~RMB 165–168k, down ~RMB 15k QoQ as L03 and L05 scale, diluting premium mix.
Based on this, 2026 volume is ~453–458k units (+~6%–7% YoY) with revenue of RMB 87.5–88.9 bn.
Exports are the core growth engine: 13k units exported in Oct, a record. Management targets 40k exports in Q4 and ~90–100k for the year (doubling YoY). L03 exports have started, while GX, G9L, and L05 will go overseas in Q1 next year.
Domestically, four new SUVs underpin volume: GX, L03, G9L, and L05 cover key SUV segments. But with the above supply bottlenecks, order leakage risk remains.
On AI, XPeng is pushing from R&D to commercialization:
a. ADAS upgrade: OTA 6.3.0 in Sep introduced the 2nd-gen VLA, lifting on-car model parameters 3.5x and response speed by 300%, and deployed Master Agent in-car. Localization in Germany took about a week, with a target for EU regulatory approval in 1H27.
In-house Turing chips have fully replaced third-party AD chips.
b. Robotaxi secured L4 pilot license: On Oct 26, it received approval to conduct L4 Robotaxi demo operations across Guangzhou. Factory-fitted mass-production vehicles completed over 2,000 internal test rides in Guangzhou, with plans for driverless paid rides in 2027.
It will partner with ride-hailing platforms to scale across domestic and overseas cities.
c. Humanoid robots racing to mass production: The first automated line started in Sep, with IRON targeting mass production by year-end. A launch event is planned for Q1 2027, with external deliveries and revenue contribution from Q2.
Subsidiary Pengxing raised about $900 mn at a post-money valuation of $6.3 bn.
At 2026E volume of 453–458k units and revenue of RMB 87.5–88.9 bn, XPeng's current market cap of ~RMB 59.7 bn implies 0.68x 2026E P/S.
However, with only 1.5 months left in 2026, the market is already anchoring to 2027. On a conservative 2027 revenue estimate of ~RMB 95.7 bn (+<10% YoY), current valuation implies ~0.6x 2027E P/S.
At the industry level, NEV penetration in China is above 60%. Price wars and raw material inflation persist, driving multiple compression for new EV makers, with 2026E P/S mostly at 0.4–0.8x.
XPeng sits in the upper half of that range, with a premium largely tied to AI options such as robots and Robotaxi.
The robot subsidiary's post-money valuation is $6.3 bn. At XPeng's ~73.8% stake and applying a 20% liquidity discount for unlisted equity, its attributable value is ~$3.7 bn (~RMB 24.9 bn at $1=RMB 6.70), about 42% of current market cap.
Dolphin Research does not believe the secondary market will mark the full RMB 24.9 bn into the stock:
a. $6.3 bn is a single-round primary valuation, typically with investor protections such as liquidation preference and buybacks. Common equity value is lower.
b. The robot biz currently has no revenue and only R&D expense, which drags XPeng's profit when consolidated.
c. Mass production and external deliveries are yet to be realized.
Until IRON ships externally or the robot biz is refinanced/spun off with public pricing, the market is more likely to treat it as a discounted 'option'.
Thus Dolphin applies SOTP: core auto (including services and tech licensing) valued on 2027E P/S, and robots included at a fraction of RMB 24.9 bn:
Base case (preferred): core auto at 0.5x 2027E P/S (~RMB 47.9 bn), robots at 50% (~RMB 12.5 bn), totaling ~RMB 60.3 bn, broadly in line with current market cap.
Bull case: core auto at 0.6x (~RMB 57.4 bn), robots at 100% (~RMB 24.9 bn), totaling ~RMB 82.3 bn, ~+38% vs. current price, equivalent to ~0.86x 2027E P/S overall.
Prerequisites include IRON shipping on time externally, or robot biz refinancing/spin-off with public pricing, and Robotaxi entering paid ops.
Bear case: core auto at 0.35x (~RMB 33.5 bn), robots at 30% (~RMB 7.5 bn), totaling ~RMB 41.0 bn, ~-31% vs. current price.
This would require vehicle GPM falling back below 12% in Q4, 2027 volume guidance missing, and robot mass production delayed. After Q3 prints, Dolphin sees lower probability of this scenario.
Near-term, rerating hinges on sustaining 60k monthly deliveries in Nov–Dec, IRON hitting year-end mass production, holding vehicle GPM at or above 12.5% amid ASP pressure in Q4, and management's guidance on 2027 volume and breakeven.
Medium-term upside comes from IRON external deliveries, Robotaxi moving from pilots to paid ops, VLA deployment in Europe, and scaling of four new SUVs plus exports. These validate AI 'options' converting into revenue.
A robot biz refinancing or spin-off IPO would provide a public reference price, shifting the robot value from 'discounted' to 'fully included' in valuation. This is the most direct bull trigger.
Below is the main text:
I. Vehicle GPM beat
Q3 deliveries were 118k units, mid-range of company guidance (115–121k), so the Street focused on auto revenue and GPM. Consensus expected vehicle GPM at ~12.5%, modestly up from 12.1% in Q2.
Actual vehicle GPM was 13.1%, about 60 bps above expectations, mainly as ASP was materially higher (RMB 183k vs. RMB 168k). Unit cost rose less than ASP.
Drilling down into unit economics:
a) ASP: sharp rebound on GX mix
ASP was RMB 183k, up RMB 18k QoQ, attributed to model mix improvement.
i) Model mix upgrade: GX had its first full delivery quarter, lifting mix by ~11ppts QoQ to ~18%, offsetting the drag from Mona (M03 plus L03 launched in Jul) rising to ~43% mix.
ii) Higher export mix: Exports hit a record 10,055 units in Sep, lifting Q3 export mix to ~24% (from 19.4% in Q2). Export models priced above EUR 40k supported ASP.
b) Unit cost: mix-driven increase, offset by scale and in-house chips
Unit cost was ~RMB 159k, up ~RMB 14k QoQ.
i) Structural increase: higher premium mix raises unit cost, which is not cost deterioration per se.
ii) Raw material pressure: memory prices kept rising in 2H (also behind L03 supply constraints), compounded by higher battery and aluminum costs and initial L03 ramp costs and amortization.
Partly offset by:
iii) Scale benefits: deliveries +15% QoQ, further diluting fixed costs.
iv) In-house chips: Turing chips replaced third-party AD chips across the lineup, lowering core component costs.
c) Unit GP: up to ~RMB 24k
Unit GP was ~RMB 24k, up ~RMB 4k QoQ, above the market's ~RMB 21k.
II. Q4 guidance beat on both deliveries and revenue
a) Deliveries guide beat, but L03 supply bottleneck remains
Q3 deliveries were 118.4k units, +15% QoQ. L03 rose from under 3k units in Jul to over 10k in Sep, and GX stabilized above 7k per month.
Q4 delivery guidance is 169–174k (+43%–47% QoQ), with drivers and bottlenecks as noted above. The newly launched Mona L05 (RMB 140k–172k) competes with BYD Sealion 06 and Leapmotor C11.
b) Revenue guide slightly above, but implies lower ASP
Q4 revenue guide is RMB 30.4–31.8 bn (+37%–43% YoY). As noted, implied ASP declines ~RMB 15k QoQ.
Dolphin believes ASP headwinds in Q4 are largely set as L03 and L05 scale, while VW service revenue stays low. Blended GPM likely lands at 17%–19%.
The key is whether vehicle GPM can hold as ASP falls, and how much scale can dilute opex.
III. Blended GPM down as service 'red envelope' fades
Q3 revenue was RMB 24.28 bn, above the Street at RMB 22.7 bn. Blended GPM was 18.9%, slightly above the 18.6% Street, with the decline driven by lower high-margin services and a QoQ recovery in vehicle GPM.
i) Total revenue beat
Auto sales were RMB 21.63 bn (+20% YoY, above RMB 19.8 bn Street), mainly on ASP gains from higher-priced mix.
Service and other was RMB 2.65 bn, down RMB 50 mn QoQ (+13.7% YoY).
a. Tech R&D service recognition fell: after VW's ID. UNYX 08/09 launches, milestone revenue from the development phase declined. Management noted a large milestone recognition last quarter.
The decline was smaller than the Street expected, mainly because:
b. Carbon credit transactions increased, the primary driver of YoY growth in services.
c. Parts and after-sales rose with a larger installed base.
ii) GPM slightly above expectations; service GPM drop was the drag
Vehicle GPM dynamics are covered in Section I. Service and other GPM was 67.1%, down 800 bps QoQ and broadly in line with the Street at 67.5%, reflecting a lower mix of high-margin tech R&D services.
Service GP fell ~RMB 250 mn QoQ to RMB 1.78 bn.
IV. Opex supports Physical AI and new launches
Intelligence is XPeng's core moat, requiring heavy investment in AI driving, robotics, and new platforms. With revenue growing faster in Q3, opex ratios fell meaningfully, though absolute opex remained elevated.
1) R&D: RMB 2.85 bn, down slightly QoQ
R&D rose 17.5% YoY, with ratio at 11.8% (vs. 14.8% in Q2), mainly invested in:
i) ADAS upgrade:
Hardware: Turing chips are in mass production across the lineup. L03 Max uses a single 750 TOPS chip, Ultra SE uses dual 1,500 TOPS, bringing 1,500 TOPS to RMB 150k-class SUVs for the first time.
G9L carries three Turing chips (2,250 TOPS).
Software: VLA 2.0 improves 'sense of time' with 30-second temporal memory and a world model that projects six seconds ahead. It rolled out with OTA 6.3.0 on Sep 22, alongside VLA 2.0 Lite for lower compute platforms.
ii) Robotaxi (L4 autonomy):
Factory-fitted mass-production Robotaxi adopts a four-chip redundant architecture, with vehicle BOM well below RMB 200k. It has obtained permits for driverless road testing for the primary seat, and the cloud teleoperation platform is ready.
Business model: XPeng provides vehicles and the tech platform, charging service fees or revenue share, partnering with ride-hailing platforms domestically and abroad.
iii) Humanoid robot IRON:
IRON has 76 DoF in total and 21 DoF per hand, running three Turing chips (2,250 TOPS). Core components such as joint modules, actuators, and precision structures have been sourced.
The first batch will be deployed in XPeng stores and campuses, with monthly capacity of several thousand units.
Pengxing's latest round was led by external institutions, with Tencent and Alibaba as strategic investors. XPeng holds ~68.4%–73.8% (subject to option pool and warrant exercises), will continue consolidation, and plans to complete robot asset injection within 18 months of the first subscription.
iv) New model development:
Mona L03 launched on Jul 16 (from RMB 123.8k), G9L launched on Sep 17 (pre-sale from RMB 259.8k), and Mona L05 launched on Oct 29. All four new SUVs have now rolled out.
2) S&M: RMB 2.78 bn, driven by new model marketing and commissions
S&M ratio was 11.4% (vs. 12.6% in Q2). Beyond commissions and launch marketing, overseas channels are scaling, with ~150 dealers in Europe.
Stores stood at 731 across 253 cities at Q3-end, a net decrease of 9 stores and 4 cities vs. Q2-end, as channels enter an optimization phase. Owned charging stations increased to 4,035 (vs. 3,780 at Q2-end).
V. Operating loss narrowed
Q3 net loss was RMB 870 mn (vs. RMB 1.34 bn in Q2 and RMB 380 mn a year ago). GAAP OP loss was RMB 750 mn, better than the Street at RMB 1.21 bn.
Besides better vehicle GP, a RMB 160 mn FV gain on contingent consideration from the Didi auto asset acquisition and RMB 110 mn of other income also supported narrower OP loss.
Excluding these, core operating profit (GP minus core opex), a cleaner gauge of core cash generation, was -RMB 1.03 bn, narrowing ~RMB 300 mn QoQ, driven by the factors discussed above.
<End here>
Risk disclosure and statement: Dolphin Research Disclaimer and General Disclosure
Prior in-depth and tracking pieces on XPeng by Dolphin Research:
Earnings season
Aug 25, 2026 earnings note 'XPeng: Auto sales under pressure, can the AI story keep dancing?'
Aug 19, 2025 earnings note 'XPeng: GPM at a record high, can it spread its wings?'
Aug 20, 2025 call Trans 'XPeng (Trans): Aiming to make New P7 a top-3 BEV in the RMB 200–300k range'
May 21, 2025 'XPeng: After hardship comes reward, can XPeng become a soaring 'Roc'?'
May 21, 2025 '(Q1 2025 Trans): Poised to take off, is this 'Roc' really going sky-high?'
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.