$Moderna(MRNA.US)
Moderna Has Soared. Is Its Cancer Vaccine Worth the Premium?
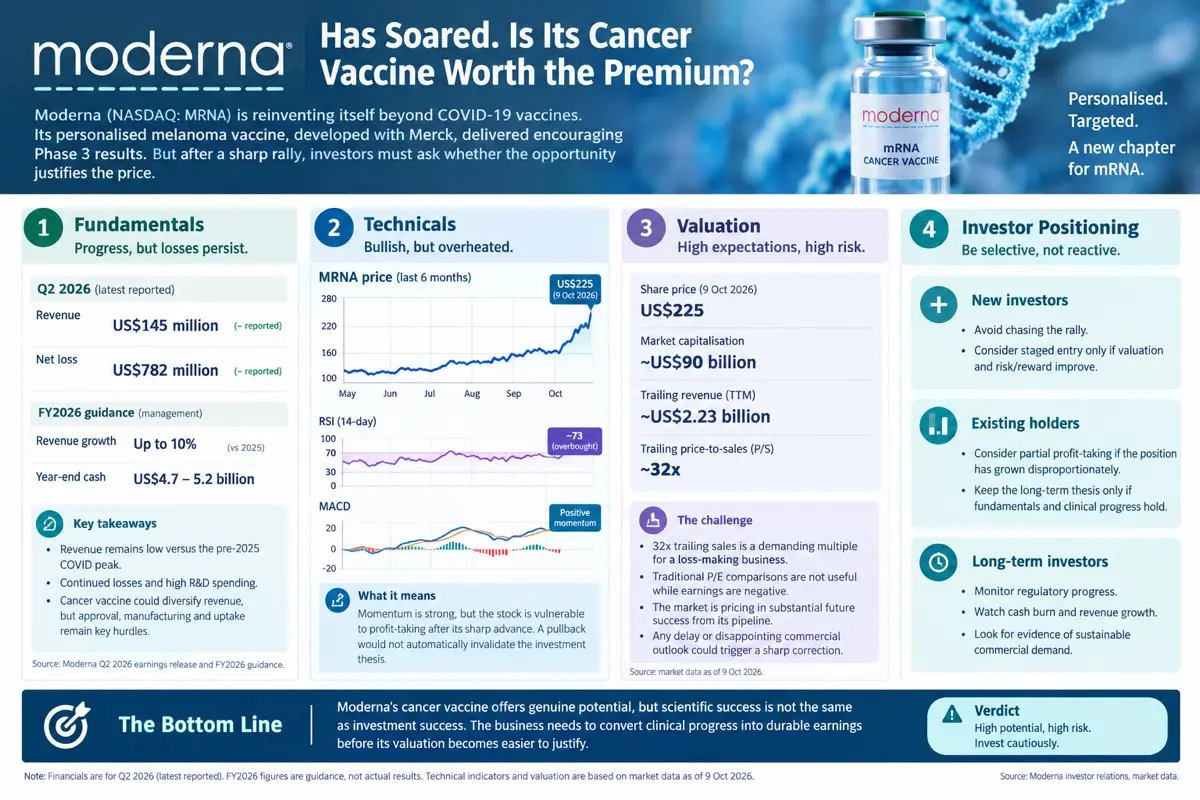
Moderna $Moderna(MRNA.US) is reinventing itself beyond COVID-19 vaccines. Its personalised melanoma vaccine, developed with Merck, delivered encouraging Phase 3 results, opening a potential new growth chapter. But after a spectacular rally, investors must ask whether the opportunity justifies the price.
Fundamentals: progress, but losses persist
Moderna reported Q2 2026 revenue of US$145 million and a net loss of US$782 million. Management expects FY2026 revenue growth of up to 10%, with year-end cash projected at US$4.7–5.2 billion. The cancer vaccine could diversify revenue, but regulatory approval, manufacturing costs and commercial uptake remain key hurdles.
Valuation: the biggest concern
At around 32 times trailing sales, Moderna commands a demanding valuation despite continued losses. Traditional price-to-earnings comparisons are unhelpful while earnings remain negative. The market is effectively pricing in substantial future success from its pipeline. Any delay or disappointing commercial outlook could trigger a sharp correction.
How should investors position themselves?
New investors should avoid chasing the rally and consider staged entry only if valuation and risk/reward improve. Existing holders may consider partial profit-taking if the position has grown disproportionately. Long-term investors should monitor regulatory progress, cash burn and evidence of sustainable revenue growth.
Verdict: Moderna’s cancer vaccine offers genuine potential, but scientific success is not the same as investment success. The business needs to convert clinical progress into durable earnings before its valuation becomes easier to justify.