CLuo

CLuo

ReturnsTop 9%
2Following14Followers266Likes & Bookmarks
C
CLuo
Featured

$Taiwan Semiconductor(TSM.US)

Context:

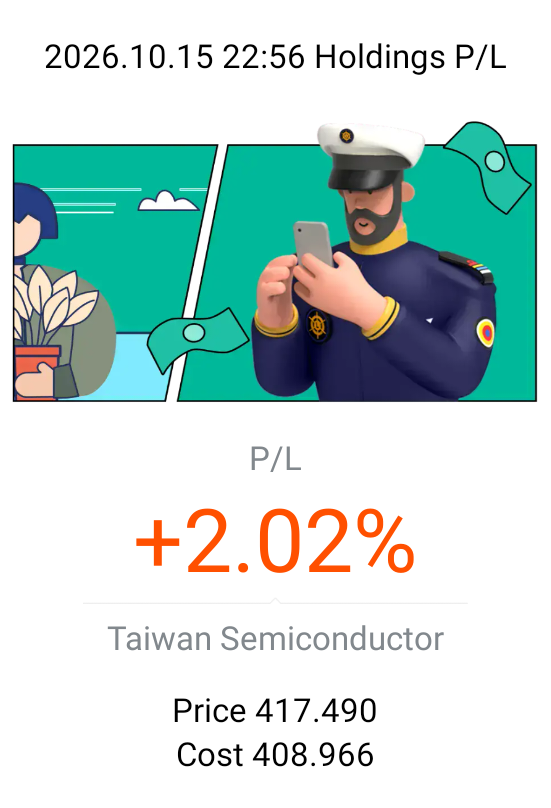
I decided to buy TSM today, right after its earnings. Honestly, it's an interesting day to enter because the numbers were strong, yet the stock still sold off.

Q3 revenue grew 50.9% YoY and net profit jumped 68.7%, but the market seems more focused on inflation, interest rates and concerns around AI spending.

What caught my attention wasn't just the earnings beat. It was how differently the market reacted to the results.

My Trade:

I placed a buy order today because I see TSMC as more than just another AI stock. Whether it's Nvidia, Apple or other chip designers, someone still needs to manufacture those advanced chips at scale.

I'm not assuming today's price is the bottom. Valuation, overseas expansion costs and pressure on margins are all worth watching.

But I don't want short-term market pessimism to completely overshadow what the company is delivering.

Takeaway:

Today's trade reminded me that good earnings don't always lead to a green day.

Sometimes the harder part is separating a company's performance from the market's expectations.
图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Tesla(TSLA.US)

Context:

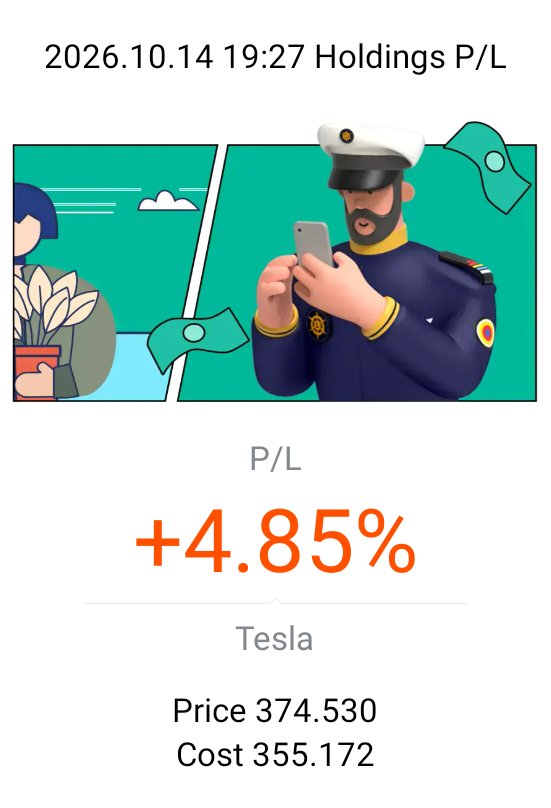
Tesla closed near $375 after several weak sessions, with attention turning to the October 15 Roadster reveal.

But I'm more focused on Robotaxi safety concerns and Q3 earnings on October 21 than another flashy announcement.

My Trade:

I'm holding TSLA for its long-term potential in autonomous driving, robotics, and energy storage. Still, ambitious promises need real execution.

What matters most to me is commercial progress, profitability, and margins rather than short-term hype.

Takeaway:

Patience isn't blind optimism. I believe in Tesla's vision, but I still question its timeline.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Dell Tech(DELL.US)

Context:

DELL is a pretty interesting one to watch right now. The stock has been under pressure recently, even as AI infrastructure spending continues to expand.

What caught my attention today was IDC's projection that spending on OCP-related infrastructure could reach $800B annually by 2029.

But there's another side to the story. AI data centers are consuming huge amounts of memory, pushing component costs higher while the traditional PC market faces weaker demand.

In a way, AI is creating opportunities and problems for Dell at the same time.

My Trade:

My interest in DELL isn't just about the AI hype. I'm more interested in whether it can turn growing AI server demand into sustainable profits.

Selling more servers is great, but if component costs rise and competition squeezes margins, revenue growth alone won't tell the full story.

Today's price weakness doesn't change how I evaluate Dell, but it reminds me why execution and profitability matter just as much as demand.

Takeaway:

One thing I'm learning is that being on the right side of a growing industry doesn't automatically guarantee strong returns.

For Dell, I think the real test is whether it can capture more value from the AI infrastructure boom, not just sell more hardware.

Curious what others think: Is Dell becoming a serious AI infrastructure player, or will hardware margins remain its biggest limitation?

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo
Featured

$Direxion Semicon Bull 3X(SOXL.US)

Context:

Today is a good example of why I hold SOXL differently from my individual semiconductor stocks.

Semiconductors are bouncing again after Micron’s strong results and continued AI memory demand. SOXL is up around 4%, with NVDA and MU higher while AVGO is down. Treasury yields are also still adding pressure in the background.

So this isn’t simply “chips are going up again.” There are still a lot of moving pieces.

My Trade:

I’m holding SOXL because I still have conviction in the broader semiconductor cycle, especially as AI continues to drive demand across compute, memory and infrastructure.

But I treat it very differently from NVDA or TSM. SOXL gives me 3x daily exposure, so being right long term isn’t enough. Timing, volatility and position size matter much more.

A strong green day is nice, but I don’t want it to make me forget what I’m actually holding.

Takeaway:

SOXL has taught me that conviction and leverage are two separate decisions.

I can stay bullish on semiconductors without getting more aggressive every time the sector rallies.

The harder question isn’t whether I believe in AI or semiconductors long term. It’s how much leverage I’m comfortable carrying while that story plays out.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Seagate Tech(STX.US)

Context:

AI gets most of the attention for compute, but all that data still needs somewhere to live. That’s why STX caught my attention.

My Trade:

I’m holding STX because I see storage as a less obvious but essential part of the AI infrastructure buildout. Recent HDD supply tightness only strengthens that view for me.

Takeaway:

AI doesn’t stop at GPUs. Compute creates data, and data creates storage demand.

That’s the part of the AI trade I think people still underestimate.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$NVIDIA(NVDA.US)

Context:

My NVDA position is currently up 23.76% from an average cost of $183.636. Seeing a gain like this naturally makes me think about taking profit, but I keep reminding myself that a rising share price alone is not a reason to sell a good business.

What matters more to me is whether the business I originally bought is becoming stronger or weaker.

NVIDIA continues to play an important role in AI computing infrastructure. What I am watching is not the daily share price, but whether the company can sustain its competitive advantages, continue growing earnings over the long run, and turn the enormous demand for AI computing into durable economic value.

Of course, a wonderful business can still be a poor investment at the wrong price. After NVDA's strong performance, valuation and increasingly high market expectations deserve even more attention.

My trade:

I am still holding. As long as the business remains strong and my original investment thesis stays intact, I would rather be patient than sell simply because I am sitting on a good profit.

Takeaway:

My biggest lesson is to think like a business owner rather than react like a trader. Next time, I want to spend even less time watching short-term price movements and more time asking one question: Would I still want to own this business for years if I could not see its stock price every day?

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Western Digital(WDC.US)

Context:

WDC has been one of those positions that reminds me how different market sentiment can be from actual industry demand.

The stock has faced pressure from concerns around slower AI growth, higher yields, and whether AI infrastructure spending can keep going.

But what keeps me interested is simple: AI still needs physical infrastructure, and that includes a lot of storage. Tight HDD supply and longer order visibility make me think storage may be more important to the AI buildout than the market gives it credit for.

My Trade:

I’m still holding WDC. I don’t want to judge the position based on daily AI headlines.

What matters more to me is whether hyperscale data-center demand stays strong, supply remains disciplined, and WDC can turn that demand into better cash flow and fundamentals.

Takeaway:

This trade changed how I think about AI investing. Not every winner has to make the most advanced chips.

Sometimes the less exciting parts of the infrastructure stack can benefit from the same long-term trend.

So short-term weakness doesn’t automatically change my view. I’d rather watch whether the storage demand story itself starts to break.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Dell Tech(DELL.US)

Context:

What keeps DELL on my radar is actually pretty simple. AI needs a lot more than powerful chips. Someone still has to turn all that computing power into servers and infrastructure that companies can actually deploy, and Dell is participating directly in that buildout.

The recent numbers show that demand is there. But at this point, I think the more interesting part is what happens after the big growth numbers. Dell still has to prove that rapidly expanding its AI server business can create attractive profits, not just impressive revenue.

My Trade:

I’m continuing to hold my DELL shares, but I’m not adding simply because the stock has been strong. I would rather give the position time and watch the business. The thing I care about now is whether Dell can handle huge AI server demand without giving too much away through higher component costs and pressure on margins.

That is the part of DELL I think deserves more attention. A massive order book can look exciting, but eventually those orders need to become profitable business.

Takeaway:

DELL is teaching me to separate business growth from investment quality. More sales are good, but I also want to know what the company earns from those sales.

So my reason for holding is not simply that AI is popular. I’m holding because I want to see how much value Dell can actually capture from the AI infrastructure boom.

This is my personal trading reflection, not investment advice.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$TSLA 2X Long ETF(TSLL.US)

Context:

I already hold TSLA, but wanted additional leveraged exposure without simply adding more shares. TSLL targets 2x TSLA’s daily performance, so I see it as a tactical position rather than a long term holding.

My Trade:

I understand TSLL carries very different risks from owning TSLA. Daily resets and compounding mean long term returns can differ significantly from simply getting 2x TSLA’s return, especially during volatile markets.

That’s why I’m focused on position size and how the trade develops rather than treating every TSLA move as a reason to add.

Takeaway:

Leveraged ETFs provide more exposure with less capital, but they also require more discipline. For me, the key is knowing the role of the position before volatility picks up.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Tesla(TSLA.US)

I didn’t buy Tesla because I think it’s just a better car company.

My average cost on Tesla is $355.17, and the position is currently up 1.94%. Nice, but that was never the reason I bought it. What interests me is that Tesla is still being defined by the market. Cars give it scale today, while autonomy, energy and AI could reshape what the company is worth tomorrow.

That uncertainty is why Tesla can look expensive to one investor and cheap to another. For me, the question was whether enough of those future businesses can become real to justify paying for part of that future today. That’s the bet I made at $355.17.

The 1.94% gain doesn’t prove the thesis. It only means the market has moved in my direction so far.

CLuo 2026-09-1622:49:26 Tesla TSLA P/L% +1.94% Market price 363.040 USD, ,Cost 3
C
CLuo

$NVIDIA(NVDA.US)

Context:

I bought NVDA because I wanted exposure to the AI growth story, but the more I follow the company, the more I see it as something bigger than just a chipmaker. What interests me is how NVIDIA is building an entire ecosystem around AI, including computing, networking and software.

My Trade:

I’m still holding my position. What I’m watching now is whether this ecosystem continues to translate into real demand from customers. I’m also curious to see how NVIDIA keeps its position as AI infrastructure becomes more competitive.

Takeaway:

My biggest takeaway from holding NVDA is that I shouldn’t look at it only as a stock that benefits from AI. I want to understand how the company is building its role in the AI infrastructure itself.

I’m curious what other NVDA holders think. Do you see NVIDIA mainly as a chip company, or as an AI infrastructure company?

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Comfort Systems USA(FIX.US)

Context: What interests me about FIX is that AI is not only a story about the companies building AI. Behind the growth of AI and data centers, there is also a huge need for power, cooling, electrical and mechanical infrastructure.

That made me look beyond the obvious AI names and pay more attention to the companies building the infrastructure behind them. FIX gives me exposure to this trend from a different angle, rather than directly investing in AI chips or software.

My Trade: I’m holding FIX because I like the idea of investing in a business that can benefit from the continued expansion of data centers. I’m not trying to predict which AI company will ultimately win. Instead, I’m interested in the infrastructure that many of them will need regardless of who wins.

Takeaway: This position reminded me to look one step beyond the obvious trend. Sometimes the interesting opportunity isn’t the company everyone is talking about, but the businesses providing what that trend needs to keep growing.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Circle(CRCL.US)

Context: I originally added Circle to improve diversification in my portfolio. Rather than having too much exposure to assets driven by similar factors, I wanted to include a position with a different risk and return profile.

My Trade: I did not add to or reduce my position this time. I’m continuing to hold Circle at an average cost of $90.909. The position is currently around +2%, with the share price at approximately $92.940. For now, I’m monitoring whether the position continues to serve its intended role in my portfolio.

Takeaway: Diversification is not just about owning more stocks. What matters is whether each position adds genuinely different risk and return drivers to the overall portfolio.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

I’m looking for ORCL to close around $169 on 11 September.

The key for me is whether OCI growth confirms that the huge AI backlog is actually converting into revenue.

Expectations are already high, so I don’t think a normal EPS beat alone is enough for a 10%+ rally.

If cloud growth and FY2027 guidance hold up without another major financing surprise, I think a mid-to-high single digit gain is the most reasonable outcome.

C
Captain's Watch
Oracle Earnings Challenge — Guess the close and win cash!

$Oracle(ORCL.US) reports Q1 FY2027 after the US close tonight, Thursday 10 September — the numbers land around 04:00 SGT Friday morning, with the call at 05:00. ⏰Here is the part worth sitting with. A...

LONGBRIDGE ORACLE EARNINGS CHALLENGE Where does ORCL.US close on Friday 11 Septe
C
CLuo

$Seagate Tech(STX.US)

Context: Everyone is chasing AI chips, but where does all that training data actually live?

Seagate had a huge run and is finally taking a breather around $848. HDDs are still much cheaper than SSDs for massive storage, and big cloud companies will keep needing them as AI demand grows. That cost advantage is the key catalyst for me.

My trade: I am in this for the long haul, so I do not use a stop loss. I am holding my shares and letting the long term storage trend play out.

Takeaway: HDDs are still the cheapest way to store AI data. Is this a solid dip to buy, or are margins close to peaking?

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Seagate Tech(STX.US)

Context: STX has pulled back quite a bit recently, but I don’t think the core story has changed. Cloud storage demand is still strong, HAMR is starting to become a bigger part of the business, and Seagate already has a lot of its nearline capacity spoken for well into 2028. The balance sheet is also in much better shape now, with the company back at investment grade.

My trade: I’m keeping my core position. At this point, I care a lot more about whether demand, margins and free cash flow stay strong than what the stock does over the next few weeks.

Takeaway: What I’m watching now is whether Seagate can keep margins above 50% as HAMR continues to scale. If it can, then I think the long-term story is still very much intact despite the recent pullback.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Comfort Systems USA(FIX.US)

Context: What I like most about this company is its moat in complex data center liquid cooling. The technical barriers are high, making it difficult for competitors to enter the space.

After a huge run, the stock is now going through a healthy consolidation, while continued data center buildouts remain a strong long-term catalyst.

My Trade: I’m staying patient on the sidelines for now. If the price drops to $1,500 or below, I’ll start DCAing in to give myself a better margin of safety.

Takeaway: Strong technical barriers give this business a durable moat, but valuation still matters. At current levels, do you think we see another leg higher, or a deeper pullback first?

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Circle(CRCL.US)

Context: What interests me about Circle is its position at the intersection of crypto and traditional finance. As stablecoins gain adoption in payments and settlement, USDC is becoming more than just a crypto asset. It is evolving into financial infrastructure, with Circle at the center of that transition.

My trade: I initiated a position yesterday.

USDC circulation continues to grow, on chain volume is expanding rapidly, and Circle is building a key infrastructure layer connecting stablecoins, payments, and traditional finance. That is the opportunity I want exposure to.

Takeaway: The market may still be underestimating the long term potential of the stablecoin economy. This thesis does not require every quarter to be perfect. What matters is whether adoption continues and the long term direction remains intact.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Western Digital(WDC.US)

Context:

AI is creating an enormous amount of data, and all of that data ultimately needs to be stored. As hyperscale data centers continue to expand, I believe high-capacity HDD demand has a durable runway. With WDC now a pure-play HDD company, the thesis is cleaner and more directly tied to that structural growth.

My Trade:

I’m long WDC and simply holding my position. I’m not adding or trimming based on short-term price action. As long as cloud demand remains strong and the underlying business continues to execute, I see no reason to interfere with the position.

Takeaway:

Not every investment needs constant action. When the thesis is working and the fundamentals continue to move in the right direction, sometimes the best decision is to do nothing and give the business time to create value.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Comfort Systems USA(FIX.US)

Context: I really like its moat in complex data center liquid cooling, where high technical difficulty keeps competitors out. After a huge run, the stock is just resting in consolidation, but ongoing data center buildouts remain a solid long term business Catalyst.

My trade: I am patiently waiting on the sidelines. If the price drops to 1500 dollars or below, I will start dollar cost averaging in for a better margin of safety.

Takeaway: Strong technical barriers create a durable moat, but at current valuation levels, do you expect another leg up or a deeper pullback?

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$NVIDIA(NVDA.US)

Context:

NVIDIA reports earnings next week, and it’s the event I’m watching most closely.

As an NVDA shareholder, I’m less focused on guessing the post earnings price move and more interested in whether the results and outlook can continue to support the market’s high expectations.

With the VIX around 15, sentiment is relatively optimistic, while the 10 year Treasury yield remains elevated. These factors don’t directly affect NVIDIA’s earnings, but they could influence how the market reacts. With expectations already high, good earnings don’t necessarily mean the stock will go up.

My trade:

I’m not adding or trimming my NVDA position ahead of earnings. I’m simply continuing to hold.

I’m more focused on whether AI demand remains strong and whether management’s outlook for the coming quarters changes. For now, I’ll maintain my position and reassess after earnings.

Takeaway:

Holding is also a decision. For me, this earnings report isn’t about predicting the short term price move. It’s about seeing whether the reasons I originally chose to hold NVDA have changed.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Stride(LRN.US)

Context: I see Stride as a simple, defensive business with relatively predictable revenue from online education and career training. Recent results remained solid, while earlier insider transactions that caught my attention were largely related to tax withholding on equity awards. Despite the leadership transition, I still see continued growth in Career Learning as the key catalyst for long-term compounding.

My trade: I have avoided adding heavily while the stock remains in a sideways consolidation. I’m comfortable holding my core position, keeping downside defined, and waiting for volume to dry up and a clear breakout before committing fresh capital.

Takeaway: Stride’s asset-light education model and growing Career Learning business give me confidence in its resilience through the leadership transition.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Curtiss Wright(CW.US)

Context: The main reason I am holding tight is the current sector rotation and capital flow. Despite recent market volatility, CW has shown massive relative strength near its key support levels. As long as the fundamentals remain intact and technical supports hold, I view this consolidation as healthy accumulation.

My trade: My average entry cost sits at 627. I am taking absolutely no action today. Looking at the chart, the price is stuck in a chop zone. Adding here ruins my cost basis, and taking profits means missing out on the potential breakout. My framework is simple. I respect my stop loss and let the winners ride as long as the thesis plays out.

Takeaway: Consolidation phases test your psychology. Chopping around usually leads to overtrading and getting shaken out. My next move is to wait for a high volume breakout before considering adding to my position.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!
C
CLuo

$Western Digital(WDC.US)

Context: Western Digital trades at a persistent valuation discount to Seagate despite sitting inside the exact same enterprise hard drive duopoly. Cloud demand for high capacity nearline drives is driving gross margin expansion, yet stock market pricing still lags behind fundamental cash flow generation.

My trade: Holding my shares and letting the valuation gap close.

Takeaway: Buying unsexy infrastructure bottlenecks at a discount is my favorite way to compound capital.

图片 1,共 1 张
Trade Showcase: Trade, Show & Earn Rewards!