

🏢 MLT - Discounted Price, But Is It a Trap?🤔
Mapletree Logistics Trust is trading near its 52-week low. The bigger story is the gap between its valuation, income and fundamentals.
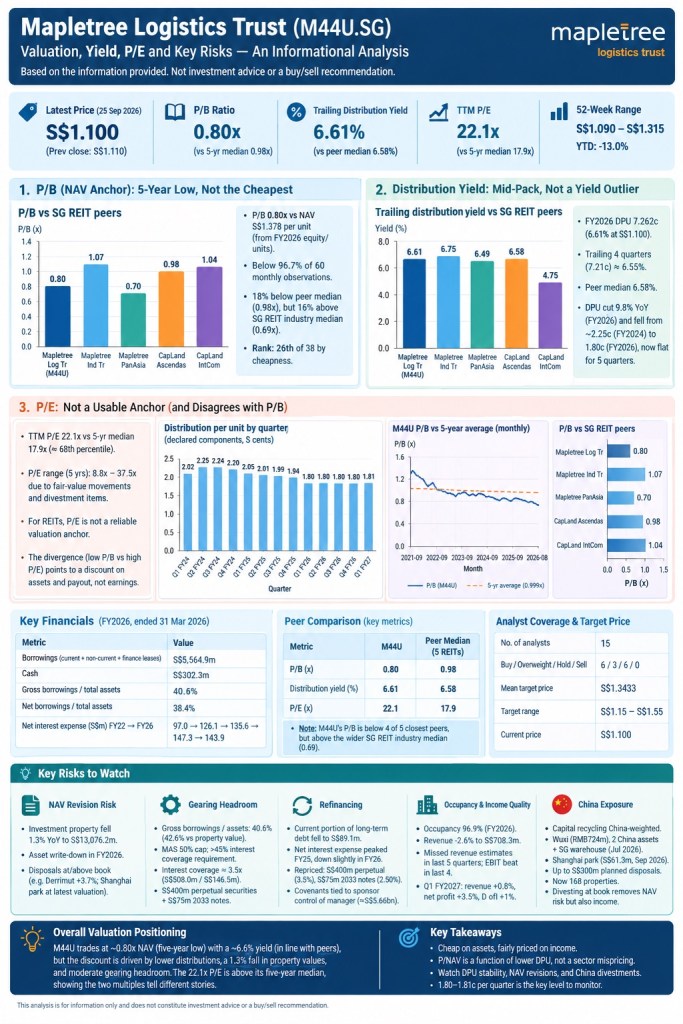
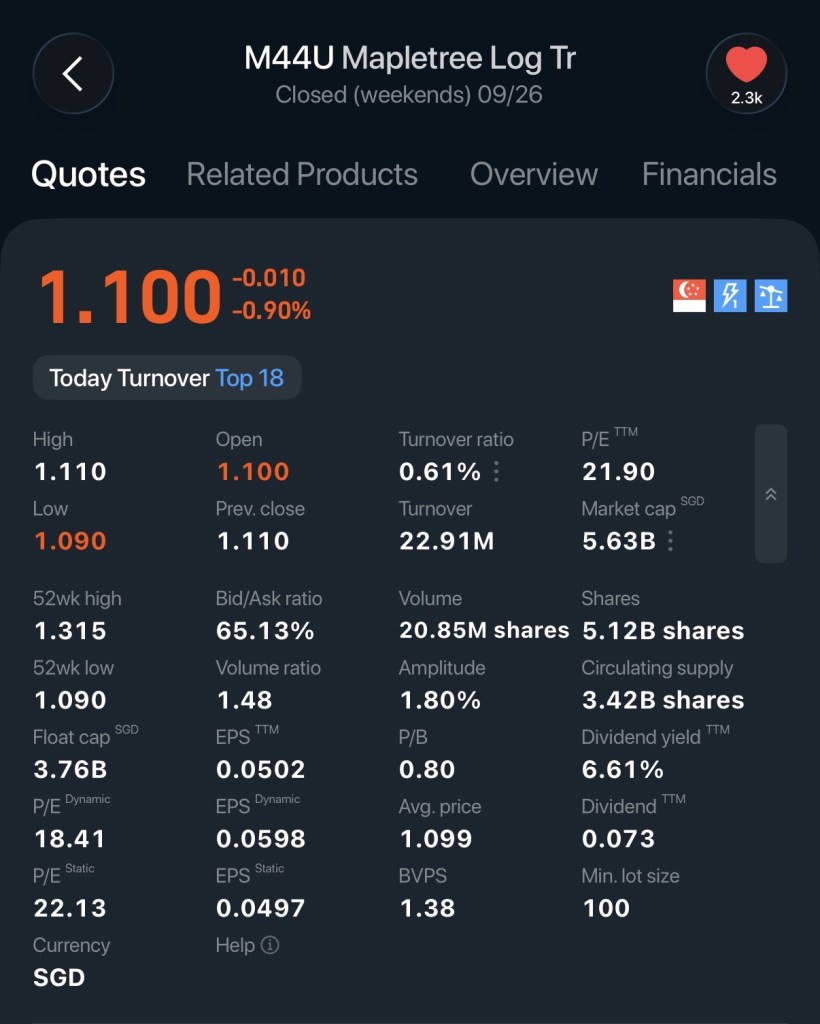
At S$1.10, MLT trades at roughly 0.80 times book value. That is well below its own five-year median of 0.98 times and suggests a meaningful discount to its net asset value (NTA).
If we compared its current P/B to the broader Singapore REIT market, the picture is less clear. MLT’s 0.80 times P/B is above the sector median of 0.69 times. Its distribution yield of 6.61 percent is nearly identical to the peer median of 6.58% ( Capland Ascendas REITs)
The main concern is distribution growth.
Full year 2026 DPU fell 9.8 percent to 7.262 cents from the prior year. Quarterly DPU has since steadied around 1.80 to 1.81 cents but it is still uncertain whether this level will hold.
Gearing is also a consideration. Gross borrowings stand at about 40.6 percent of total assets.
The P/E ratio tells another story entirely. At 22.1 times, it is above its five-year median of 17.9 times ( For reference and may not be feasible for all Reits performance measurement).
This shows the reason as to why P/B and yield metrics can send different signals when valuing REITs.
See the infographic for full valuation details, peer comparisons, financials and key risks.
Not financial or investment advice. Please do your own due diligence ☺️. Happy weekend. Cheers.
$Mapletree Log Tr(M44U.SG)