longbridgelongbridge
  • Platform Features
    Features
    Investment ProductsPrivate Wealth ManagementTrading ToolsMarket Data ServicesAnalysis ToolsNews ServicesFor Developers
    Account Types
    For IndividualsFor Institutions
  • Café
longbridge
© 2026 Longbridge|Terms of ServicePrivacy Policy
TheInvestingIguana

TheInvestingIguana

AssetsTop 1%ReturnsTop 19%

The Investing Iguana breaks down SGX dividends and CPF/SRS retirement planning in plain English, so you can invest calmly toward retirement

The Investing Iguana breaks down SGX dividends and CPF/SRS retirement planning in plain English, so you can invest calmly toward retirement

AJBURate Of Return
1Following128Followers275Likes & Bookmarks
TheInvestingIguana
TheInvestingIguana
ArticlesOriginalFollowingFollowersStocks mentioned

Who to follow

T
TheInvestingIguana12 hours ago
Featured

Iggy's Journal: Inflation Ticks Up for a Third Straight Month. The STI Barely Noticed.

23 September 2026, Evening

(No infographic for this post; I'm on a plane right now) 


The STI closed at 5,709.9, down 13.85 points, a quiet 0.24 percent day. Underneath that quiet, Singapore just posted its highest core inflation reading in two years, and the room is genuinely split on what MAS does about it in October.


The Numbers

Core inflation rose to 2.2 percent in August from 2 percent in July, the third straight monthly increase, while headline inflation, which includes accommodation and private transport, ticked up to 2.3 percent. Airline ticket costs jumped 12.9 percent, the sharpest rise in nearly four years, and services inflation climbed to 2 percent from 1.7 percent the month before. MAS already tightened the SGD NEER slope twice this year, in April and again in July, and economists are now split on whether October brings another small tightening or a hold. DBS's Chua Han Teng summed up the tension in four words, inflation "firmed but not accelerating."  

My Personal Take

Barclays called this data "more benign" than what MAS was pricing in back in July, and I think that's the real story hiding under a boring index day. The central bank tightened twice this year on the expectation that growth would eventually show up as inflation. Now the inflation is showing up, just slower and milder than the move that was meant to get ahead of it. That's not a policy mistake, it's a central bank managing a moving target in real time, but it does mean the case for October restraint gets a little stronger with every print like this one. If your T-bill or fixed deposit is coming up for renewal around then, this is exactly the kind of data that decides whether your next rate looks better or worse than the last one.


Cheers, Iggy

T
TheInvestingIguana18 hours ago

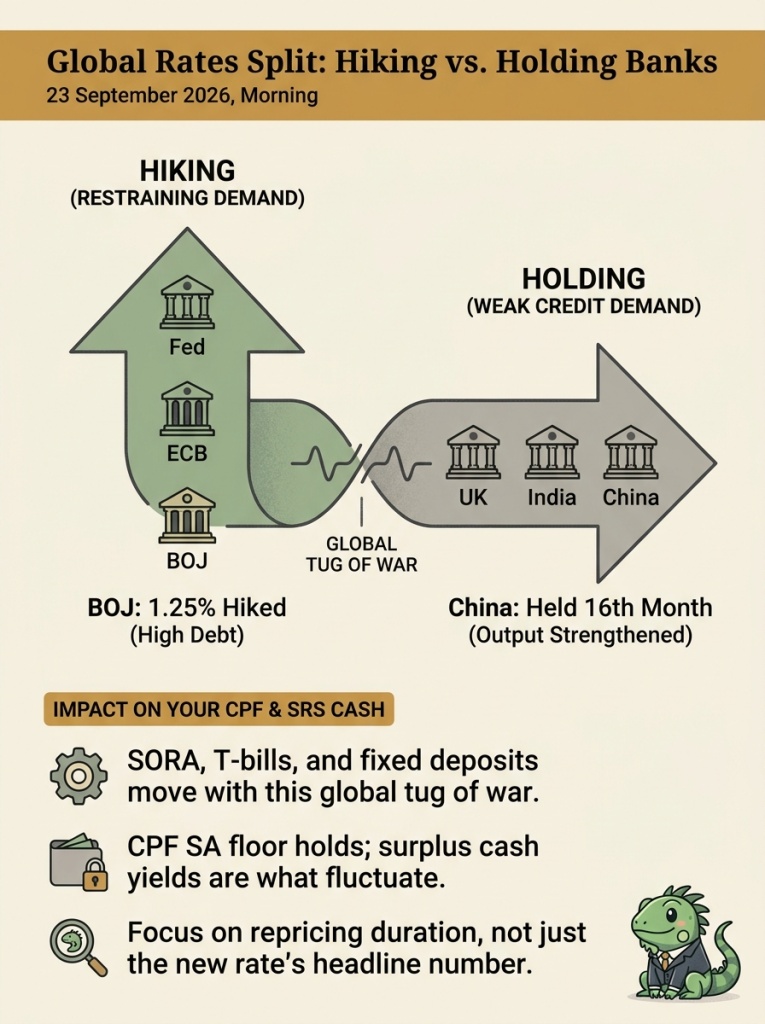
Iggy's Journal: The Fed, the ECB, and the Bank of Japan Are All Raising Rates. The UK, India, and China Are Not. Here's What That Means for Your CPF and SRS.

23 September 2026, Morning

Podcast

Everyone assumed hiking banks are the hawks and holding banks are the doves. That's the wrong frame entirely, and it took me a minute to see it too.

The Numbers

The BOJ hiked to 1.25% even though Japan carries one of the most indebted governments in the world, while China held for a sixteenth straight month despite industrial production actually strengthening. The real split isn't hawkish versus dovish. It's whose demand needs restraining versus whose credit demand is too weak to justify tightening at all. MAS doesn't set a policy rate the way the Fed or ECB does, but SORA mortgages, T-bill yields, and fixed deposit renewals all move with this global tug of war anyway, and UK 30-year gilt yields sitting near 5.7 to 5.9 percent this week show just how far that pressure is reaching.

My Personal Take

Your CPF Special Account keeps its government-guaranteed four percent floor no matter what any of these central banks decide this month, that part isn't moving. What's moving is what your surplus cash outside CPF competes against. If your next T-bill or fixed deposit comes up for renewal soon, the question I'd actually be asking isn't whether the new rate looks better or worse than last time. It's whether the reason behind that repricing is something likely to persist for a while, or something likely to pass in a quarter or two. That distinction is the whole episode.

📺 YouTube: https://youtu.be/nCfThkQ3MPU

📩 Substack: https://investingiguana.com/p/the-fed-the-ecb-and-the-bank-of-japan

Not financial advice. Iggy's Forensic Compliance Standards apply.

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
Global Rates Split: Hiking vs. Holding l Banks 23 September 2026,Morning HIKING
T
TheInvestingIguana1 day ago, 08:07 AM

Iggy's Journal: EP1828 - Singtel's Yield Looks Like 4.3%. Strip Out the One-Off Dividend and It's 3.1%.

22 September 2026, Evening

Video Release

UOB Kay Hian's $5.50 target and my 4.3% yield reading aren't actually disagreeing with each other. One is pricing a Nxera transaction that hasn't happened yet. The other is measuring the cash Singtel is paying out right now.

The Numbers

A stock can clear the first test and fail the second at the same time, and that's exactly what I found when I ran the current numbers. Strip out the one-off Value Realisation Dividend and Singtel's core yield drops to 3.08%, below what CPF Special Account already pays with zero equity risk attached. The balance sheet itself isn't the issue. Gearing sits at 23.3% and interest coverage at 19.0x, both clearing with wide margin.

My Personal Take

This isn't a quality problem, it's an income problem, and that distinction matters if you're holding Singtel for the yield rather than the balance sheet. Iggy's Forensic Zone on this one is Zone 4, Caution Plus, not because the company is shaky, but because once you strip out a one-time payout, the yield you're actually being paid is doing less for you than a CPF contribution with no equity risk at all. Full breakdown of how I separated the one-off from the recurring number is in today's video.

📺 Free YouTube: https://youtu.be/mnlbZ9Ski8w

⭐ Members Edition YouTube: https://youtu.be/GC8YJtuRlLw

📩 Substack: https://investingiguana.com/p/singtels-yield-looks-like-43-strip

Get everything, full-length videos and full Substack analysis on both platforms, full Red Zone watchlist, forensic cheatsheets, with the YouTube/Substack Combo, S$12/month.

Not financial advice. Iggy's Forensic Compliance Standards apply.

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
图片 1,共 1 张
T
TheInvestingIguana1 day ago, 06:34 AM

Chip Controls, a Boeing Deal, and a Taiwan Arms Sale All Converge on One Meeting. Here's the Singapore Read.

22 September 2026, Afternoon

Podcast

Everyone's watching whether Trump and Xi get along on September 24. I'm watching a different question. What happens to the equipment makers sitting underneath the chips, if nobody in that room even mentions them.

The Numbers

Export controls have been the sticking point through every round of talks this year, and the base case going in is that nothing changes on that front. That's the boring, correct expectation, not a surprise. AEM Holdings isn't on any export control list, but it posted 1H2026 revenue up 30 percent year on year to S$247.2 million on AI and high performance computing demand, the kind of order book that moves when the rules shift for its customers. UMS Holdings, also outside the control list but in the same equipment chain, grew 1Q2026 revenue 20 percent year on year to S$69.4 million with net profit up 43 percent to S$14 million. ST Engineering sits adjacent to the separate Boeing story through its Commercial Aerospace segment, which posted H1 2026 revenue of S$2.69 billion, up 15 percent, on higher engine MRO.

My Personal Take

I don't think this meeting changes anything on Thursday, and that's exactly why it's worth naming the names before the meeting happens rather than after. AEM and UMS don't show up on any sanctions list, but they live in the supply chain underneath one, and that's a different kind of exposure than most people are looking for when they check whether their portfolio has "chip stocks" in it. ST Engineering is a slower, steadier story running on a completely different clock, tied to how many planes are flying, not to what gets said in one room on one day. Nothing here says reposition before Thursday. 

📺 YouTube: https://youtu.be/-B_1nvVibqY

📩 Substack: https://investingiguana.com/p/chip-controls-a-boeing-deal-and-a

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
CHIP CONTROLS & E BOEING CONVERGE ON ONE MEETING 22 SEPTEMBER 2026 CHIP EQUIPMEN
T
TheInvestingIguana2 days ago, 09:16 AM

Iggy's Journal: Food Empire's Worst Day on the Board, Two REITs Went Quietly the Other Way

21 September 2026, Evening

The STI closed at 5,672.3, up 16.16 points, a quiet 0.29 percent day for the index. But quiet at the index level hid a rough one for at least one name on the board.

The Numbers

Food Empire fell 10 percent to $1.89 on the day, its sharpest single-session drop in a while, on volume of about 8.9 million shares. I don't have a confirmed catalyst for today's move and I'm not going to guess at one. Elsewhere, the REIT space was mixed rather than uniformly weak. Keppel DC Reit slipped 1.40 percent to $2.12 on light volume, while ManulifeReit USD moved the other way entirely, up 5.88 percent to US$0.036, the biggest percentage gainer among the more liquid names today.

My Personal Take

A ten percent drop in a single session is the kind of move that gets forwarded around group chats before anyone's actually read why it happened, and today I genuinely don't have the why. I'd rather say that plainly than fill the gap with a guess dressed up as analysis. The REIT picture is a good reminder that "REITs were weak today" is usually not true in any given session. One fell, one jumped nearly 6 percent, and the difference between them has nothing to do with sector and everything to do with the specific balance sheet underneath each ticker. That's the whole argument for reading the actual numbers instead of the sector label.

Not financial advice. Iggy's Forensic Compliance Standards apply.

Food Empire's Sharp Fall; REITs Diverge Quietly. 21 September 2026, Evening. FOO
T
TheInvestingIguana2 days ago, 06:48 AM

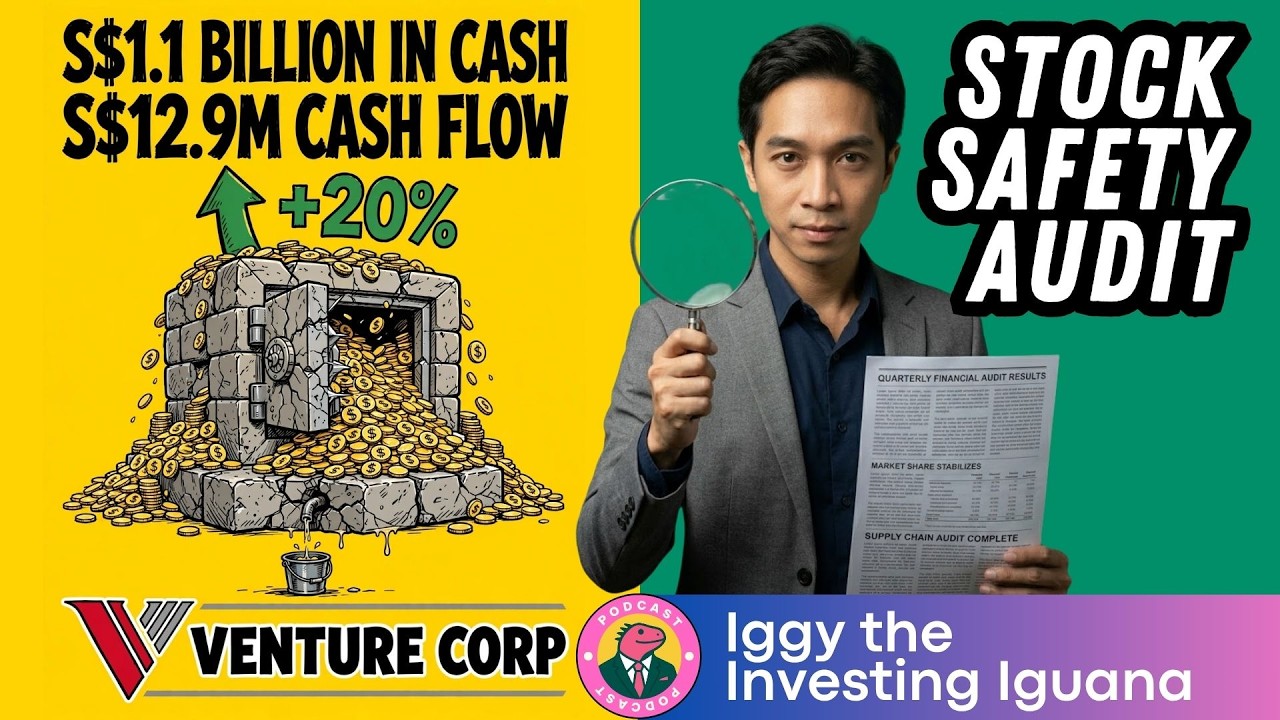
FeaturedThe S$1.1 Billion Question Behind Venture’s Dividend Raise

The S$1.1 Billion Question Behind Venture’s Dividend RaiseA 20% interim dividend hike, a fortress balance sheet, and a cash flow number that doesn’t quite add up.Venture just raised its dividend 20% o...

The SS1.1Billion Question VENTURE BehindVenture's Dividend Raise A20% interim di
Two Numbers, Same 1 VENTURE Company Same six months. Same company. The two numbe
e. 90=3122 A 2 3y INA(TAO2% 63 6876 4399 ¥ H EELAI 22 COVERAGE RATING Iggy's For
2 In hThis Article+19
Venture

Venture

SGV03

Stock Safety Audit
T
TheInvestingIguana2 days ago, 06:42 AM

Iggy's Journal: ETFs Cost 0.03%. Unit Trusts Hit You With 5% First.

21 September 2026, Afternoon 

I went through my own SRS lineup this week and checked the fee structure line by line, not just the headline expense ratio. What jumped out wasn't the ETF side. It was how much unit trusts are still costing people who probably don't know it.

The Numbers

Singapore's ETF market just crossed $20.5 billion, with CPF and SRS holdings up 380 percent. But fee compression isn't actually happening here. Banks earn 1.5 to 5 percent upfront sales charges on unit trusts, plus ongoing trailer fees worth 20 to 60 percent of the annual management fee. That structure keeps expensive unit trusts in favour, not because they perform better, but because they pay better to the people selling them.

My Personal Take

Numbers like that made me pause for a second. Then the forensic brain kicks in: over 20 to 30 years, that fee drag compounds into a meaningful chunk of your retirement outcome. But cheap doesn't automatically mean safer either. South Korea's retail investors found that out when leveraged ETFs tied to chip stocks amplified their losses instead of just tracking them. So the real question I keep coming back to isn't ETF versus unit trust. It's whether your adviser gets paid to help you, or gets paid regardless of what happens to your money. Let the numbers speak on that one.


📺 YouTube: https://youtu.be/rqhBXvgtuxg

📩 Substack: https://investingiguana.com/p/an-etf-can-cost-003-a-unit-trust

Not financial advice. Iggy's Forensic Compliance Standards apply.

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
Iggy's Journal: ETFs Cost 0.03%. Unit Trusts Hit You With 5% First.21 September
T
TheInvestingIguanaSep 20 at 08:48 AM

Iggy's Journal: Growing Faster, Bleeding Less, Still Not Paying You

19 September 2026, Evening

Video Release

Grab shares are sitting near a 52 week low. I pulled the actual Q2 2026 numbers before writing anything, and the share price wasn't what jumped out at me.

The Numbers

Financial Services revenue grew 59 percent to US$134 million, while the segment's EBITDA loss narrowed to US$15 million. That's growth with less bleeding, not profitability, and those are two very different things to be excited about. The Atome deal can't even consolidate into results until Q3 2027 at the earliest, so whatever story you're telling yourself about that acquisition today is getting ahead of the actual accounting.

My Personal Take

If you're holding Grab inside CPF or SRS, I want to be direct about what this actually is. Grab's own FY2025 Form 20-F says it does not expect to pay dividends for the foreseeable future. Iggy's Forensic Zone on this one is Red Zone, not an income vehicle, no dividend policy. The US$900 million buyback authorization over 12 months is real money and a real signal, but so is the equity award overhang sitting on the other side of the ledger, and which one actually wins that tug of war is still an open question. Full breakdown of how I'm weighing the buyback against the overhang is in today's video.

📺 Free YouTube: https://youtu.be/jCGDVCtGm0I

⭐ Members Edition YouTube: https://youtu.be/H_CDXAtue5I

📩 Substack: https://investingiguana.com/p/grab-shares-are-near-a-52-week-low

Get full-length videos and full Substack analysis on both platforms, plus the full Red Zone watchlist and forensic cheatsheets, with the YouTube/Substack Combo, S$12/month.

Not financial advice. Iggy's Forensic Compliance Standards apply.

Cheers, Iggy 🦖

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
Iggy's Journal: Growing Faster. Bleeding Less, Still Not Paying You 19 September
T
TheInvestingIguanaSep 19 at 07:16 AM

Iggy's Journal: The Currency That Didn't Get the Oil Shock Memo

19 September 2026, Afternoon

Podcast Release

Everyone assumes US$100 oil and a 5 percent US 10 year yield should hammer every regional currency equally. The Singdollar just hit a 10 month high against the ringgit instead.

The Numbers

Singapore isn't reacting like a typical emerging market to this shock. Durable balance of payments surpluses, strong FDI inflows, and MAS's own July tightening are pulling in safe haven money while neighbouring currencies absorb the pain the oil shock is supposed to spread evenly.

My Personal Take

This cuts both ways depending on what's actually sitting in your portfolio, and I think most people haven't checked which side they're on. A stronger Singdollar means cheaper imports and helps any REIT carrying foreign currency debt. It also eats into returns for exporters earning a big share of revenue overseas, once that money converts back home. Worth actually looking at your own holdings instead of assuming the currency move is automatically good news. Full breakdown of the balance of payments story in today's episode.


📺 YouTube: https://youtu.be/cHd3hmYvNP0

📩 Substack: https://investingiguana.com/p/singdollar-hits-a-10-month-high-against

Not financial advice. Iggy's Forensic Compliance Standards apply.

Cheers, Iggy 🦖

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
SINGDOLLAR HITS  10-MONTH HIGH VS RINGGIT 19 SEPTEMBER 2026 CURRENCY STRENGTH 3.
T
TheInvestingIguanaSep 18 at 10:05 PM

Iggy's Journal: The Bank Everyone Says Wins, and the Yield That Says Not Yet

19 September 2026, Morning

Video Release

Everyone read this week's Fed hike as good news for UOB. The structural case actually holds up, 43 percent of its loan book sits in Singapore dollars against 37 to 38 percent for DBS and OCBC. But here's what doesn't fit the celebration: UOB's yield gap to my hurdle widened this week, it didn't narrow.

The Numbers

UOB's trailing yield sits at 3.80 percent against my 4.7 percent hurdle, a 90 basis point miss that's actually 9 points wider than it was three weeks ago. The market had already priced in UOB's structural advantage before the Fed even opened its mouth, which is exactly why the payout hasn't caught up to the good news yet. The margin benefit Macquarie is modelling doesn't fully land until 2027, once SORA itself moves. Iggy's Forensic Zone on this one is Caution.

My Personal Take

This is the trap with a genuinely good structural story: the market prices the story faster than it prices the actual cash reaching your account. If you're eyeing UOB for CPF or SRS income off the back of this week's hike, the loan book math is real, but the yield gap widening instead of closing is the number that should slow you down, not the headline. Full breakdown of the SORA transmission timeline and why 2027 matters more than this week's rate decision is in today's video.

📺 Free YouTube: https://youtu.be/szhx0RsP10o

⭐ Members Edition YouTube: https://youtu.be/kgLS90QGxR8

📩 Substack: https://investingiguana.com/p/uob-has-the-most-to-gain-from-the


Get full-length videos and full Substack analysis on both platforms, plus the full Red Zone watchlist and analyst cheatsheets, with the YouTube/Substack Combo, S$12/month.

Not financial advice. Iggy's Forensic Compliance Standards apply.

Cheers, Iggy 🦖

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
UOB's Structural Win, Yield Gap Widen 19 September 2 2026,Morning 43% Advantage
T
TheInvestingIguanaSep 18 at 10:01 PM

Iggy's Journal: A Quick Change to How Videos Come Out

19 September, AM


Programme Note

Starting with Episode 1824 - UOB Has the Most to Gain From the Fed's Return to Rate Hikes, the YouTube video for each long form piece goes up the same day as the Substack article instead of a week later.

If you're on the free side, your video will now play up to the same point where the Substack article's free section stops, then end there, rather than staying members only for a week and then opening up in full. If you're on YouTube Only (S$5) or YouTube/Substack Combo (S$12), nothing changes for you beyond timing: you still get the full forensic video. Find it in the new Members Edition playlist.


If you're on Substack Only (US$8), that tier covers the full written analysis, not video. The free video will now be embedded near the start of the article, so you'll be able to watch that version inline. YouTube/Substack Combo (S$12) holders will find the full forensic video embedded further down, past the paywall break.


My Personal Take

This change is my effort to bring Substack and YouTube onto the same clock. It means YouTube content goes out without the old 7-day paywall delay. If you're not yet a paying member, you'll still get to watch the bulk of the video, just not the forensic insights that come with being Elite.


Not financial advice. Iggy's Forensic Compliance Standards apply.

Cheers, Iggy 🦎

Choose Your Access Level Same Forensic Standard. Different Access. YouTube Only
T
TheInvestingIguanaSep 18 at 07:58 AM

Iggy's Journal: Same Overseas Exposure, Very Different Damage

18 September 2026, Evening

Video Release

I used to treat "overseas exposure" as the warning label on a REIT. I don't think that's the sharp question anymore. The sharper one is which overseas bond market is actually setting the discount rate on those overseas properties, because three REITs with foreign exposure just got treated nothing alike.

The Numbers

Mapletree Pan Asia Commercial Trust took only a 2.3 percent cut, landing at S$1.71. CapitaLand Ascott Trust and Frasers Logistics and Commercial Trust weren't nearly as fortunate, down 27.5 percent and 27.8 percent respectively. All three REITs hold property outside Singapore. The gap between a 2.3 percent hit and a 27.8 percent one isn't explained by overseas exposure alone.

What separates them is where that overseas exposure sits. Singapore's 10 year bond yield was 2.36 percent. Australia and the UK were both sitting around 5.2 percent, the US around 4.9 percent. A REIT holding assets discounted off a 2.36 percent yield is in a completely different position than one holding assets discounted off a yield more than double that.

My Personal Take

I'm not reading this as a forecast for where distributions go next. What I am taking from it is a reminder that valuation risk can show up through the bond market before anything visibly changes inside the buildings themselves. If you're holding any of these three in a CPF, SRS, or dividend portfolio, the question worth asking isn't "how much overseas exposure," it's "overseas exposure to which bond market." Full breakdown of the country-by-country math is in today's video and on Substack.

📺 YouTube: https://www.youtube.com/watch?v=1GNdkZP9w4U

📩 Substack: https://investingiguana.com/p/why-singapores-236-bond-yield-is


Not financial advice. Iggy's Forensic Compliance Standards apply.

Cheers, Iggy 🦖

Why Singapore's 2.36% Bond Yield Is Splitting the S-REIT Sector in Two 🦖

Why Singapore's 2.36% Bond Yield Is Splitting the S-REIT Sector in Two 🦖

🟢 Singapore's bond yield barely moved this year. That 24bp calm is why some S-REITs held their target prices while others got cut by nearly 30 percent.UOB K...

YouTube
Overseas Exposure: lt's About the Bond Market |18 September 2026 REIT PERFORMANC
T
TheInvestingIguanaSep 18 at 06:36 AM

Iggy's Journal: The Fed Hiked. Singapore Hasn't Felt It Yet.

18 September 2026, Afternoon

Podcast Release

Everyone's reading this week's Fed hike as a US story. It isn't, not entirely. The part that actually matters to you sits three steps downstream, in the way SORA tracks global funding costs with a lag. The pressure from a 10 year Treasury yield above 5 percent for the first time since 2007 hasn't even fully reached Singapore's shores yet.

The Numbers

UOB Kay Hian downgraded DBS to Sell this week on the back of the oil shock story. The rating is the headline, the balance sheet underneath it is more complicated. DBS's net interest margin eased to 1.87 percent from 1.89 percent, a small move in the wrong direction. But NPL stayed flat at 1 percent and CET1 held at 16.6 percent. That combination reads as margin drift, not a capital problem and not a credit problem. Those are different risks, and only one of them is what a Sell rating usually implies.

My Personal Take

If you're holding DBS in a dividend portfolio, or you're watching REIT refinancing costs from the sidelines, the instinct is to react to the rating. I'd rather watch the chain. A margin easing eight basis points while asset quality and capital both hold steady is not the same story as a bank whose fundamentals are cracking, and conflating the two is how a downgrade headline does more work on your portfolio than the actual numbers justify. Full walk-through of how the Fed hike, the bond market, and this rating actually connect is in today's episode.

📺 YouTube: https://youtu.be/hNM4iC60j9s

📩 Substack: https://investingiguana.com/p/a-fed-hike-a-war-and-a-bond-yield

Not financial advice. Iggy's Forensic Compliance Standards apply.

Cheers, Iggy 🦖

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
图片 1,共 1 张
T
TheInvestingIguanaSep 17 at 07:58 AM
Featured

Iggy's Journal: The Dividend Raise Everyone's Celebrating, and the Line Nobody's Reading

17 September 2026, Morning

Video Release

Venture just raised its dividend by 20 percent. That's the headline everyone's clapping for. The number that actually matters is sitting three lines below it in the cash flow statement, and it tells a different story.

The Numbers

Operating profit before working capital changes came in at S$154.0 million, a healthy figure on its own. What actually reached the bank was S$12.9 million, a tenth of that. The company points to an inventory build behind the growth, and that's plausible, but it means this half's dividend wasn't funded by cash this half actually earned.

At S$16.67, the 80 cent trailing dividend works out to a 4.80 percent yield, clearing my 4.7 percent hurdle by all of 10 basis points. That's a thin cushion sitting on top of a cash conversion gap, not underneath a comfortable one. Iggy's Forensic Zone on this one is Watchlist. The balance sheet, S$1,108.5 million net cash, zero debt, can absorb a rough half. Your yield cushion has a lot less room to.

My Personal Take

I get why the dividend raise is getting the applause, 20 percent is a real number. But a raise funded by a cash conversion shortfall instead of a cash conversion surplus is exactly the kind of thing that looks fine right up until it doesn't. Full breakdown of how I'm reading the inventory story against the cushion math is in today's video and on Substack.

📺 YouTube: https://youtu.be/P0uC2qns2qQ

📩 Substack: https://investingiguana.com/p/the-s11-billion-question-behind-ventures

Get everything, zero-day access on both platforms, full Red Zone watchlist, institutional-grade cheatsheets, with Iggy's Elite Investors, S$12/month.

Not financial advice. Iggy's Forensic Compliance Standards apply.

Cheers, Iggy 🦖

The S$1.1 Billion Question Behind Venture's Dividend Raise 🦖

The S$1.1 Billion Question Behind Venture's Dividend Raise 🦖

🟢 A 20% interim dividend hike, a fortress balance sheet, and a cash flow number that doesn't quite add up.Venture just raised its dividend 20%, but the cash...

YouTube
Venture's Dividend Raise Masking  Cash Conversion -17 September r2026. .Morning
T
TheInvestingIguanaSep 16 at 10:02 PM
Featured

Iggy's Journal: Unanimous Doesn't Mean Painless

16 September 2026, Late Night

Podcast Release

3.75 to 4.00 percent. Zero dissents. The Fed just hiked for the first time since 2023, and every single voting member signed off on it, Warsh included.

What I'm Doing About It

I called a near-unanimous vote in my Longbridge prediction earlier tonight, reasoning that a hike priced above 90 percent tends to pull reluctant members into line rather than spark a fresh revolt. The actual vote landed even tighter than my range, fully unanimous, not just low dissent. I'm noting that miss on the exact number honestly rather than rounding it up to a win. What I'm tracking next is whether the one more hike penciled in for December actually shows up, and how SORA and the three local banks open when Singapore trades Wednesday.

The Numbers

The hike takes the Fed funds range to 3.75 to 4.00 percent. The 10 year US Treasury yield closed above 5 percent, its highest level since 2007. Officials penciled in one more hike by year end and none in 2027. Unemployment held at 4.1 percent even as job growth picked up in August, and the CBO estimates the Iran war adds roughly half a percentage point to inflation early next year through disrupted oil and shipping routes. Warsh named three things that changed since July, a stronger economy, inflation that didn't slow, and intensifying geopolitical tension, as his stated reasons for voting yes.

My Personal Take

What stands out to me isn't the hike itself, everyone saw that coming. It's the unanimity. A committee that was 9 to 3 in July closing ranks completely tells me the internal debate has shifted from whether to how much, and that matters more for SORA-pegged mortgages and every S-REIT on my board than tonight's quarter point does on its own. 

Good morning Singapore, your Wednesday is starting exactly as your Tuesday night wondered it might.

PS: I will cover the implications of this in a follow-up long form article soon. 


Cheers, Iggy 🦖

图片 1,共 1 张
T
TheInvestingIguanaSep 16 at 09:55 PM

Iggy's Journal: UOB Called REITs Calm. One REIT's Gearing Says Otherwise.

17 Sep AM (for you) 16 Sep PM (for me) 

Podcast Release

Same broker note, same day, two very different calls. UOB Kay Hian downgraded DBS to Sell and OCBC to Hold on an oil shock, then turned around and called S-REITs an oasis of calm. That phrase is doing a lot of work, so I went and checked one REIT's actual numbers instead of taking the label at face value.

The Numbers

Boustead REIT is where the calm-versus-scared framing gets tested. Gearing sits at 36.4 percent, a real miss against my own 35 percent threshold. But interest coverage comes in at 5 times against my 4 times floor, comfortably offsetting the gearing miss rather than compounding it. Occupancy is strong at 98.1 percent with a 5.4 year lease runway, and forward yield estimates cluster somewhere between 7 and 9 percent. I'm not treating that yield range as confirmed since this REIT only listed in March and has no trailing payout history yet.

My Personal Take

Rising bond yields are supposed to punish REITs through financing costs, that mechanic hasn't changed just because a broker used a nice phrase. What I think is actually happening is relative, not absolute: when banks start taking hits on an oil shock, a REIT with decent coverage and near full occupancy starts looking calmer next to them, even with a gearing number that would've bothered me on its own in a quieter week. While the rest of you are waking up in Singapore, it's time for me to go to bed in London. Good morning and goodnight! 

📺 YouTube: https://youtu.be/8Nwgc0lAD14

📩 Substack: https://investingiguana.com/p/uob-kay-hian-just-called-reits-an

Not financial advice. Iggy's Forensic Compliance Standards apply.

Cheers, Iggy 🦖

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
图片 1,共 1 张
T
TheInvestingIguanaSep 16 at 07:29 AM

Iggy's Journal: Flat on Top, Restless Underneath

16 September 2026, Afternoon

Market Update

STI sat at 5,636.1 as of 2.52pm SGT, down just 2.52 points on the day. Practically flat on the index. Look past the headline number though and a few names are moving with real conviction.

What I'm Doing About It

Keppel DC REIT is trading actively today but I'm holding off on any zone language for it. There's a two-gate escalation sitting in my notes that hasn't made it into the Ledger yet, so until that's resolved I'm tracking the price action without attaching a verdict.

The Numbers

CapitaLand Integrated Commercial Trust led the active board by volume, unchanged at S$2.270. CapitaLand Ascendas REIT was the stronger mover among the top names, up 0.86% to S$2.340. Keppel DC REIT slipped 0.47% to S$2.110 on heavy turnover, no verdict attached for the reason above.

Elsewhere on the board, Singtel eased 1.12% to S$4.400 and SIA fell 1.51% to S$6.510, both softer against a broadly flat index. Business Times reported UOBKH cutting its STI target and downgrading the banks on the back of the prolonged Middle East conflict, and separately flagged that Fed chair Warsh looks poised to raise rates for the first time under his watch, adding another thread to the yields story pressuring regional currencies.


My Personal Take

Honestly, a session like this is easy to scroll past. Index barely moved, so it looks like a nothing day. But Ascendas REIT catching a bid while Singtel and SIA both slip tells me the money isn't sitting still, it's just not agreeing on a direction yet. Not reading too much into one afternoon snapshot, especially with that STI target cut sitting in the background. Let the numbers speak, I'll pick this up properly at the close.

Not financial advice. Iggy's Forensic Compliance Standards apply.

Cheers, Iggy 🦖

图片 1,共 1 张
T
TheInvestingIguanaSep 16 at 06:05 AM

Iggy's Journal: Three Fair Value Numbers For One Stock, And I'm Not Picking A Winner

16 September 2026, PM

Podcast Release

New podcast's up today on UOB, and this one's less about the stock and more about a problem I ran into while trying to answer a simple question. Same stock, same day, same public data, and one data provider's own two models can't agree with each other. Analyst consensus sits near $42.98. That same provider's internal fair value model comes out at $36.37, below where UOB is actually trading. Two numbers from one source, supposedly measuring the same thing, landing on opposite conclusions.

I'm not issuing a zone verdict on this one. Not because I couldn't pick a number and move on, but because the sources themselves disagree, and manufacturing certainty where the data has none isn't the kind of forensic work I want to be doing. A crowd model and analyst consensus both point to roughly a 5% discount. An internal model says the market's already paying too much. There's also a 3.9% dividend yield figure floating around that I haven't verified against a second source, so that stays out of the conclusion entirely until it checks out properly.

My Personal Take

Honestly, this episode started as a straightforward "is UOB cheap" question and turned into something more useful, a look at how easily two models from the same shop can disagree without anyone flagging it. That's the kind of thing that should make you pause before treating any single fair value number as settled fact, mine included. If you hold UOB for CPF or SRS income, the honest answer today really is "unresolved," not a hedge, an actual accurate description of where the numbers sit. Worth the listen if you want to see how I sat with that instead of forcing a tidy conclusion just to have one.

📺 YouTube: https://youtu.be/vxjZ58M8QMg

📩 Substack: https://investingiguana.com/p/uobs-fair-value-is-43-43-or-36-depending

Not financial advice.  

Cheers, Iggy 🦖

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
图片 1,共 1 张
T
TheInvestingIguanaSep 15 at 03:17 PM

Iggy's Journal: The Number Everyone's Watching Isn't The Fed, It's The 10-Year

15 September 2026, Late Night

Quick one before I turn in, still adjusting to UK time. The US 10-year Treasury yield ended last week at 4.97%, just below 5%. It briefly traded above 5% on Monday, but hasn't recorded a daily close above that level since 2007. JPMorgan strategists now see a quarter point hike as likely at the Fed meeting concluding Wednesday.

What I'm Doing About It

Higher global yields can affect financing conditions here, but that's not the same as saying it moves SORA directly, SORA responds to Singapore dollar money market conditions and MAS policy settings. What I'm actually doing is watching Lendlease and Keppel DC's coverage ratios more closely this week, not because either has a new problem, but because that's the channel worth tracking if borrowing costs drift higher.

The Numbers

August core CPI rose 0.3% month on month, 0.1 point above forecast, annual core rate held at 2.4%, in line with expectations. That pushed futures to price roughly a 90% probability of a hike this week. One portfolio manager called the Fed "behind the curve," expecting yields higher regardless of Wednesday. JPMorgan's desk sees a hike as likely but stays bearish on long end Treasuries given possible reactions to the statement and Chair Warsh's press conference.

My Personal Take

The 5% level itself doesn't mean much mechanically, nothing structurally different happens crossing a round number. But markets treat round numbers as decision points anyway, and that alone can move things. I'd rather watch how Wednesday's decision gets received than react to a yield print from before it.

Cheers, Iggy 🦖

Iggy's Journal: The Number Everyone's Watching Isn't The Fed, It's The 10-Year 1
T
TheInvestingIguanaSep 15 at 03:36 AM
Featured

Iggy's Journal: Fed Week Begins, And So Does My Detour Through Abu Dhabi

15 September 2026

Posting later than usual, I'm transiting through Abu Dhabi airport en route to London. Also can't believe we're already mid-September.

STI is down 61.84 points to 5,656.2 this morning, extending lower after Monday's small gain. Backdrop: 10-year Treasury yield at its highest since 2023, Brent crude spiking as high as US$109 intraday on a Saudi pipeline shutdown, and the Fed's two-day meeting starts today.

OCBC is the standout mover, down 2.07% to S$31.19. Worth being precise, this is a capital strength call, not a yield call. Trailing yield still doesn't clear my income threshold at current prices. Addvalue Technologies traded heaviest volume again, flat at 0.187, same growth-not-income story as every week. Lendlease REIT eased 0.92% to 0.540, no price reaction yet to the thin interest coverage I've flagged.

My Personal Take

Watching a red morning unfold from an airport lounge is a strange way to experience a session. Reminds me none of this needs me hovering over it live. Fed decision lands over the next two days, still rather wait for that than react to one red morning driven mostly by oil.

What I'm Doing About It

Nothing drastic. Not touching my OCBC tracking off one session. Watching Lendlease more closely this week, thin coverage plus rising borrowing costs is exactly the combination I said I'd revisit. Holding off any fresh read on Keppel DC or the banks until the Fed decision actually lands.

Postings may run later or less predictably over the next week and a half while I'm in London. Nothing changing underneath.

Not financial advice. Iggy's Forensic Compliance Standards apply.

Cheers, Iggy 🦖

Iggy's Journal: Fed Week Begins, And So Does My Detour Through Abu Dhabi 15 Sept
T
TheInvestingIguanaSep 15 at 03:06 AM

This is a very useful summary. Great initiative!

C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — AI Slowdown Fears Crash Chips, Ignite Cybersecurity

Anthropic, OpenAI and xAI's CEOs called for slower AI development this weekend — Trump dismissed it as a "hoax" live with Nvidia's Jensen Huang. Chip stocks crashed while cybersecurity surged as the "...

T
TheInvestingIguanaSep 14 at 04:48 AM

FeaturedMaybank’s BUY Case for Addvalue Rests on a Viasat Deal. My Screen Runs on a Different Number Entire

Maybank’s BUY Case for Addvalue Rests on a Viasat Deal. My Screen Runs on a Different Number Entirely.Third-party validation from a US partner and a zero-dividend balance sheet are two different quest...

Maybank's BUY Case for Addvalue Rests on a Viasat Deal Third-party validation an
Every BUY Call Needs a LCTEAN Story fle Column Chart with Index Labels Maybank's
Strong Results-Not in Dispute 59.9% 147.5% 0% Revenue Growth Net Profit Growth D
2 In hThis Article+18
NASDAQ Composite Index

NASDAQ Composite Index

US.IXIC

Stock Safety AuditAnalyst Ratings Review
T
TheInvestingIguanaSep 14 at 04:42 AM
Featured

Iggy's Journal: The Best Yield In Singapore Isn't On Any Exchange

14 September 2026, PM

Podcast Release (Iggy Answers)

 CPF Special Account pays 4.0% a year, guaranteed, and it doesn't move when the Fed does something or oil spikes past US$100. That single guaranteed number is the reason my forensic floor sits at 3.2% and my real hurdle sits at 4.7%. Most dividend names and REITs never actually clear that 4.7% bar, and yet they still get called good yields by people who never ran the comparison.

The uncomfortable question this episode sits with, if a REIT is yielding 3.8% and carrying real equity risk on top of that, what exactly is it beating. Not the risk free rate on paper, the actual guaranteed rate many of you already have access to. That gap between "sounds like a decent yield" and "actually clears the bar I'd set for taking on equity risk" is the whole episode.

My Personal Take


Genuinely, this is one of those numbers that should embarrass more of the market than it does. CPF SA sitting quietly at 4.0%, guaranteed, no research required, no forensic audit needed, and yet plenty of dividend portfolios are built around yields that don't even beat it. I'm not saying move everything into CPF SA, that's not the point and I know the liquidity trade offs are real. But the next time a 3.8% yield gets called attractive, ask what it's actually competing against before deciding it's worth the equity risk. Worth the listen, kopi-o in hand, let the numbers speak on this one because they're not flattering to a lot of what passes for income investing here.

📺 YouTube: https://youtu.be/RSSY3vhs2bw

📩 Substack: https://investingiguana.com/p/the-toughest-yardstick-in-singapore

Cheers, Iggy 🦖

- YouTube

- YouTube

YouTube 上盡享你喜愛的影片和音樂、上載原創內容,並與親友和世界各地的人分享。

youtu.be
图片 1,共 1 张
T
TheInvestingIguanaSep 14 at 12:38 AM
Featured

Iggy's Journal: Trading Volumes Are Up 35%, The Index Itself Just Had A Rough Week

14 September 2026, AM

Morning Read

Wall Street closed out last week strong, S&P 500 up 0.86%, Nasdaq up 0.96%, Dow up 0.98%, snapping a four day losing streak. Brent crude retreating nearly 3% did most of the work there, easing the inflation worry that had been building all week. Worth noting though, that calm came even as bond markets were pricing in a firmer case for the Fed to hike this week, the exact gap I flagged in Friday's podcast, SORA can look calm while the pressure underneath it is already building.

STI didn't get the same relief. Full week closed down 1.83% to 5,695.93, four straight down sessions before Friday's small 0.11% bounce, with DBS, OCBC and UOB absorbing most of the profit taking as oil and yields did their thing. And this morning's Business Times headline is already flagging oil jumping again on a Saudi pipeline shutdown, so whatever eased things Friday in the US may not carry through to today's SGX open.

One number worth sitting with from the weekend papers, SGX securities trading value climbed 35% year on year in August, driven by retail buying and the STI rally. Participation is up sharply even in a week the index itself struggled. Worth remembering those are two different stories, more people trading is not the same as the index performing well, and it's useful to know which one you're actually part of.

My Personal Take

Heading into a week where the Fed meets Tuesday and Wednesday, and honestly I'd rather anchor on that date than react to a Monday morning oil headline that could look completely different by Wednesday. Reminder too, I'm off to London shortly for the teaching side of things, so if postings land a bit later or less often than usual over the next week and a half, that's the reason, nothing changing in how I'm tracking the numbers. Have a good week ahead, Iguanas, kopi-o and steady hands this one.


Cheers, Iggy 🦖

图片 1,共 1 张