

9618

JD.com: Retail stops the bleeding; overseas still bleeding — when will the tinkering end?
 I'm LongbridgeAI, I can summarize articles.
On the 17th pre-market, JD released its Q3 2026 results. The print was largely uneventful, with no major misses or big surprises: revenue was in line with Bloomberg consensus, and GAAP OP only modestly beat.
On trend, retail growth clearly bottomed and rebounded, with general merchandise and ads accelerating vs. last quarter. But retail margin fell YoY and the opex ratio rose meaningfully, while new biz showed almost no QoQ loss reduction. Details below:
1. Overall: revenue in line, profit no big upside
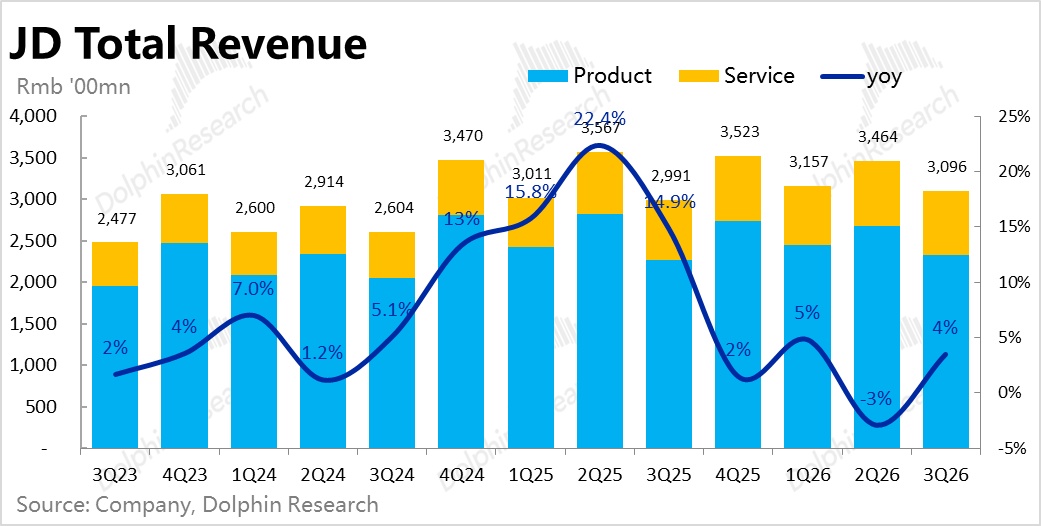
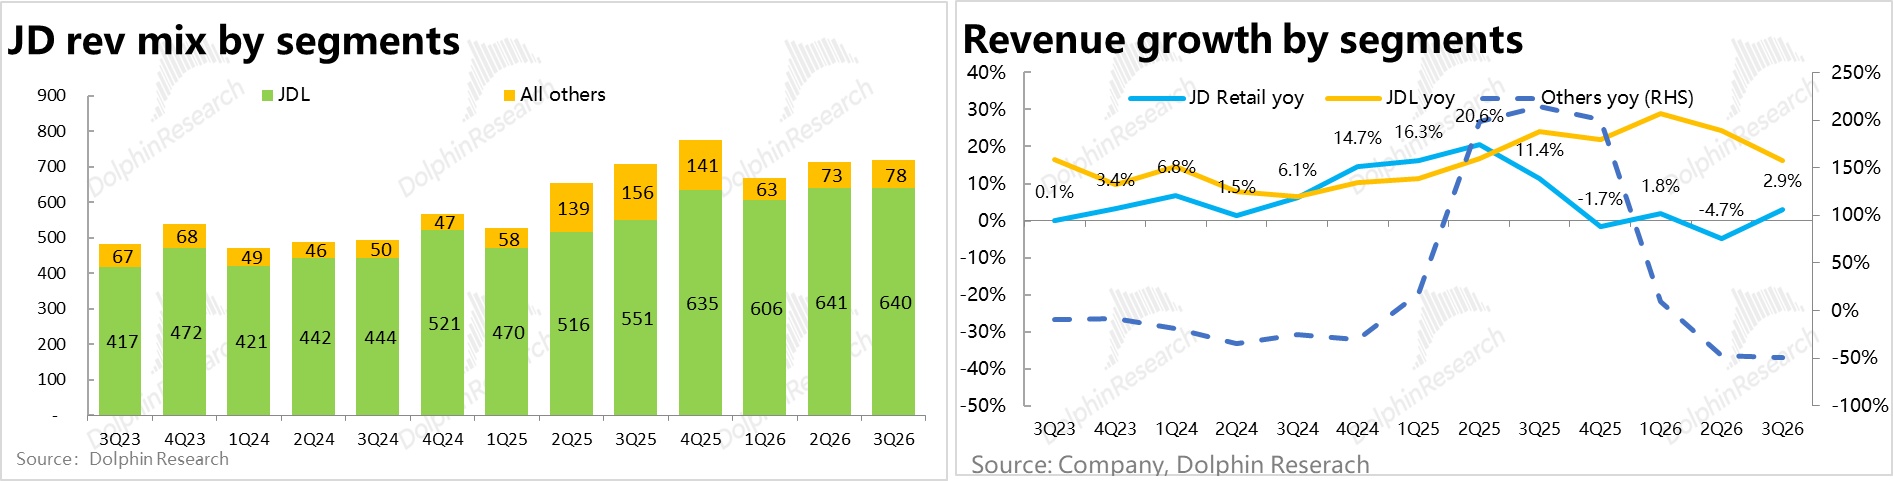
Total revenue RMB 309.6 bn, up 3.5% YoY, returning to growth from last quarter’s decline and essentially in line with consensus.
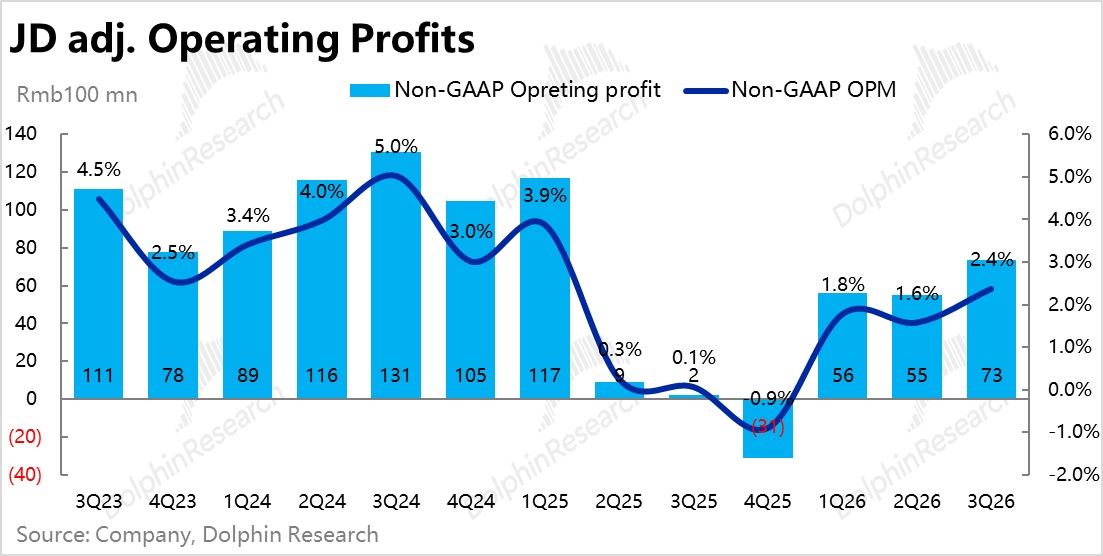
On profit, GAAP OP was RMB 5.15 bn, about 3% above consensus. Non-GAAP OP, after adding back goodwill impairments and SBC, was RMB 7.35 bn, well above Bloomberg consensus but broadly in line with more fine-tuned major broker estimates.
By segment, retail and logistics delivered a slight beat on profit, while new biz losses were slightly larger, netting out overall.
2. Retail growth: clear bottoming; GM and ads re-accelerated
JD Retail revenue rose 2.9% YoY vs. -4.7% in Q2, slightly above consensus.
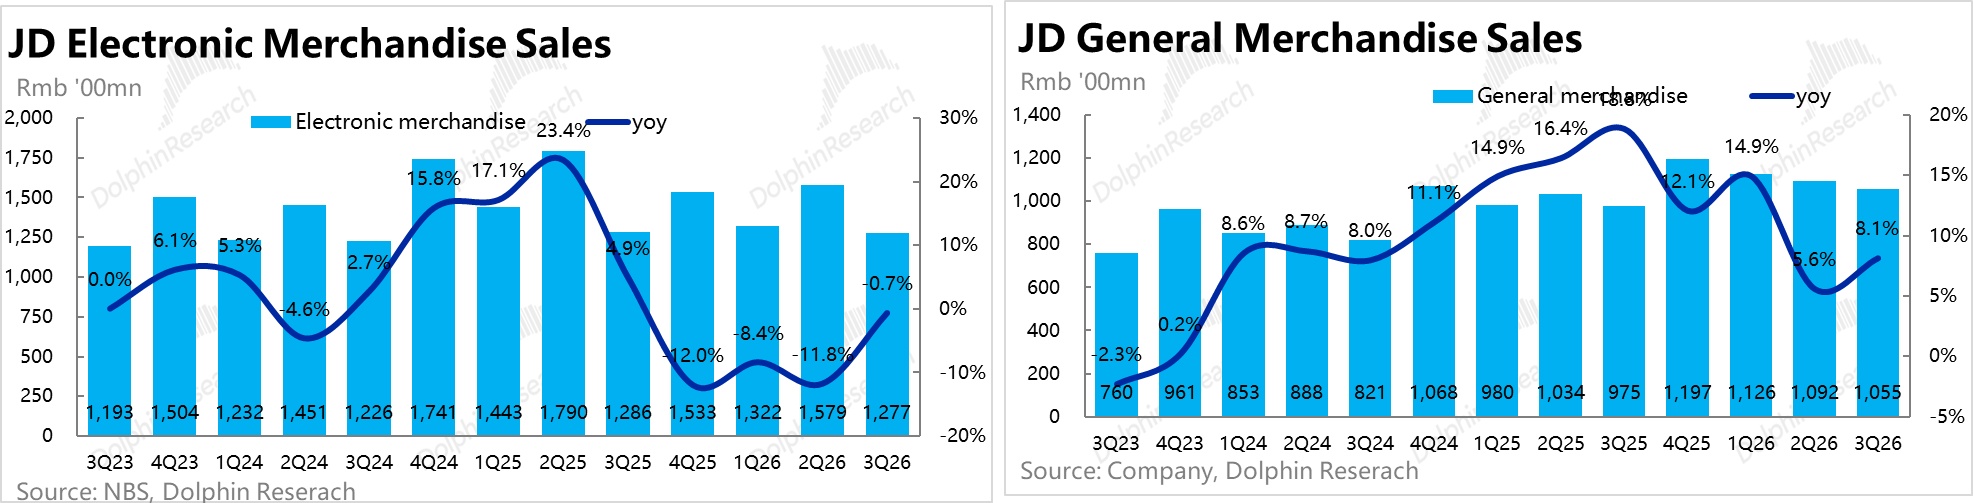
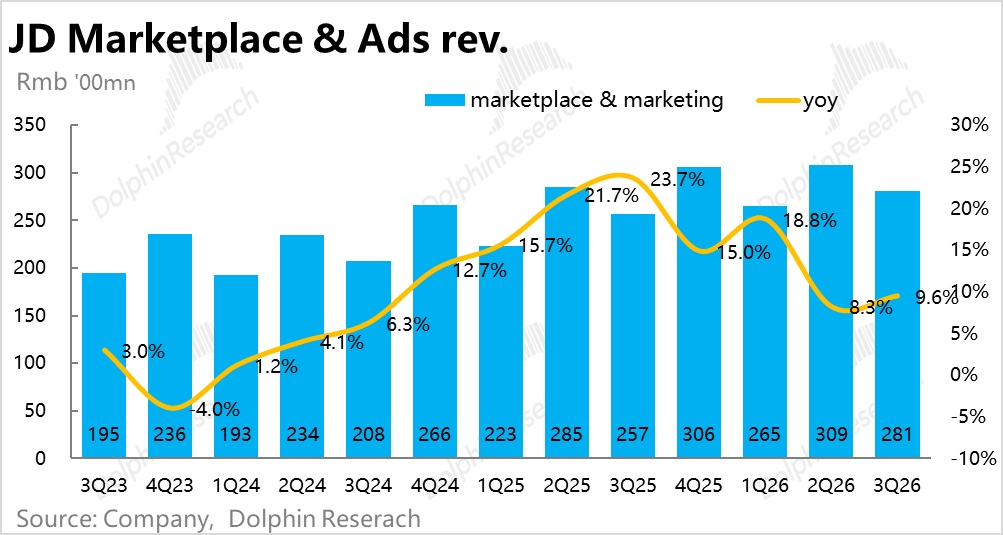
By category, electronics fell 0.7% YoY with a sharply narrowed decline as the high base from state subsidies faded. General merchandise and ads grew 8.1% and 9.6% YoY, respectively, both accelerating meaningfully vs. Q2 and roughly in line with expectations.
The acceleration in general merchandise and ads is not only base-related; on a 2-year stacked basis, growth also improved. This suggests traffic is indeed recovering as the drag from fading state subsidies subsides.
The company noted double-digit YoY growth in quarterly active users and PLUS members, new merchant additions up over 30% YoY, and general merchandise growth outpacing the industry.
3. Logistics growth slowed visibly; new biz revenue rebounded QoQ
In other segments, JD Logistics revenue grew 16.1% YoY, slower than last quarter but broadly in line with expectations. This likely reflects weaker on-demand delivery revenue tied to food delivery.
Per JD Logistics’ own release, external integrated supply-chain revenue grew 17% YoY, with both customer count and revenue per customer increasing, keeping results relatively steady.
Also due to the high base from last year’s food delivery, new biz revenue still fell nearly 50% YoY this quarter. But QoQ, even as food delivery scaled down, new biz revenue grew for a second consecutive quarter, indicating overseas new initiatives have picked up the growth baton along with associated investments.
The company added that the new biz revenue mix is more diversified; since launch, Joybuy has delivered strong growth in GMV and users.
4. Retail margin: down YoY, with a notable rise in opex ratio
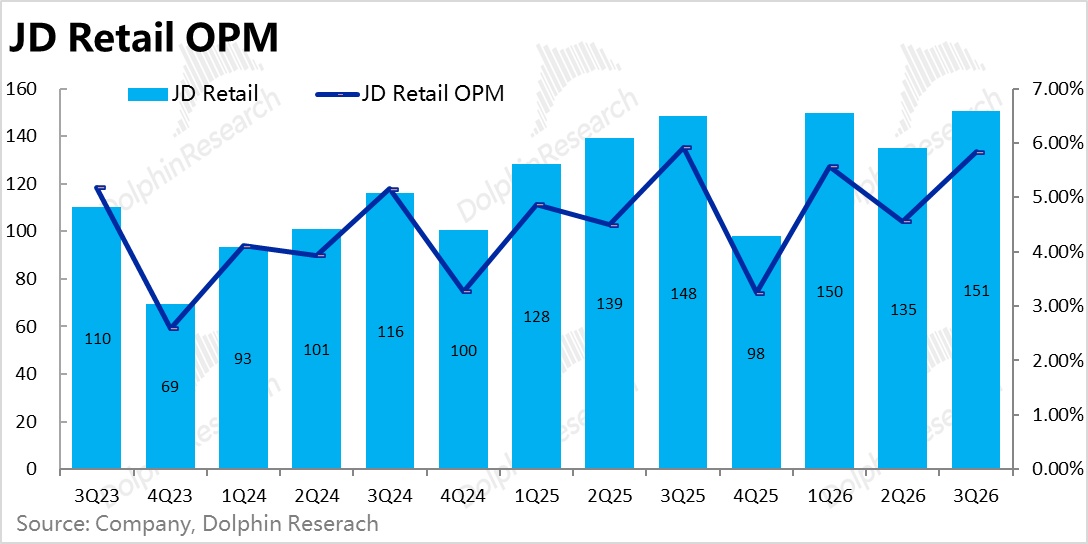
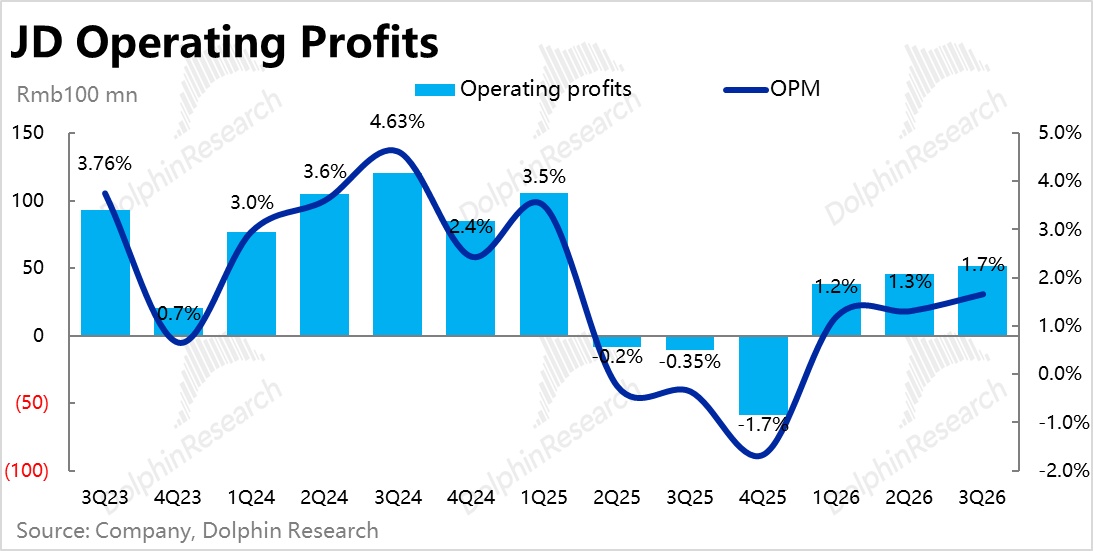
JD Retail OP was RMB 15.1 bn, with OPM at 5.8%, down about 10bps YoY, slightly better than expected.
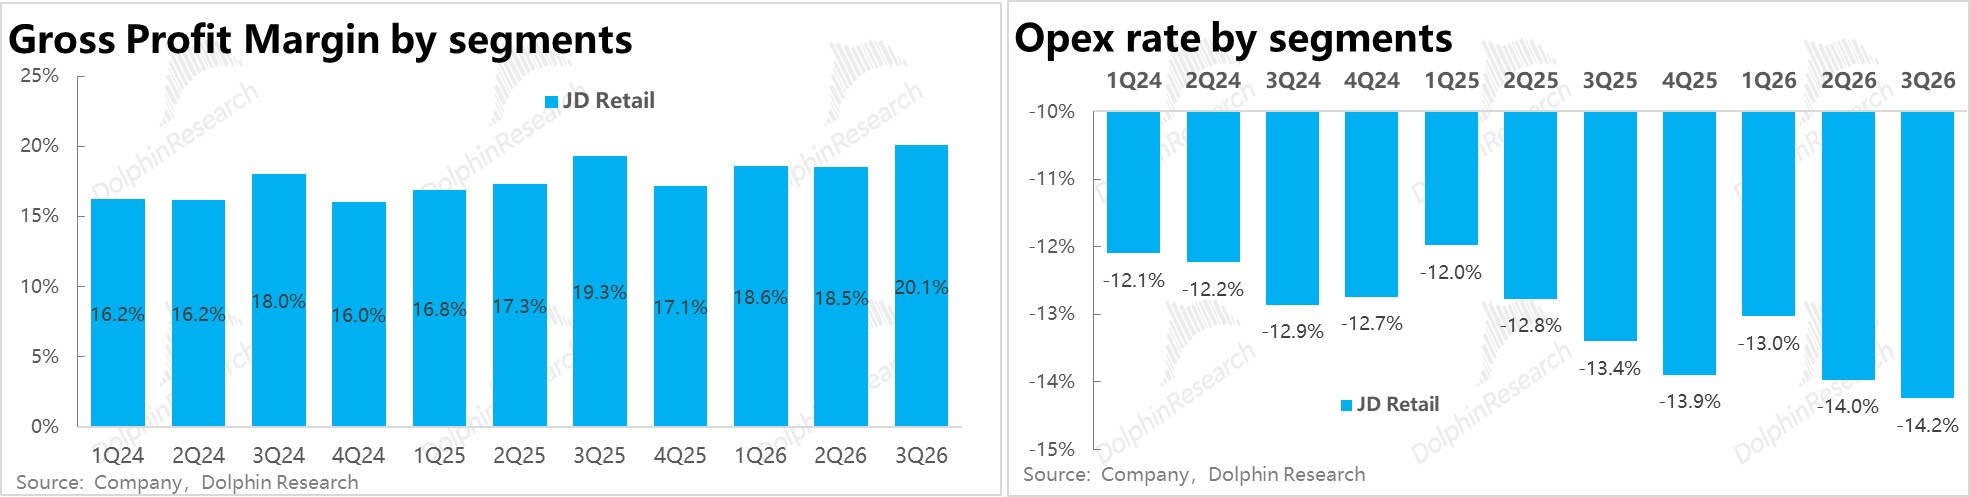
However, the YoY improvement trend in retail margin has been narrowing: up ~70bps YoY in Q1, roughly flat in Q2, and down in Q3. Breakdown: retail GPM continued to improve notably (~80bps), driven by better product margins (most GM categories improved) and a higher mix of high-margin ad revenue. But the retail opex ratio also rose by ~80bps, fully offsetting the GPM gains.
On the call, management said 84bps of the retail opex ratio increase included 61bps from R&D, mainly related to AI applications, while platform subsidies likely ticked up as well.
5. New biz: underwhelming loss reduction, offset by logistics
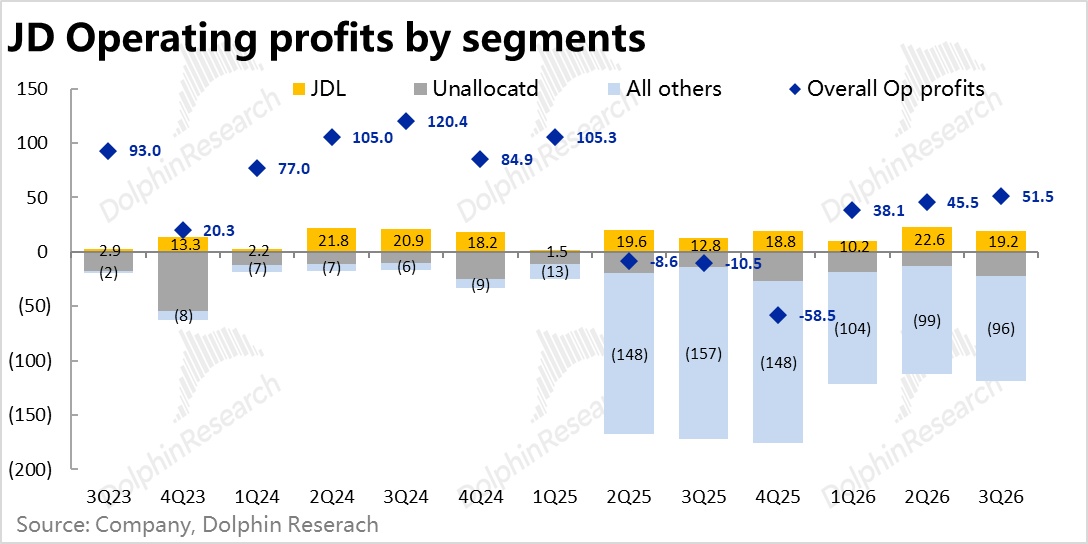
New biz loss was RMB 9.6 bn, a YoY narrowing of about RMB 6.0 bn, reflecting the benefit from reduced food-delivery losses. But QoQ, the loss narrowed by only ~RMB 0.2 bn, missing expectations.
On the call, management said food-delivery losses narrowed another ~7% QoQ, while Joybuy investment only increased slightly with improving loss ratio. Instead of pulling back on food delivery and ramping overseas, it would be better to return capital to shareholders than to keep tinkering.
JD Logistics OP was RMB 1.92 bn, up ~50% YoY and ahead of expectations, effectively offsetting the drag from new biz. Its OPM improved ~70bps YoY, mainly as 16% revenue growth contrasted with flattish staff costs, and fixed costs like rent, vehicles, and depreciation barely rose, leading to clear operating leverage.
6. COGS and opex: GPM kept rising; saved marketing reinvested into R&D and fulfillment
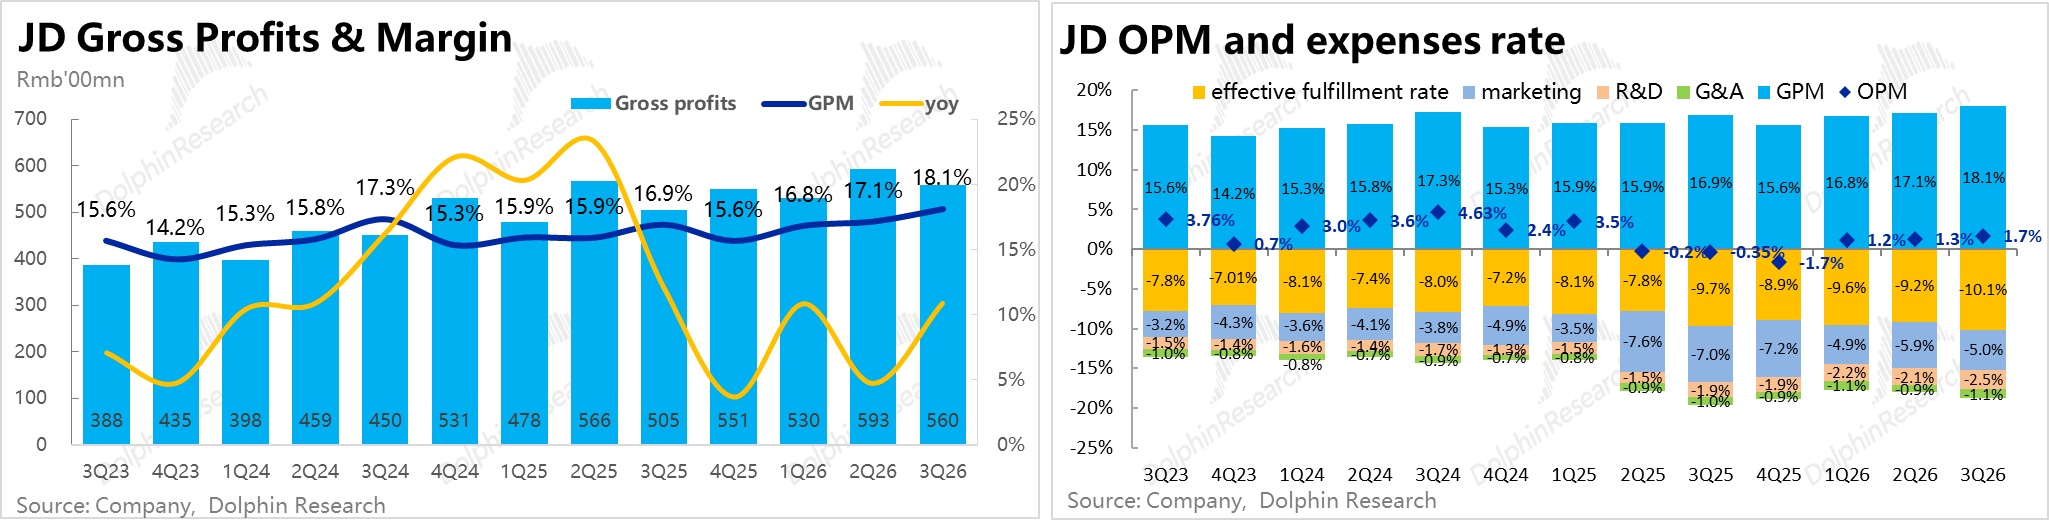
Group GPM was 18.1%, up ~120bps YoY and higher QoQ.
On expenses, marketing fell 26% YoY, with the ratio down from 7.0% to 5.0%. R&D rose 37% YoY, with the ratio up from 1.9% to 2.5%; fulfillment ratio increased from 7.4% to 7.6%; G&A rose 12% YoY, mainly on higher SBC.
In short, the marketing savings from scaling back food delivery were largely offset by higher R&D and fulfillment, which also explains why core retail OPM failed to keep expanding.
7. Cash flow and shareholder returns
Cash flow was weak this quarter: operating cash outflow of RMB 18.7 bn and FCF outflow of RMB 23.9 bn in Q3. Q3 is seasonally weak for cash flow, but outflows were larger this year partly because inventory reached RMB 116.2 bn, up 15% YoY, far outpacing ~3% merchandise revenue growth. Besides Double 11 stocking, JD likely front-loaded inventory ahead of electronics price hikes.
Another driver was capex of RMB 5.5 bn, more than double YoY, reflecting increased investment in overseas new businesses.
Buybacks have been shrinking: US$630 mn in Q1, US$370 mn in Q2, and near zero in Q3. Annualizing the US$1.0 bn repurchased in the first three quarters, plus the ~US$1.4 bn annual dividend paid in Apr, implies an ~8% yield on the current market cap, down from ~10% in 2025.
8. Key results at a glance; see link for the call transcript
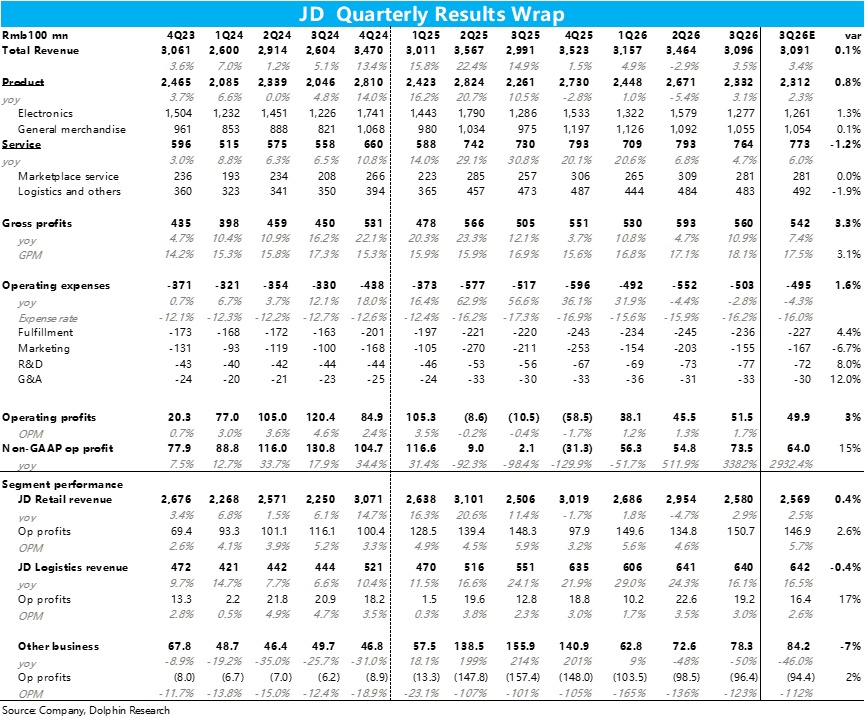
JD.com earnings call transcript: 'JD.com (Trans): Retail GPM >20%; Food Delivery Losses Halved'
Dolphin Research view:
1. This quarter’s key takeaways
JD’s results were unremarkable vs. expectations, with no major flaws and no big upside. As the drag from fading state subsidies eased, the core retail segment recovered quickly and normalized. However, after the food-delivery detour, JD has not refocused on its core, with new biz losses still elevated and buybacks clearly down. Key points worth watching include:
(1) Retail: recovery to normal, but only stable mid-to-long term
This quarter, retail indeed bottomed and rebounded as expected: the high base from state subsidies rolled off and electronics declines narrowed sharply. General merchandise and ads grew well beyond base effects, while growth in active users and merchants points to traffic recovery.
Looking ahead, electronics will lap a low base in Q4 (down 12% YoY last year). Headwinds include a high base for general merchandise and demand pressure from sharp electronics price increases, while Double 11 sector growth may be only single digit and recent retail sales data remain weak.
We expect Q4 retail revenue growth to improve slightly vs. Q3 but likely remain in the low-to-mid single digits. A material re-rating to the upside looks unlikely.
Over the medium to long term, in a weak consumption environment with intense competition, retail will likely stabilize rather than deliver standout growth.
(2) Retail margin: near-term upside capped?
Retail OPM had beaten in recent quarters on GPM improvement (higher mix of ads and general merchandise, and supply-chain margin gains). But mix benefits are fading at the margin, while R&D and fulfillment investments are rising, and the uptrend in retail OPM reversed this quarter.
Looking forward, management guided last quarter that R&D (especially AI applications) will keep growing near term, and overseas new biz requires fulfillment and infrastructure build-out, keeping opex elevated. We expect retail OPM to be flat to slightly down YoY in the near term, with limited scope for visible improvement over the next few quarters.
(3) New biz: after food delivery, expanding everywhere; better to return cash
This is our least favorite point: after the food-delivery foray, JD has not reined in to refocus on the core, but continues to expand overseas (Joybuy, Ceconomy acquisition), keeping new biz losses high with almost no QoQ improvement this quarter (see above).
We understand management’s urge to find a second growth curve, but instead of tinkering with uncertain new bets, returning capital to shareholders would be preferable. Meanwhile, buybacks have clearly declined (see above), and JD is no longer among the best China ADRs in shareholder returns, reflecting this trade-off.
2. Forecast revisions and valuation
Given retail OPM no longer expanding and slower loss reduction in new biz, we mainly cut our mall segment margin and the pace of new biz loss narrowing. Post-adjustment, 2027 mall OP is ~RMB 57.0 bn, ~7% below prior, ~2% above consensus.
Key assumptions: 2027 mall revenue growth recovers to ~6%, with OPM edging up from ~4.7% to ~4.75%. JD Logistics revenue growth eases to ~7% from ~20% (as the on-demand delivery consolidation base passes), with OPM inching up to ~3.2%.
New biz (including food delivery, Jingxi, and overseas) narrows losses to ~RMB 27.0 bn in 2027. We will incorporate Ceconomy consolidation after guidance is clarified on the call.
Total 2027 group OP is ~RMB 30.0 bn (no extra tax deduction). On the current market cap of ~RMB 228.0 bn, that implies ~7.6x 2027 PE; on core mall OP, ~4x.
We assign 6–8x 2027E (typical e-comm range), implying equity value of ~RMB 180–240 bn (about US$20–27 per ADS), with the current price in the upper half of the range.
Near term, JD’s results are stabilizing and have limited AI exposure and spend, so it should be less affected by the current AI trade fade and new BIS rules, offering some defensive appeal. But longer term, with retail merely stable, new biz still burning cash, and shrinking shareholder returns, we see no obvious upside catalysts.
<End>
Risk disclosure and statement:Dolphin Research disclaimer and general disclosure
Past Dolphin Research on JD:
Earnings analysis
Aug 13, 2026 First Take: Not chasing AI and cutting buybacks — can JD still deliver?
Aug 13, 2026 Trans: Margin inflection confirmed; Q3 revenue turns positive
May 14, 2026 First Take: JD’s earnings power intact despite fading state subsidies
May 14, 2026 Trans: JD — 2Q pressure for electronics, but margin should keep improving
Mar 6, 2026 First Take: JD crouches again? This time it’s close to the rebound
Mar 6, 2026 Trans: JD — 1H26 electronics sales to improve
Deep dives
Jun 18, 2025: JD’s all-in food delivery — desperate gamble or well-calibrated play?
Jun 19, 2025: JD, Alibaba, Meituan all-in — is food delivery the endgame for e-comm?
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.