

名创优品:国内狂飙,海外失速,“增收不增利” 何时是头?
 我是 LongbridgeAI,我可以总结文章信息。
On the afternoon of Nov. 17 (BJT), MINISO released Q3 FY2026 results. $名创优品(09896.HK) , $名创优品(MNSO.US).
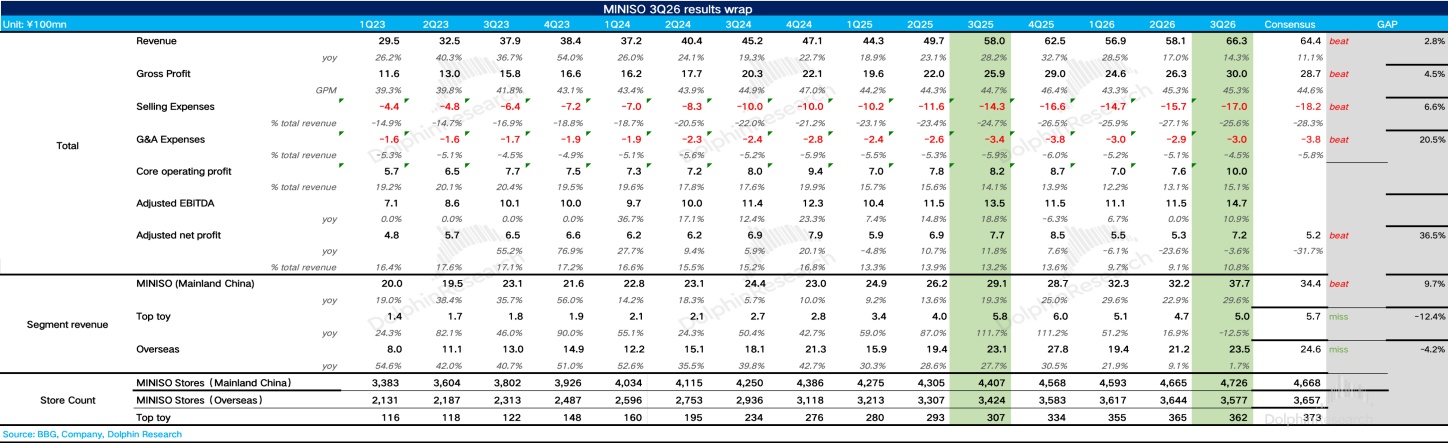
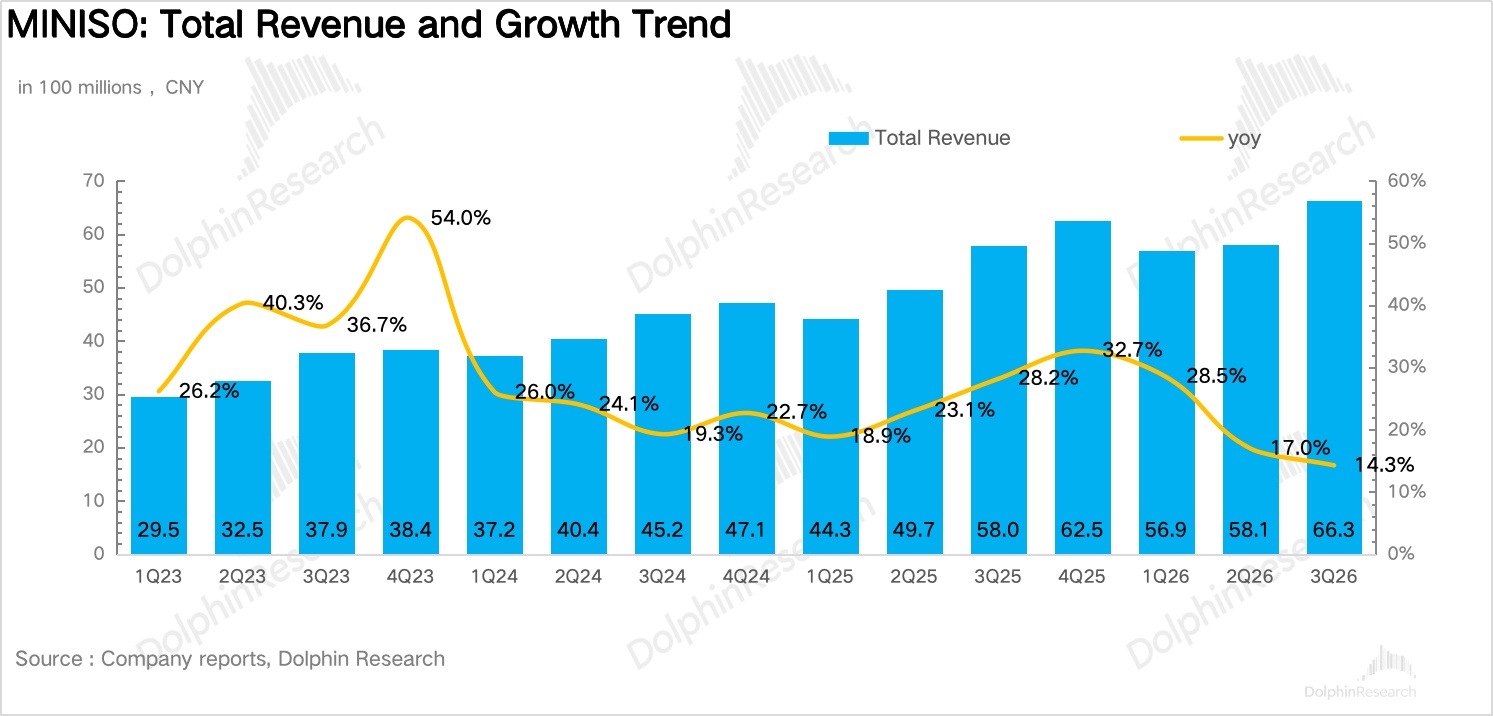
Overall, revenue beat again in Q3, with China delivering its best print in recent years. However, overseas slowed notably while opex ratios kept rising, and profits lagged revenue growth—the old issue of revenue up, profit not up persists.
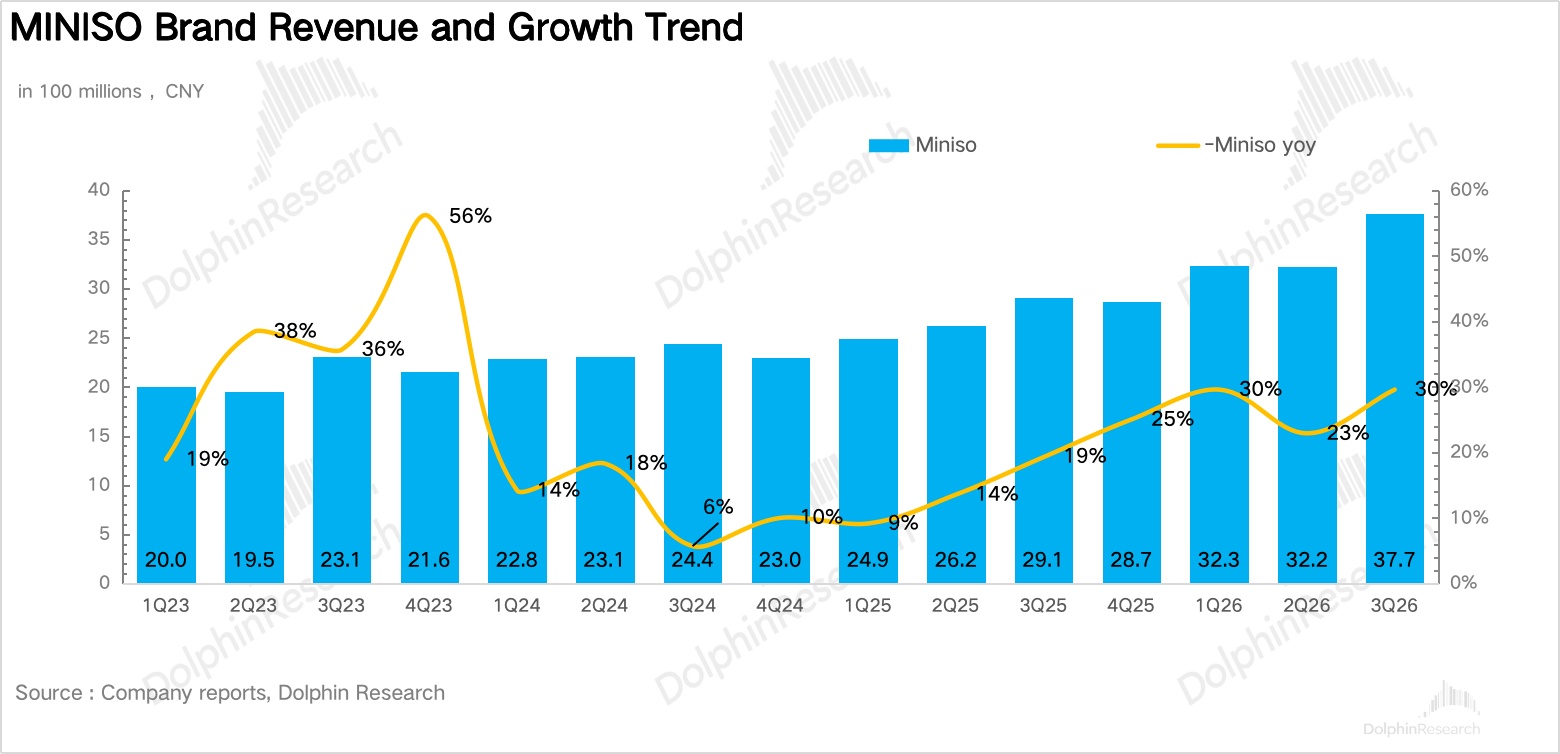
1) Revenue beat: strong China, weak overseas. Q3 revenue was RMB 6.63bn (+14.3% YoY). By segment, China grew 29.6% YoY to RMB 3.77bn and accelerated QoQ despite a high base last year. Same-store sales posted high single-digit growth for the sixth straight quarter, with clear lifts from large-format stores, IP-themed products, and owned IP.
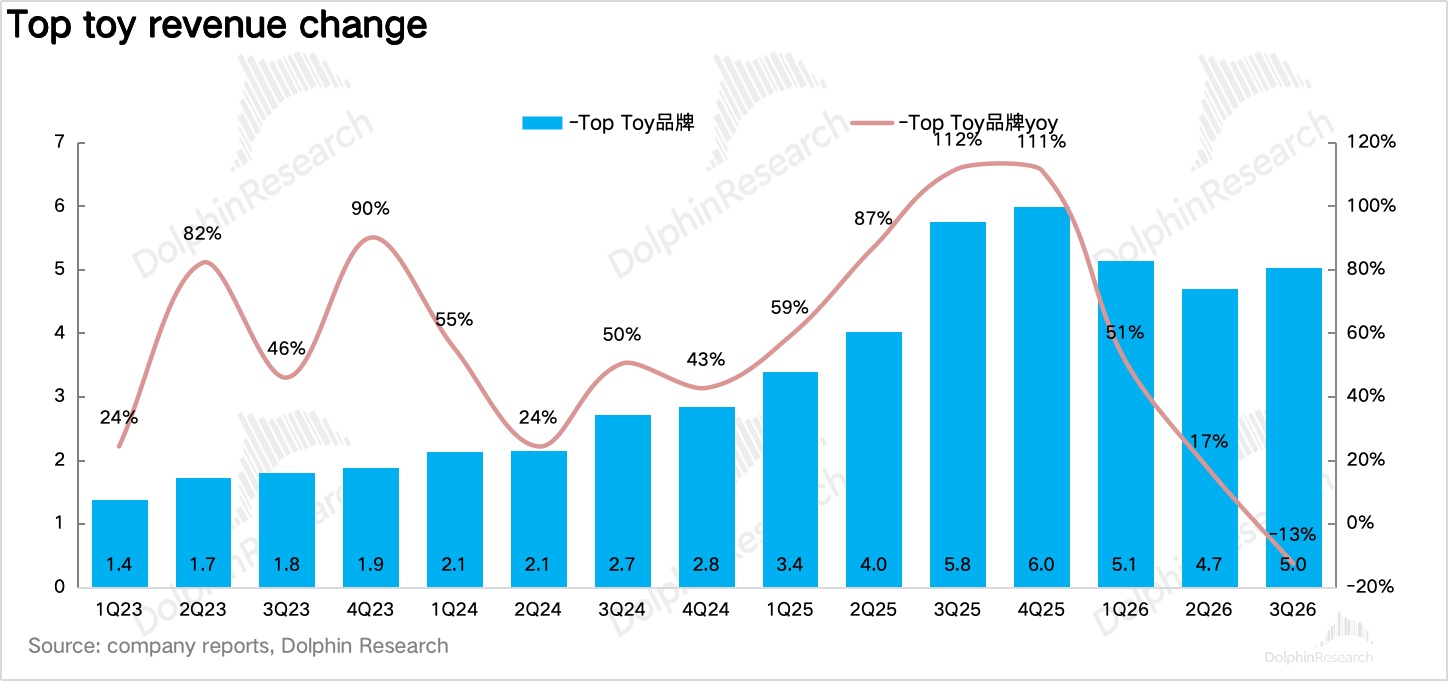
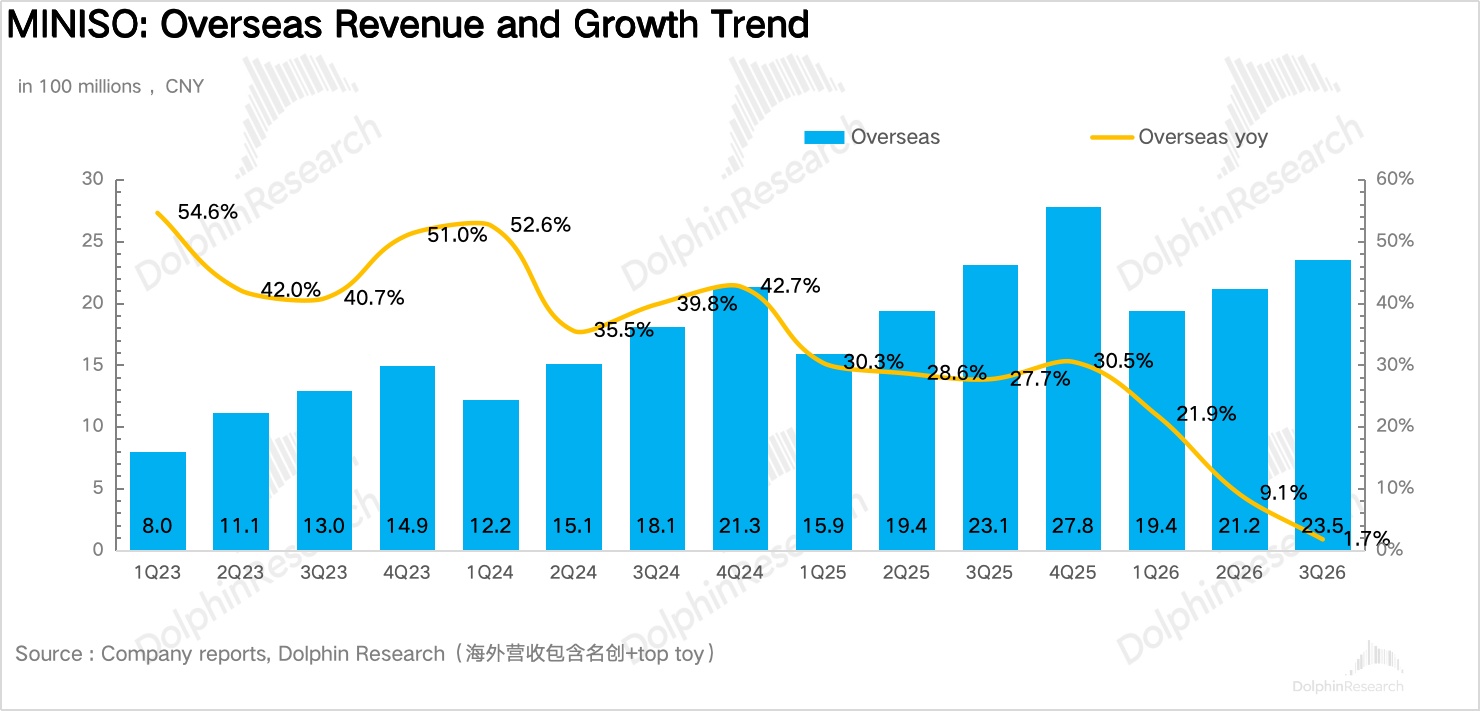
Overseas rose just 1.7% YoY to RMB 2.35bn, continuing to decelerate, mainly due to the deliberate pullback of distributor channels and a shift to self-operated stores. Distributor destocking and closures in SE Asia weighed on growth, though North America remained solid. TOP TOY fell 12.5% YoY to RMB 500mn, reversing from growth given last year's hot IP base.
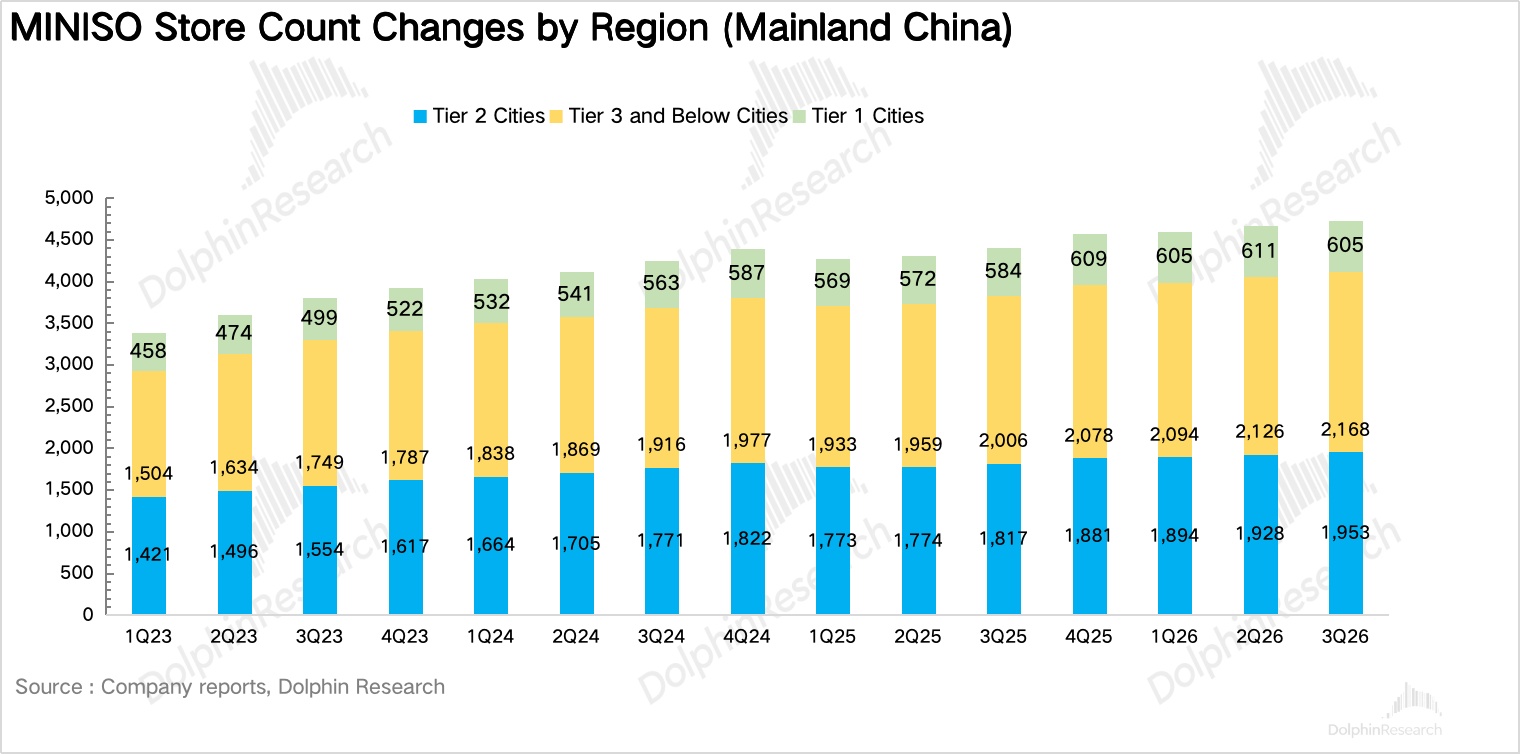
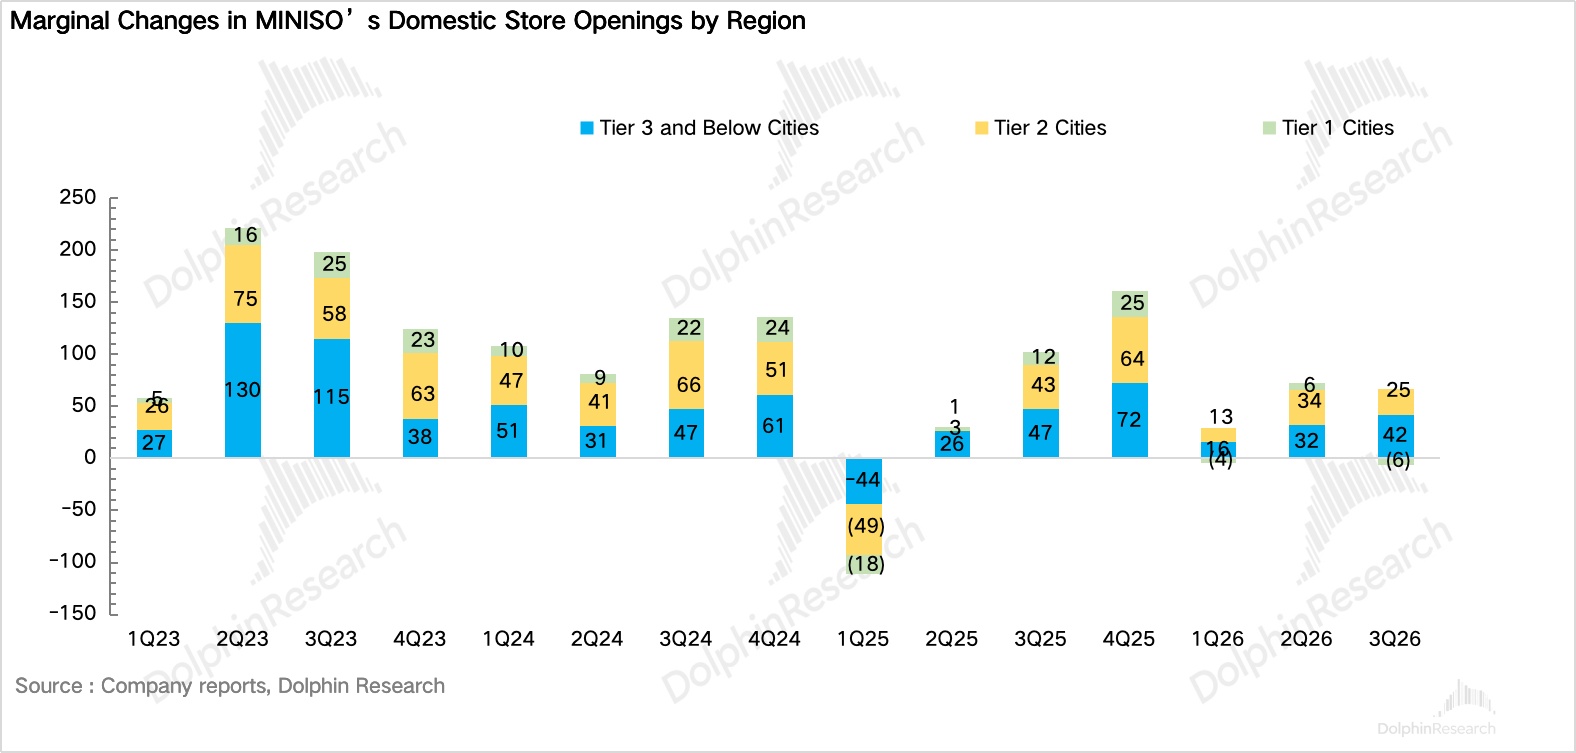
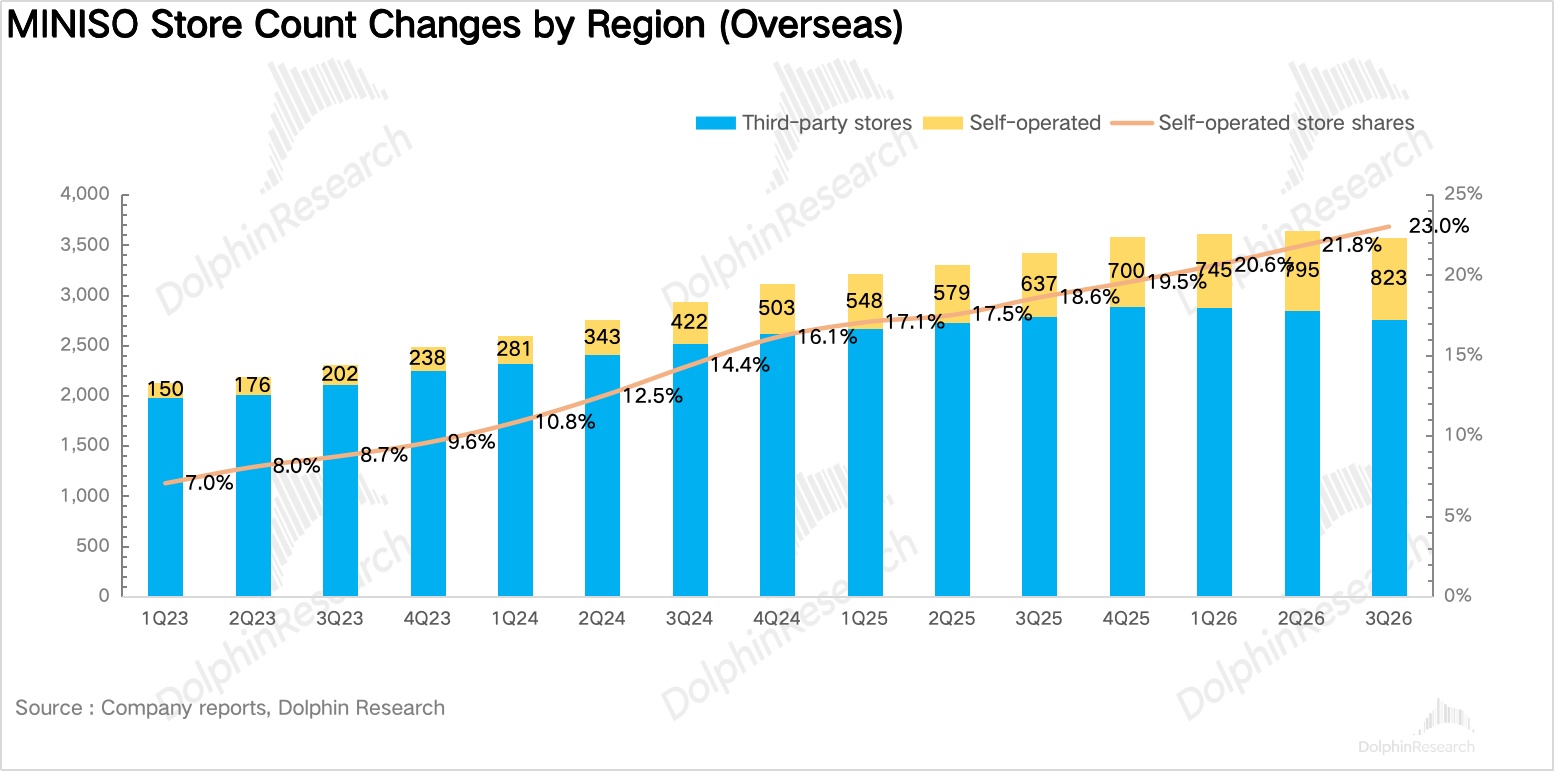
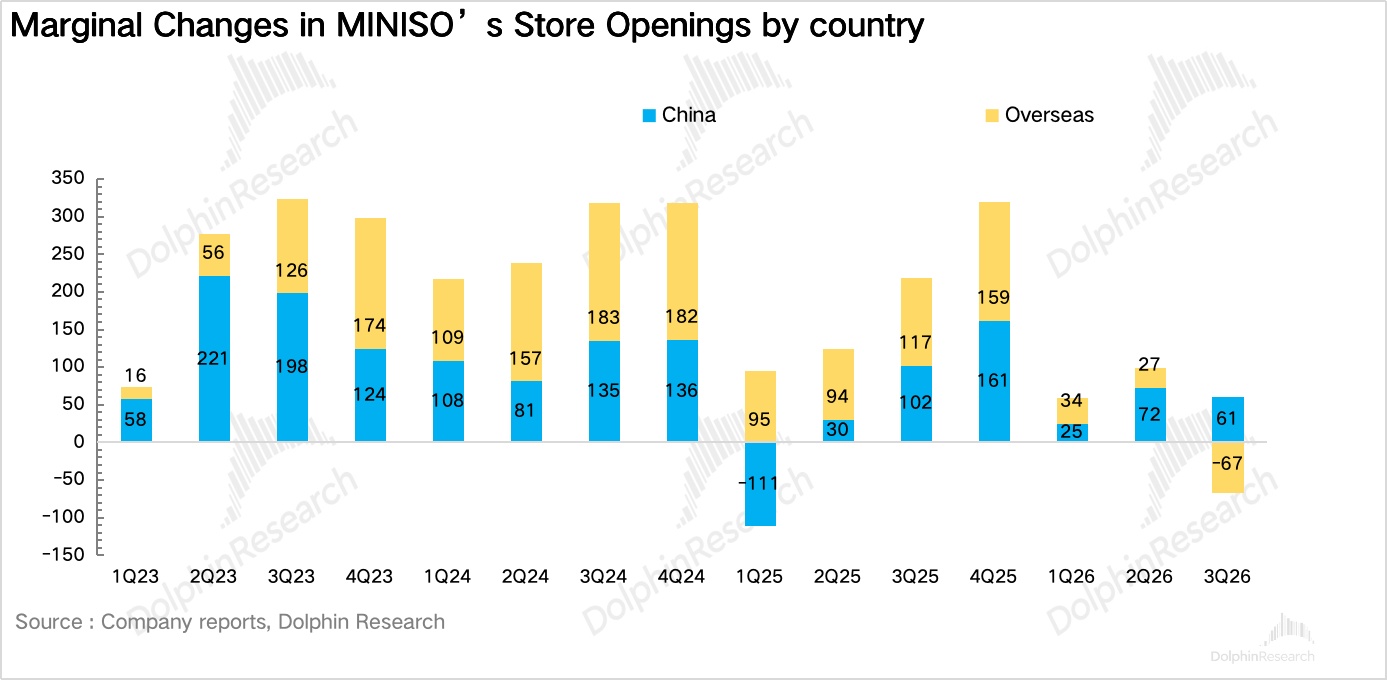
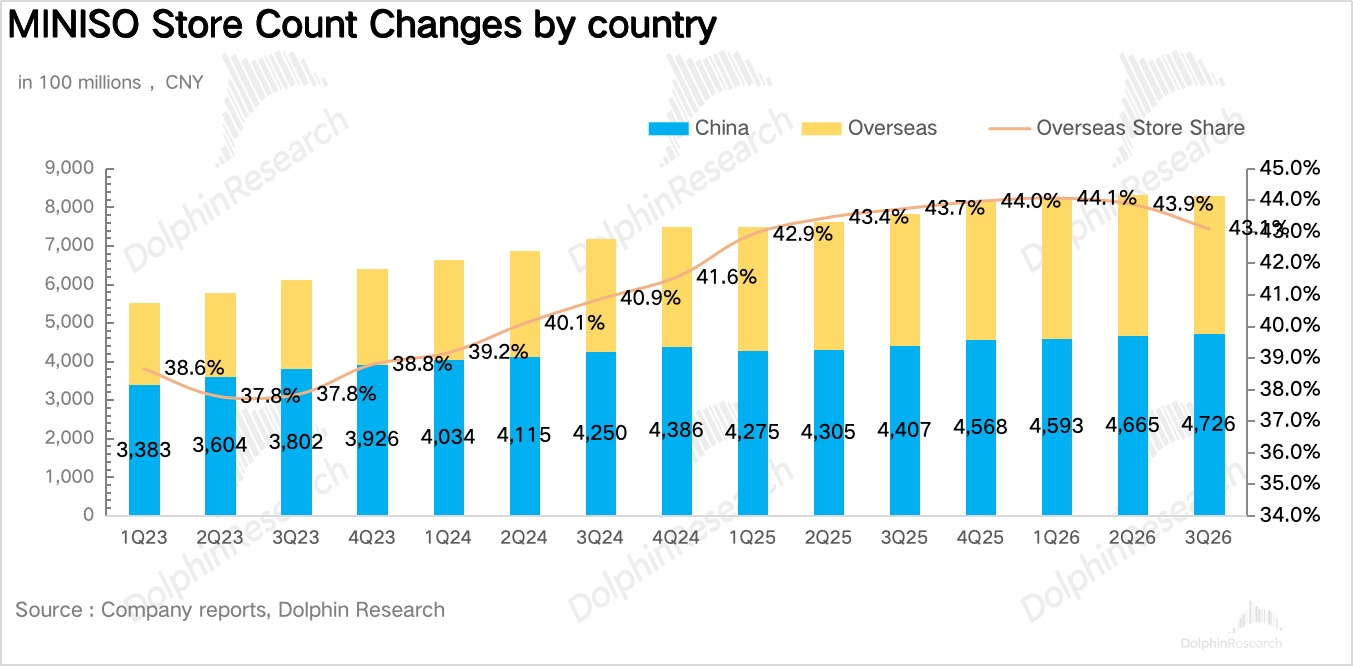
2) Faster store openings in China; mixed overseas. By quarter-end, total stores reached 8,665, roughly flat QoQ. In China, MINISO net added 61 stores, with a faster cadence than 1H, and large-format 'Park' stores now exceed 120. Overseas, net stores fell by 67, driven by distributor closures, with the mix shifting toward self-operated and North America.
TOP TOY stores fell by 3 QoQ to 362, with 11 net closures in China and 8 net additions overseas.
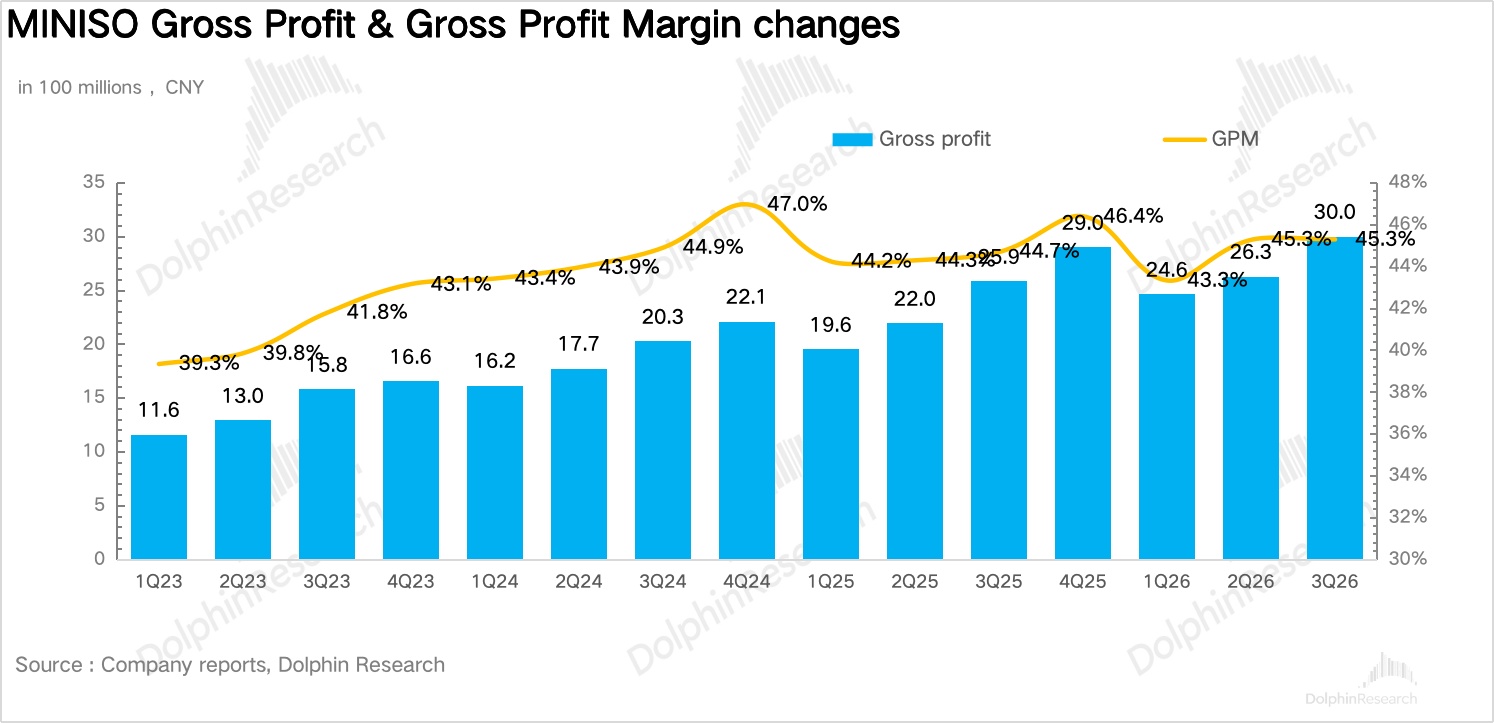
3) GPM improved YoY. Benefiting from pricing optimization and a higher mix of owned IP and designer IP (high single-digit share in 9M), Q3 GPM expanded 60bps YoY to 45.3%, a three-year high.
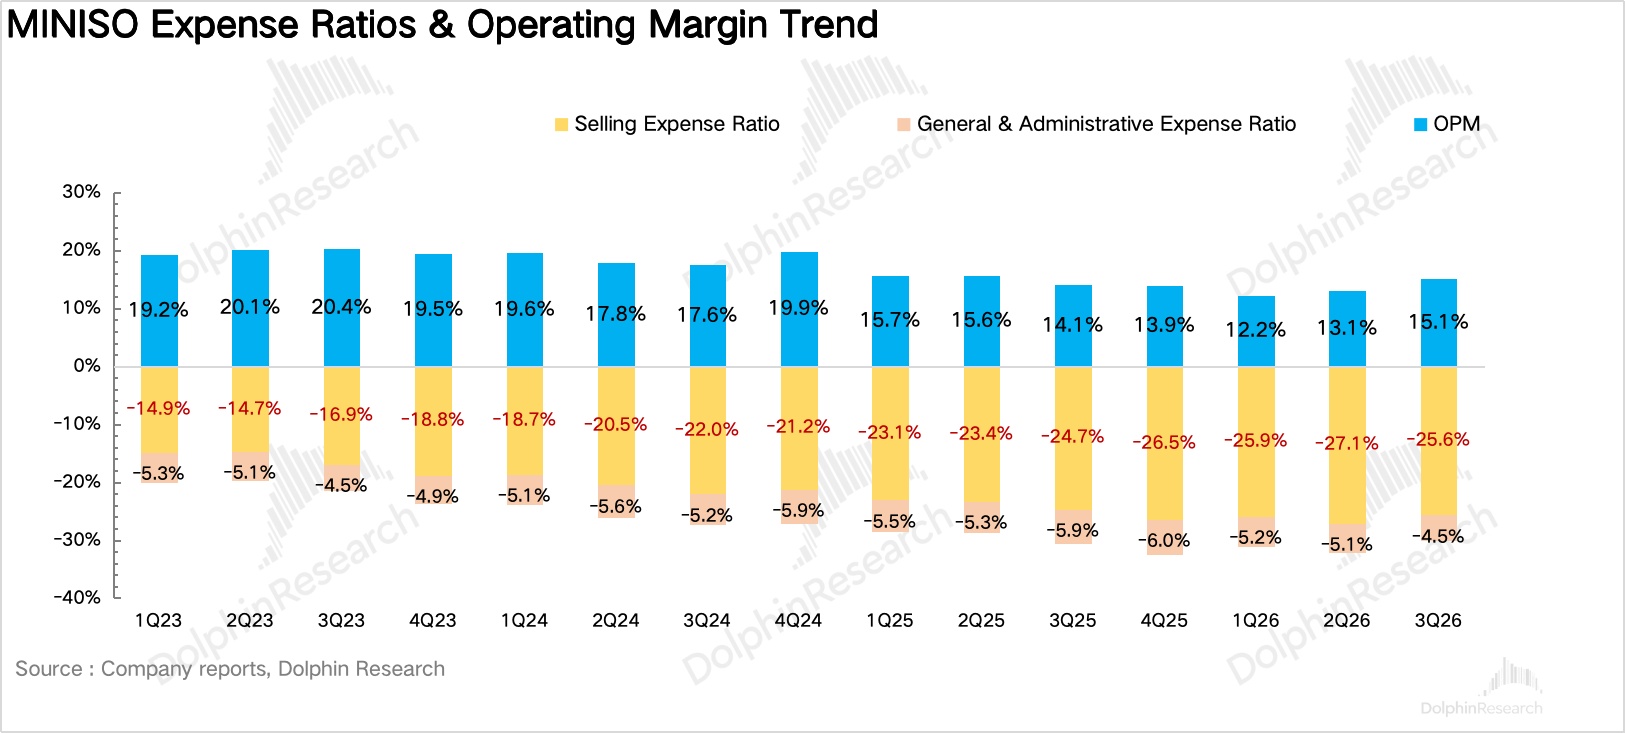
4) Opex ratio kept climbing; core profit still down. On expenses, ex-SBC, selling expenses rose 28.8% YoY, outpacing revenue, lifting the selling ratio by 290bps YoY to 25.9%. Key drivers were D&A and rent at overseas self-operated stores, higher overseas headcount costs, and more marketing. The G&A ratio (ex-SBC) was flat. As a result, adj. OP (ex-FX) was RMB 1.0bn, down 2.5% YoY, and adj. OPM fell 260bps YoY to 15.1%.
Under GAAP, due to fair value losses on AI-related LP investments and losses on exchangeable note derivatives, attributable net profit fell 35.7% YoY to RMB 280mn.
5) Detailed financials:
Dolphin Research view:
First, China was the quarter's positive surprise, showing MINISO is far from entering a 'rent-collecting' steady state domestically. The market had assumed the 4,000+ China-store footprint was mature, with growth hinging more on overseas. Recent quarters show large-format stores (over 120 'Park' stores) and IP-themed stores lifting store productivity, while scaling owned IP (e.g., YOYO) is pulling China back into a high-growth lane.
More importantly, the rising mix of owned and designer IP also pushed GPM to a record high. Dolphin Research has long argued that MINISO resembles an 'Android-like' open IP ecosystem: mass licensed IP attracts traffic but licensing fees cap margins, whereas scaling owned IP is the key to breaking this ceiling. This is the most encouraging marginal shift this quarter.
The concern is that overseas issues have spread from profit to revenue. The premium multiple had been pinned on overseas expansion, especially North America. In 1H, overseas issues were mainly profit-driven: revenue grew, but the shift to self-operated brought upfront costs that compressed margins. In Q3, overseas revenue growth slowed to 1.7%, and store count declined net. We think this reflects an intentional model switch overseas—from 'distributor-led rapid rollout' to 'self-operated with refined ops'.
Under distribution, MINISO earns wholesale margins—asset-light but with weaker control. Under self-operation, it captures full retail margins but bears rent, staffing, and inventory costs. The transition cost is clear: distributor destocking and closures weigh on revenue, while upfront investment in self-operated stores compresses margins—squeezing both revenue and profit.
For now, the North America self-operated model looks proven, with still-healthy growth. But adjustments in SE Asia and LatAm distributor markets are ongoing; the timing of overseas growth recovery and profit contribution from self-operated stores still needs evidence.
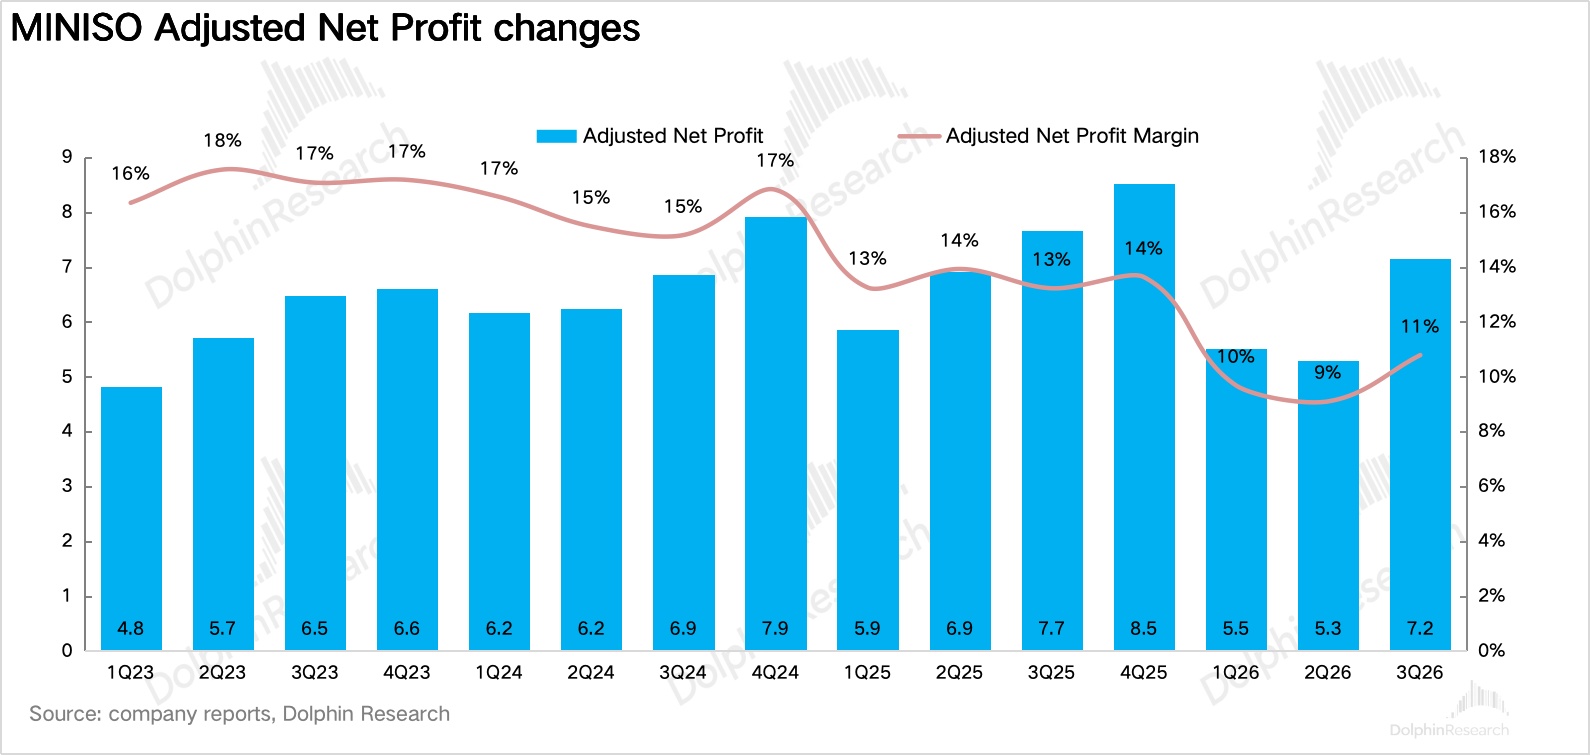
On profit, while adj. net profit fell 3.5% YoY this quarter, the decline narrowed vs. Q2, mainly thanks to strong China scale and higher GPM. With continued investment in overseas self-operation and IP licensing, the selling ratio has yet to improve.
We previously flagged two signals for a profit inflection: 1) selling ratio peaking, and 2) owned IP and overseas self-operation translating into higher-quality profit. In Q3, the second signal started to emerge (owned IP lifting GPM), but the first has not appeared. Also, based on the company's guidance for high single-digit 2H revenue growth, Q4 revenue growth may slip to low single digits, keeping pressure on profit.
Valuation. Adj. net profit was RMB 1.8bn in 9M. On a neutral case, we model Q4 adj. net profit down ~10% YoY to ~RMB 750mn, implying FY2026 adj. net profit of ~RMB 2.5bn and a current multiple of ~9x; assuming ~10% profit growth in 2027 (roughly in line with revenue), the multiple is ~8x.
Overall, we think the current multiple already prices in overseas slowdown and margin pressure, limiting downside; but without a peak in the selling ratio and clear overseas turnaround, a major re-rating is unlikely.
Thus, if China sustains high growth and we see overseas revenue stabilize with the selling ratio no longer rising YoY, the multiple could repair to 10–12x, implying ~10%–30% upside, subject to individual risk appetite.
Detailed charts below:
<End>
Related:
Commentary:
May 26, 2026 earnings review: MINISO: AI investments turbocharged, but growth still paid for
Apr. 1, 2026 earnings review: MINISO: Large stores lift revenue, overseas profit improves—tailwinds for IP retail?
Nov. 21, 2025 earnings review: MINISO: A revenue mint, a cash shredder
Aug. 21, 2025 earnings review: MINISO: Big-box rescue—IP retail rebounds?
May 23, 2025 earnings review: MINISO plunge? Without an IP soul, hard to clone the next Pop Mart
Mar. 21, 2025 earnings review: MINISO: Profitability steps up again—Is IP retail a money printer?
Deep dives
MINISO: From '10-yuan store' to the endgame of IP retail hits?
MINISO: Has Shein cracked? Offline Shein for daily goods looks resilient
Risk disclosure and disclaimer: Dolphin Research disclaimer and general disclosure
本文版权归属于原作者/机构。
以上内容仅代表作者个人观点,不代表平台立场。本内容仅供投资参考,不应被视为投资建议。如您对平台提供的内容服务有任何疑问或建议,请联系我们。