

零跑:越卖越多、越赚越少,“以价换量” 走到头了?
 我是 LongbridgeAI,我可以总结文章信息。
Leapmotor (09863.HK) reported Q3 2026 results after the Hong Kong close on Nov 20 Beijing time. Overall, the print missed markedly: revenue came in slightly below, while profit missed by a wide margin. Specifically: $零跑汽车(09863.HK)
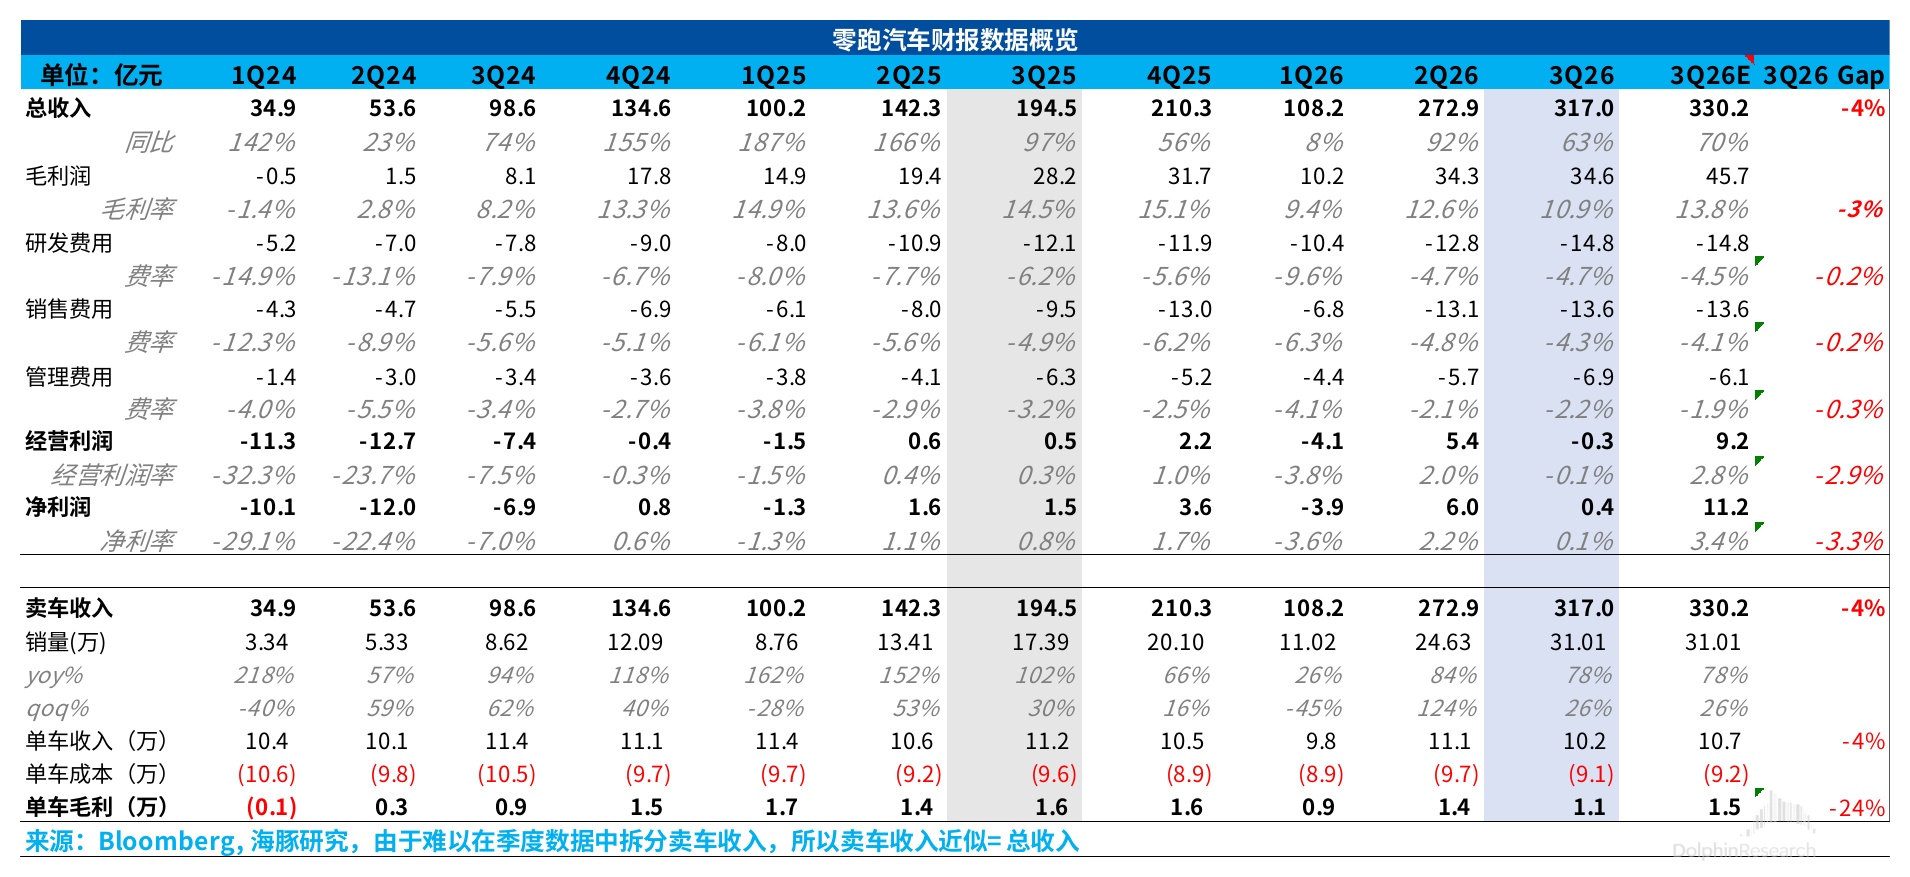
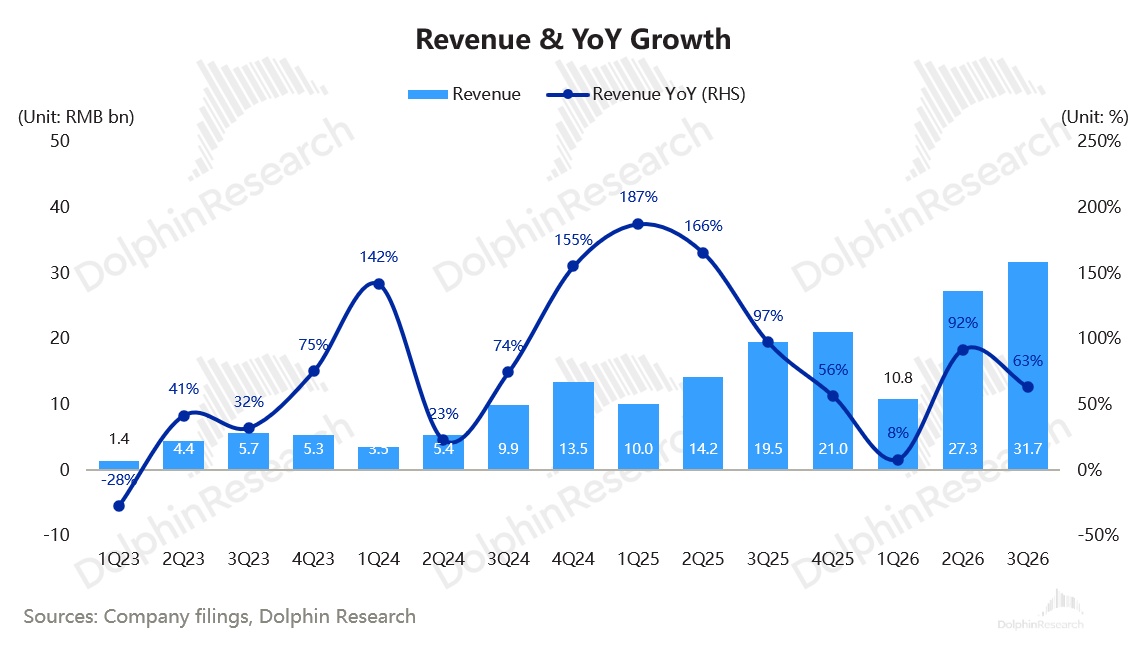
1. Revenue short of estimates; ASP fell QoQ: Q3 revenue was RMB 31.70bn, +63.0% YoY, vs. the street at RMB 32.55bn (≈2.6% light). The shortfall was mainly due to weaker ASPs.
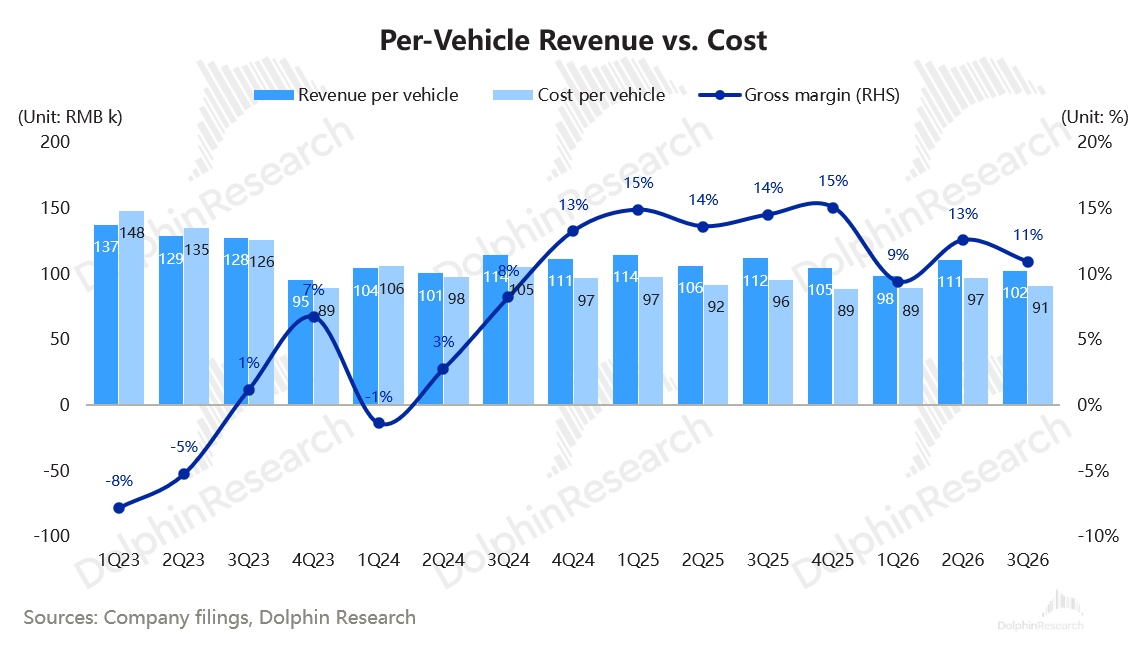
Q3 ASP was approx. RMB 102k per unit (roughly revenue/volume), down about RMB 9k vs. Q2’s RMB 111k and ≈RMB 3k below the street’s ~RMB 105k. Mix shifted down as lower-priced A-series gained share.
Models A10 and A05 continued to scale (cumulative sales since launch exceeded 200k units). The A-series mix rose by about 8.7ppt QoQ to 34.8%, while the higher-priced D-series (D19/D99) was broadly flat QoQ.
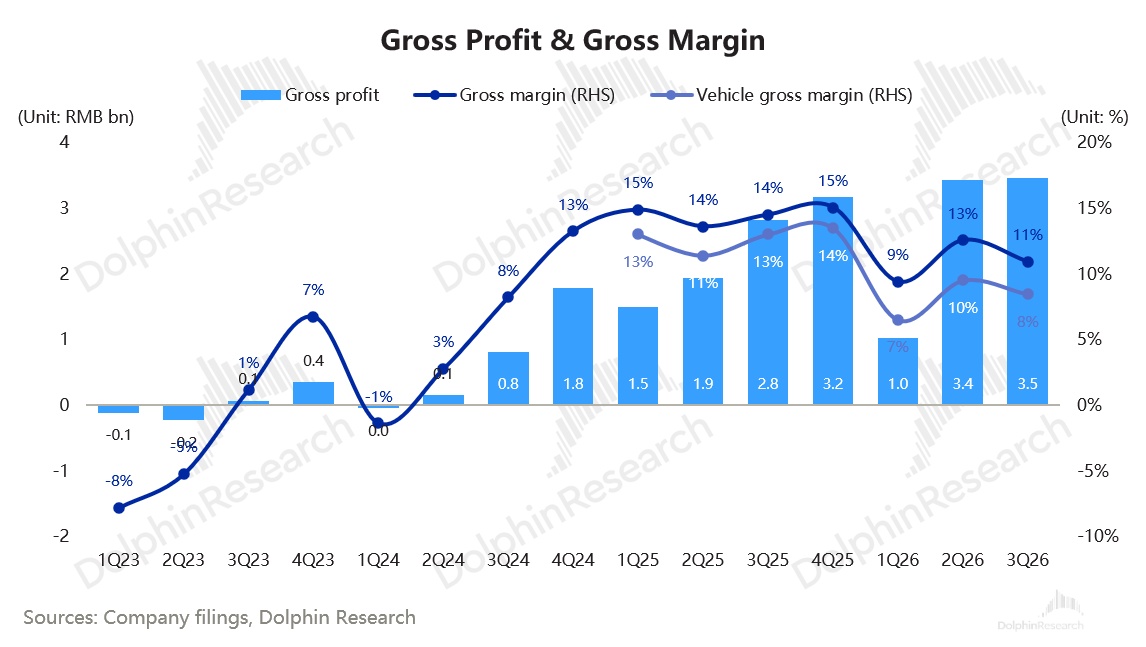
2. GPM declined sharply QoQ, well below expectations: Q3 GPM was 10.9%, down 170bps QoQ and 360bps YoY, vs. the street at 13.8%. Per-unit GP fell to ~RMB 11.2k from RMB 13.9k in Q2, vs. the street at ~RMB 14.5k.
The full-year vehicle GPM guidance is 10–11%, but Q3 blended GPM was only 10.9%. Excluding higher-margin non-vehicle businesses such as carbon credits and components, vehicle GPM likely dipped below 10%.
Management attributed the miss to three factors: mix shift, raw material inflation, and higher ocean freight. Details:
a. Mix skewed to lower-priced models: Rising contribution from entry A-series with lower margins was the primary driver of the QoQ GPM decline. D99 had its first full delivery quarter but was not large enough to offset.
b. Higher raw materials and ocean freight: Price increases in memory chips and batteries were the main reason for the YoY GPM decline. Export volumes rising alongside higher freight rates also weighed on QoQ margins.
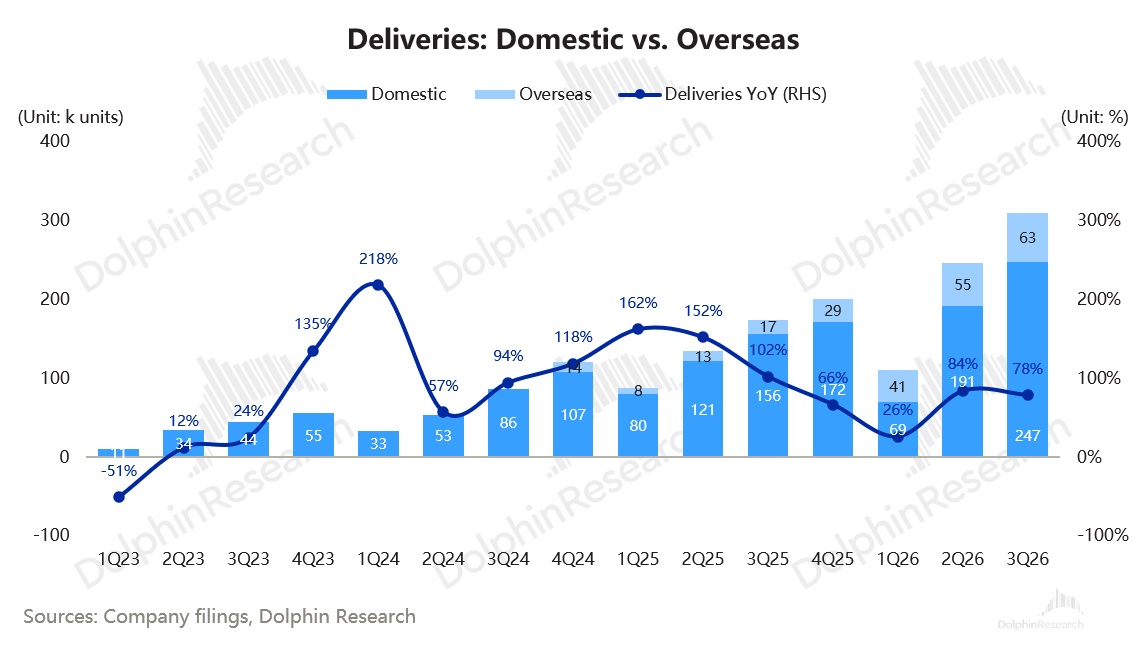
c. Scale benefits offset by price and cost headwinds: Q3 deliveries reached 310k units, +26% QoQ, with monthly sales of 100k+ in Jul–Sep. Yet GP was only RMB 3.46bn, up just RMB 0.03bn vs. Q2’s RMB 3.43bn.
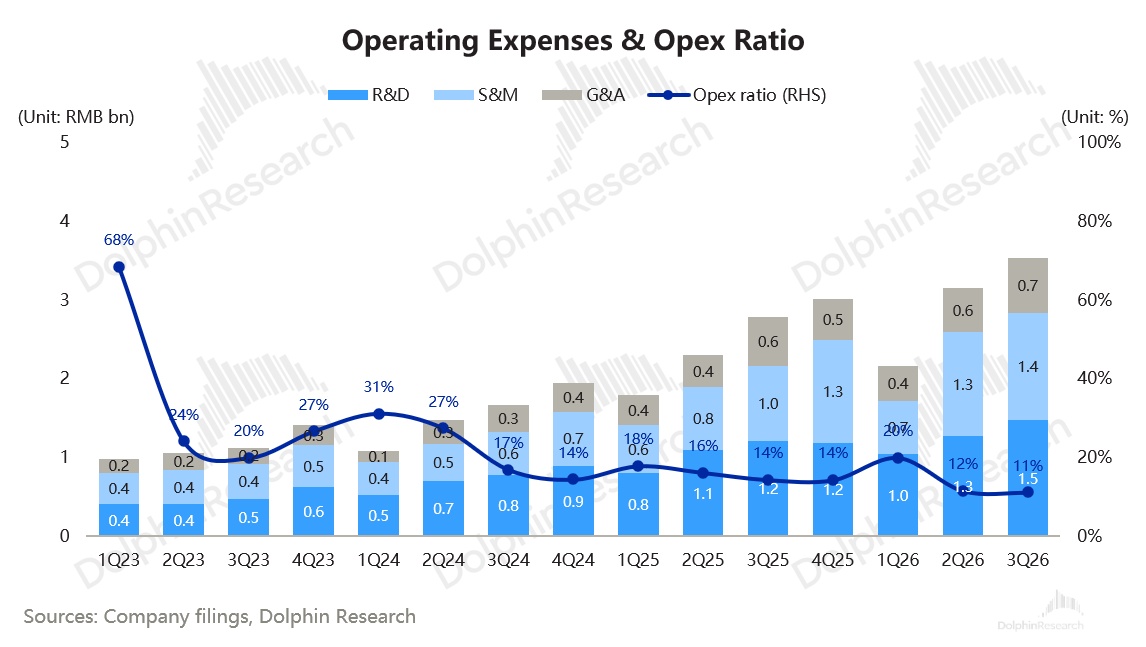
3. Opex rose QoQ; opex ratio edged down: Q3 opex totaled RMB 3.53bn, up RMB 0.38bn QoQ and slightly above the street’s RMB 3.46bn. The opex ratio was 11.1%, down 40bps QoQ but above the street’s ~10.6%. By line item:
a. R&D at RMB 1.48bn, +RMB 0.21bn QoQ, in line with the street: Spend focused on LEAP 5.0 architecture, LWM world model, CTC 3.0 and MM-i multi-mode hybrid e-drive, as unveiled at the Sept Tech Day. Headcount also increased.
b. S&M at RMB 1.36bn, +RMB 0.05bn QoQ: Q3 saw a cluster of launches including A05 and B01/B10 facelifts, plus Tech Day and continued overseas channel build-out. Ad spend and sales headcount rose; the S&M ratio fell 50bps QoQ to 4.3%.
c. G&A at RMB 0.69bn, +RMB 0.12bn QoQ and above the street’s RMB 0.61bn: Driven by higher admin headcount with biz. expansion, and higher taxes and surcharges.
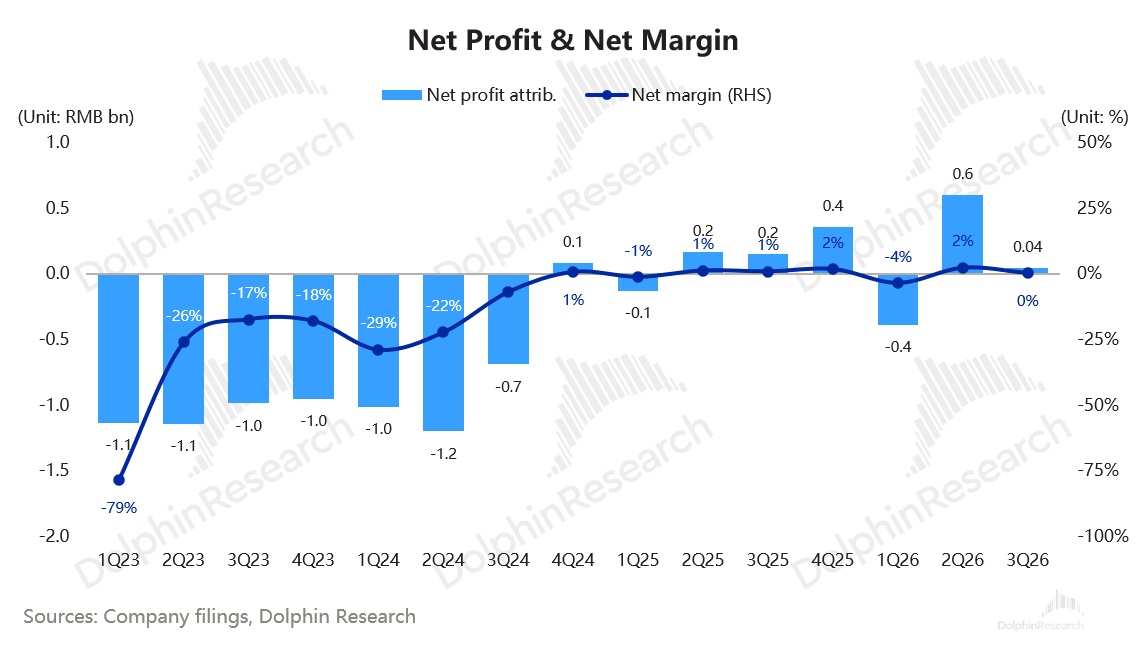
4. OP turned negative; attributable NP nearly zero, well below expectations: Q3 OP was -RMB 30mn (Q2 RMB 540mn; Q3 2025 RMB 50mn), far below the street’s RMB 920mn.
Attributable NP was just RMB 40mn (Q2 RMB 600mn; Q3 2025 RMB 150mn), vs. the street at RMB 1.12bn. Per-unit NP fell from ~RMB 2,430 in Q2 to ~RMB 130, driven by sharply lower GPM, higher opex QoQ, and a ~RMB 220mn QoQ decline in other income.
Dolphin Research View
Overall, Leapmotor’s quarter was a clear miss. ASP dropped to RMB 102k and GPM fell to 10.9%, nearly 300bps below the street; with opex rising and other income down, OP turned negative and attributable NP was only RMB 40mn, almost zero.
The core issue: a 100k/month run-rate failed to translate into profit. Earnings were eroded by the surge in low-priced models and higher raw materials and ocean freight.
The earnings downgrade the market feared materialized in Q3. BYD Seagull 2nd-gen price cuts, extra cash subsidies in Oct, the export VAT rebate cut, and higher memory costs will likely cap ASP and GPM in Q4 and 2027.
Whether FY guidance will be cut, and by how much, awaits management’s confirmation on tonight’s call. Based on Dolphin Research’s estimates, progress vs. guidance looks as follows:
a. Full-year sales ~1.0mn units: Likely broadly achieved. Deliveries were ~667k in 9M26 and ~773k in Jan–Oct; Nov–Dec would need ~114k/month, about 7% above Oct’s 106k.
Dolphin Research estimates Q4 deliveries of ~320–340k and FY26 of ~0.99–1.01mn units. But the A-series should remain the volume driver, while D-series premiumization underwhelms, so Q4 ASP and GPM likely stay under pressure.
b. Full-year NP of ~RMB 3.0bn: Unachievable and likely to be cut. 9M attributable NP totals only ~RMB 250mn, implying ~RMB 2.75bn needed in Q4, nearly the full prior target.
Assuming ~330k Q4 deliveries, ASP ~RMB 105k, and GPM 11–12%, Dolphin Research sees Q4 attributable NP of ~RMB 400–500mn and FY26 of ~RMB 650–750mn, roughly one-quarter of the original guide. The 13–14% full-year GPM guide is also out of reach: 9M blended GPM is ~11.3%, implying FY ~11.2–11.6%; the 10–11% vehicle GPM guide was likely breached in Q3.
c. Overseas: The ~200k export target looks achievable. Jan–Oct exports already exceeded 180k; Nov–Dec need only ~10k/month, and with Q3 at ~21k/month, full-year could reach ~220k.
Whether the 2027 overseas target of 350–400k units holds remains to be seen, but localization is progressing and should partially offset the export VAT rebate cut (13%→9%). The Zaragoza, Spain plant started B10 production on Oct 16; B05 is slated for pilot runs this year and SOP in 2027. The Goiânia, Brazil plant aims to mass-produce B10 and C10 in 2H27. Profit contribution from overseas depends on when the JV starts recognizing profits.
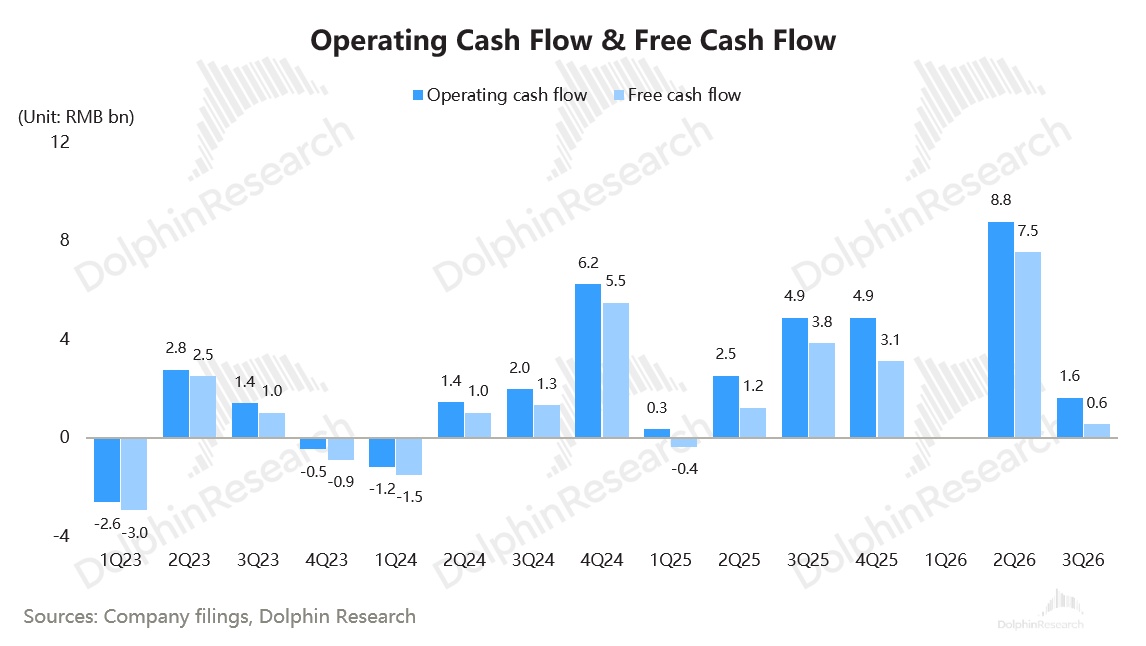
d. Cash flow fell sharply: Q3 operating CF was RMB 1.62bn (Q2 RMB 8.78bn; Q3 2025 RMB 4.88bn), and FCF was RMB 550mn (Q2 RMB 7.54bn). Management cited strategic inventory build increasing procurement outlays and concentrated A/P maturities; cash on hand at quarter-end was RMB 39.14bn.
Assuming FY26 sales of 1.0mn units and revenue of RMB 104.7bn (+62% YoY), the current ~RMB 36.8bn market cap implies ~0.35x FY26 P/S, near the historical trough.
The prior 2027 target was 1.5–1.6mn units (seven new models; a second brand debuting in 4Q27). Dolphin Research conservatively models 1.25mn units (+25% YoY, mostly overseas-driven), implying 2027 revenue of ~RMB 138.6bn (+32% YoY) and a current P/S of ~0.27x.
Dolphin Research believes the multiple sits at a historical low mainly because:
1) Profit guidance cut again: The FY NP target has been reduced from ~RMB 5.0bn to ~RMB 3.0bn this year, yet 9M delivered only ~RMB 250mn, and Q3 GPM fell to 10.9%. The RMB 3.0bn target is largely out of reach; Dolphin Research expects FY NP at ~RMB 650–750mn, about a quarter of the original guide.
If raw material and freight pressures persist and earnings fail to improve, the market will not award a high multiple.
2) Declining revenue quality: Incremental volume is concentrated in RMB 50–60k A-series models, while D-series premiumization has underperformed. ASP fell from RMB 111k in Q2 to RMB 102k, with GPM down from 12.6% to 10.9%.
If low-priced A-series keeps driving volume without profit, revenue multiples deserve a discount.
3) Overseas, a key pillar, faces cost and policy headwinds: Higher ocean freight already dragged Q3 margins; the export VAT rebate will be cut from 13% to 9% from Apr 2027, and the EU may impose import quotas on PHEVs.
Exports are sold via the JV with Stellantis, with Leapmotor’s own margin only in the low single digits, and profit recognition at the JV will take time. Within the 2027 350–400k overseas target, only ~50k units are planned for local production in Spain, so most will still be exported from China, making policy shocks hard to fully offset.
4) Cycle and cost do not support a re-rating: China PV retail is still declining, memory and other components are rising in price, and the auto OEM group trades near historical lows. It is hard for Leapmotor to decouple and re-rate on its own.
Therefore, with profit targets missed and a downtrend in GPM not yet reversed, near-term upside looks limited.
A durable turn likely requires easing in memory and commodities, plus cost-down from in-house cells to put GPM back on an uptrend, alongside overseas outperformance. Tech licensing and component supply (FAW Hongqi cooperation, FAW’s private placement subscription, STLA platform partnership) also offer upside optionality to the multiple.
Related charts:
<End here>
Risk disclosure and disclaimer:Dolphin Research disclaimer and general disclosure
Dolphin Research’s prior pieces on Leapmotor for reference:
Aug 25, 2026 earnings call Trans: 'Leapmotor (2Q26 Transcript)'
Aug 25, 2026 earnings take: 'Leapmotor: Profit Guidance Slashed—Is Going Overseas the Only Way Out?'
Mar 16, 2026 earnings call Trans: 'Leapmotor (4Q25 Transcript): 2026 Sales Target Held at 1 Million Units'
Mar 16, 2026 earnings take: 'Leapmotor: An Export Hit—Can It Really 'Lead' New EV Makers to a Million?'
Nov 19, 2025 earnings call Trans: 'Leapmotor (3Q25 Transcript): 2026 Targets of 1 Million Units in Sales and RMB 5bn in Net Profit'
Nov 18, 2025 earnings take: 'Leapmotor: 'Leap' Momentum Stalls—How to Fight Its Way Out?'
Aug 19, 2025 earnings call Trans: 'Leapmotor: Full-Year Sales Target Raised to 580k–650k Units'
Aug 18, 2025 earnings take: 'Leapmotor Fights Its Way Through a Cutthroat Red Ocean!'
May 20, 2025 earnings call Trans: 'Leapmotor (1Q25 Transcript): How Can the EV 'Price-War King' Pull Off a Comeback?'
May 20, 2025 earnings take: 'Leapmotor: Winning on Hard Work—A Real Gem in the EV Melee!'
Mar 11, 2025 earnings call Trans: 'Leapmotor (Transcript): 2025 Sales Target of 500k–600k Units'
Mar 10, 2025 earnings take: 'Leapmotor: Dark Horse Comeback—Is the 'Mini Li Auto' on a Tear?'
Aug 16, 2024 earnings call Trans: '2024 Sales Target of 250k Units and Full-Year GPM Target of 5% Maintained'
Aug 15, 2024 earnings take: 'Leapmotor: Revenue and Gross Profit Both Miss—Can Exports Turn the Tide?'
May 17, 2024 earnings take: 'GPM Turns Negative—Can Leapmotor Carve Out a Path Overseas?'
Mar 26, 2024 earnings call Trans: 'Full-Year GPM Kept at 5%–10%'
Mar 25, 2024 earnings take: 'GPM Keeps Rising—Can Leapmotor 'Lead' Overseas?'
Oct 17, 2023 earnings call Trans: 'GPM Outlook Keeps Improving—Is It Time to Invest in Leapmotor? (Leapmotor 3Q Earnings Call Transcript)'
Oct 16, 2023 earnings take: 'GPM Turns Positive—Is Leapmotor Finally Crossing the Survival Line?'
Aug 25, 2023 earnings take: 'Leapmotor: GPM Still Negative—When Will the 'Xiaomi of Cars' Take the Lead?'
Sep 29, 2022 deep dive: 'Leapmotor: Down 30% Since IPO—Is the 'Redmi Version of XPeng' a Trap or a Real Opportunity?'
本文版权归属于原作者/机构。
以上内容仅代表作者个人观点,不代表平台立场。本内容仅供投资参考,不应被视为投资建议。如您对平台提供的内容服务有任何疑问或建议,请联系我们。