

SK hynix: How Long Can the AI-led Memory Supercycle Last?
 I'm LongbridgeAI, I can summarize articles.
In the last two pieces, Dolphin Research outlined the technical logic and roadmap behind the 'memory power' trade. This note shifts back to the company lens, focusing on the flagship of this cycle’s HBM rally — $SK Hynix(SKHY.US).
SK hynix sits in a delicate spot: DRAM pricing is surging and HBM stays tight, lifting earnings, with the stock up ~10x within half a year at one point. Yet Samsung and Micron are rapidly qualifying into Nvidia and other core customers’ supply chains, moving hynix’s edge from 'exclusive' to merely 'lead'.
As a manufacturer, results boil down to 'price and volume': price is set by industry supply vs. demand, and volume in tight cycles largely follows installed capacity. Customer mix and LTA coverage define pricing power and visibility. We discuss three questions:
1) Will the supply–demand gaps in DRAM (DDR and HBM) widen or narrow, and what does that imply for price?
2) Which major customers are most tightly tied to hynix, can new LTAs smooth the cycle, and what flexibility vs. risk does hynix’s LTA strategy entail?
3) How much can hynix’s capacity and earnings grow, and is the current valuation reasonable?
Below is the main text:
I. Decisive factor — DRAM industry supply–demand outlook
Even in the AI era, memory tech content has risen but same-generation performance gaps across vendors remain limited, with standardized specs and broadly homogeneous products. As a result, memory makers do not set price; they take price set by supply–demand.
Since sales volume is largely capacity-bound and relatively stable, most revenue and margin elasticity comes from price. Therefore, supply–demand for DRAM is the single most important driver of results and share prices.
1.1 Industry demand: nearly all incremental demand from servers
We split total DRAM demand into three buckets: a) conventional end-products, e.g., PCs, smartphones, automotive, TV; b) DDR used in general-purpose servers; c) DDR+HBM for AI servers.
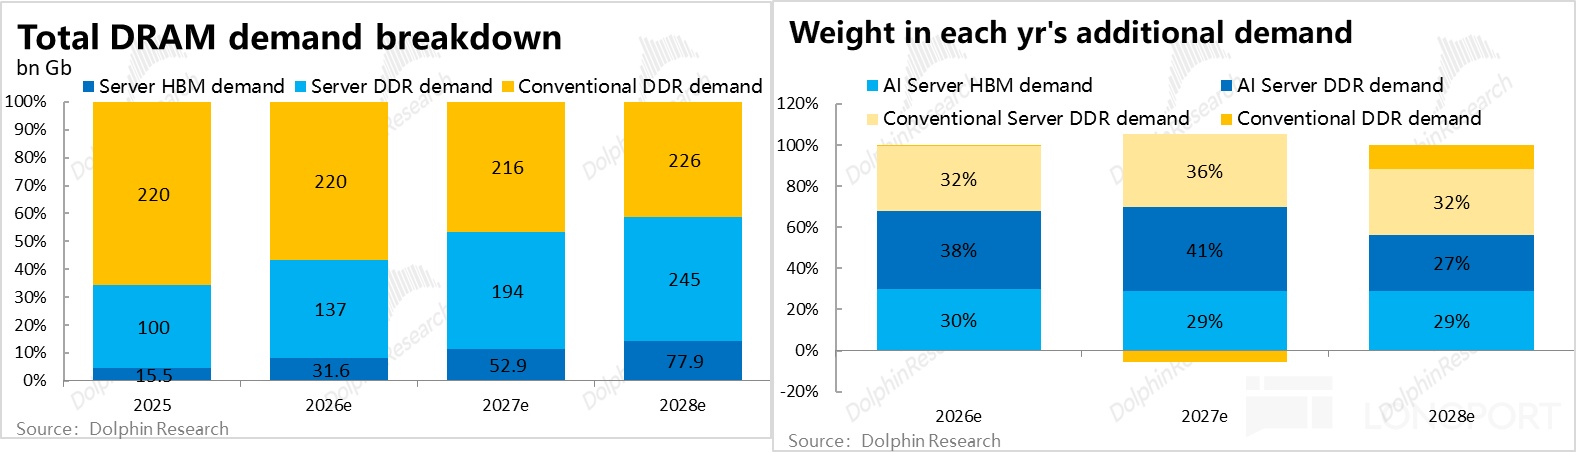
Bottom line: industry DRAM demand (incl. HBM, excl. inventory swings) rises from ~336 bn Gb in 2025 to ~549 bn Gb in 2028, ~18% CAGR. General-purpose servers, AI server DDR and HBM each contribute roughly one-third of the incremental demand, while conventional products contribute ~3%. Server (incl. AI) share of total demand climbs from ~34% to ~59%.
a. Conventional end-demand: price squeeze, but capacity per device is sticky
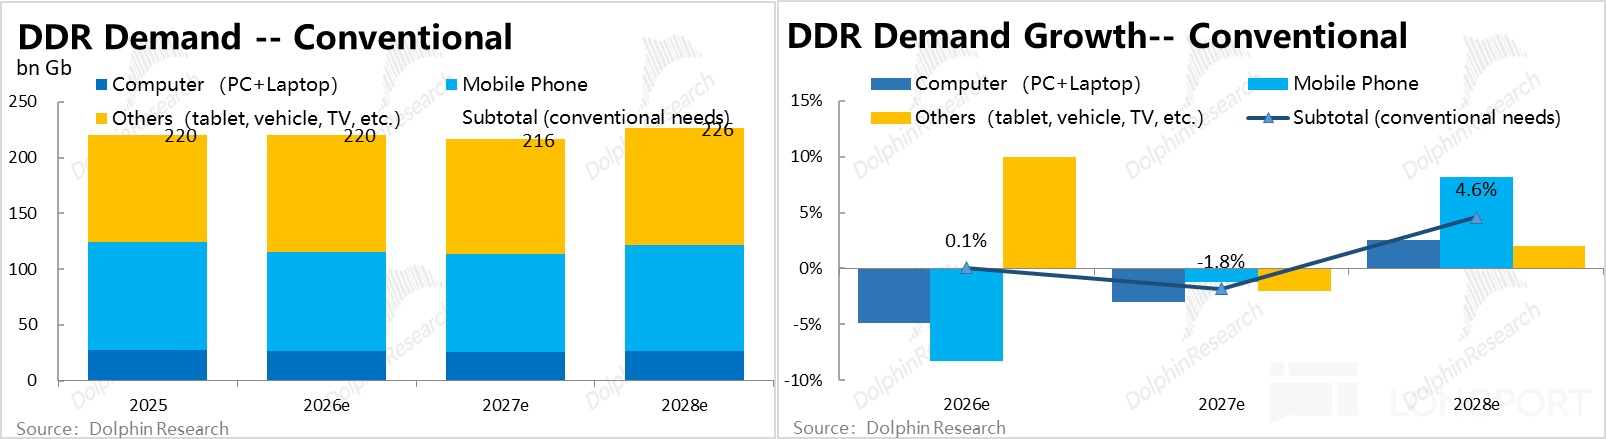
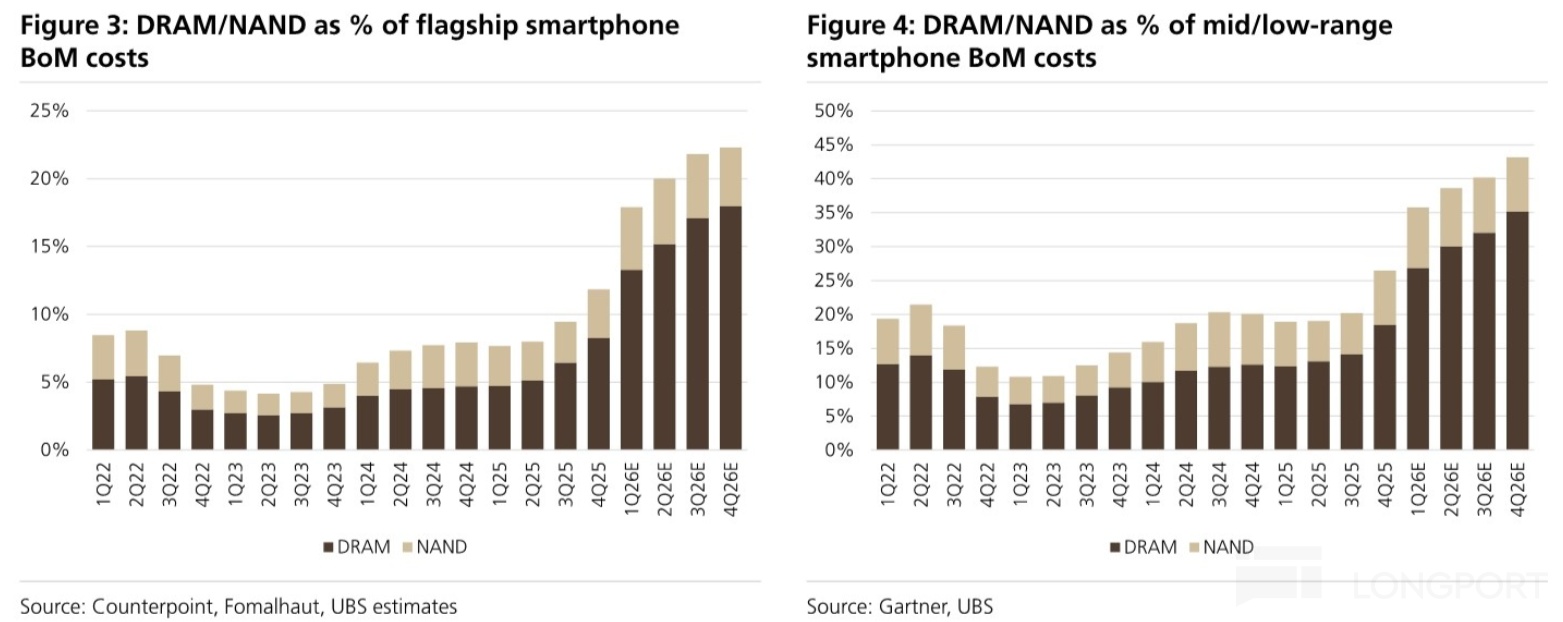
For PCs, phones, tablets, autos, TVs and others, conventional DRAM demand in 2026–28 stays roughly flat (~216–226 bn Gb), with share dropping from ~66% to ~41%. The key driver is higher DRAM prices suppressing shipments (e.g., memory now accounts for a doubled share of smartphone BOM costs).
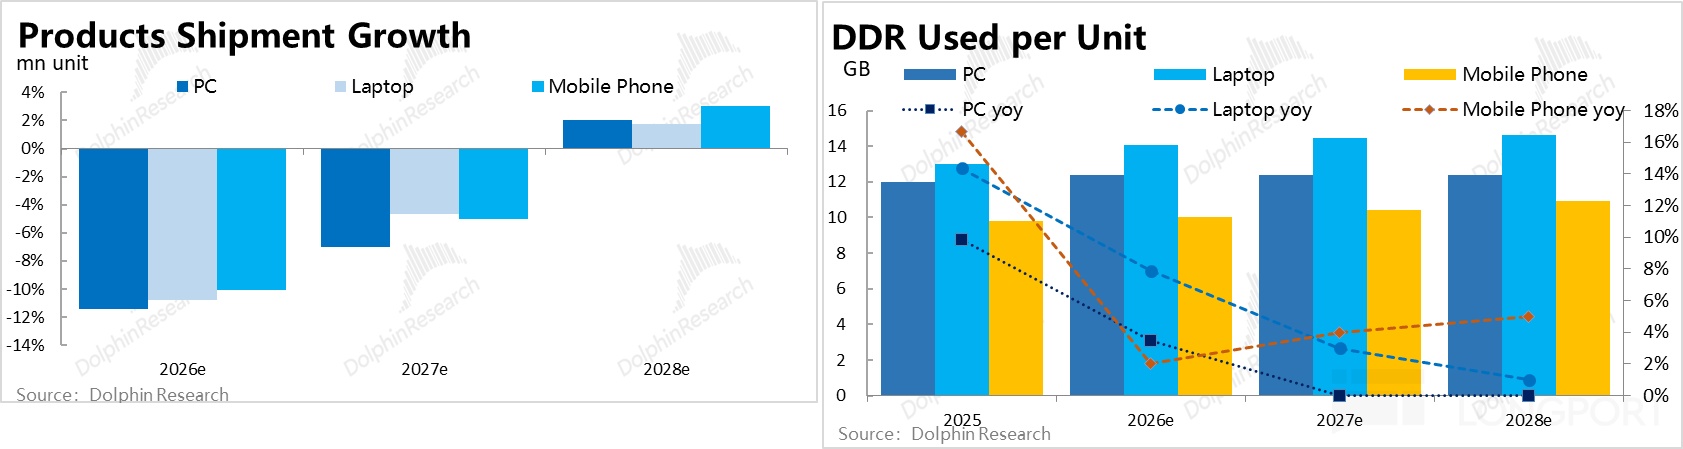
Consensus sees PC and handset shipments down ~10% in 2026, then down another ~5–7% in 2027. We think per-device memory capacity is relatively non-discretionary and unlikely to be cut, to preserve user experience.
Overall, conventional DRAM is the 'buffer' in memory demand: squeezed demand is mostly deferred and will re-emerge as prices ease, providing a floor in a down cycle.
Risks go both ways: sustained price hikes could deepen the squeeze; on the other hand, if on-device AI scales, per-device memory could step up notably, adding demand.
b. General-purpose servers: overlooked incremental driver, doubles in three years
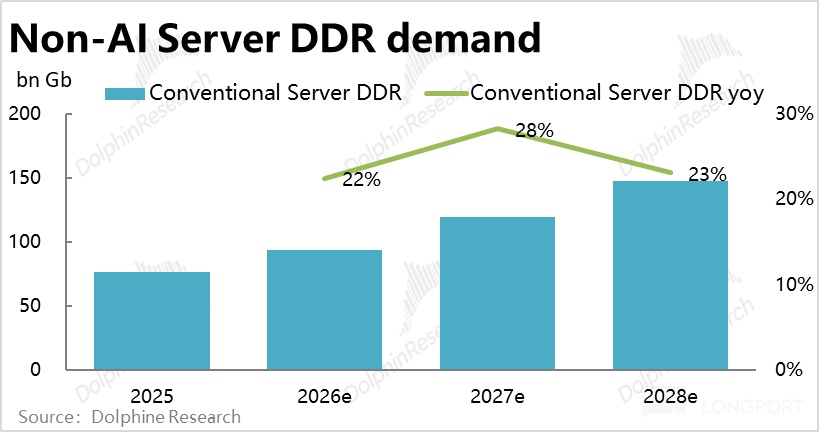
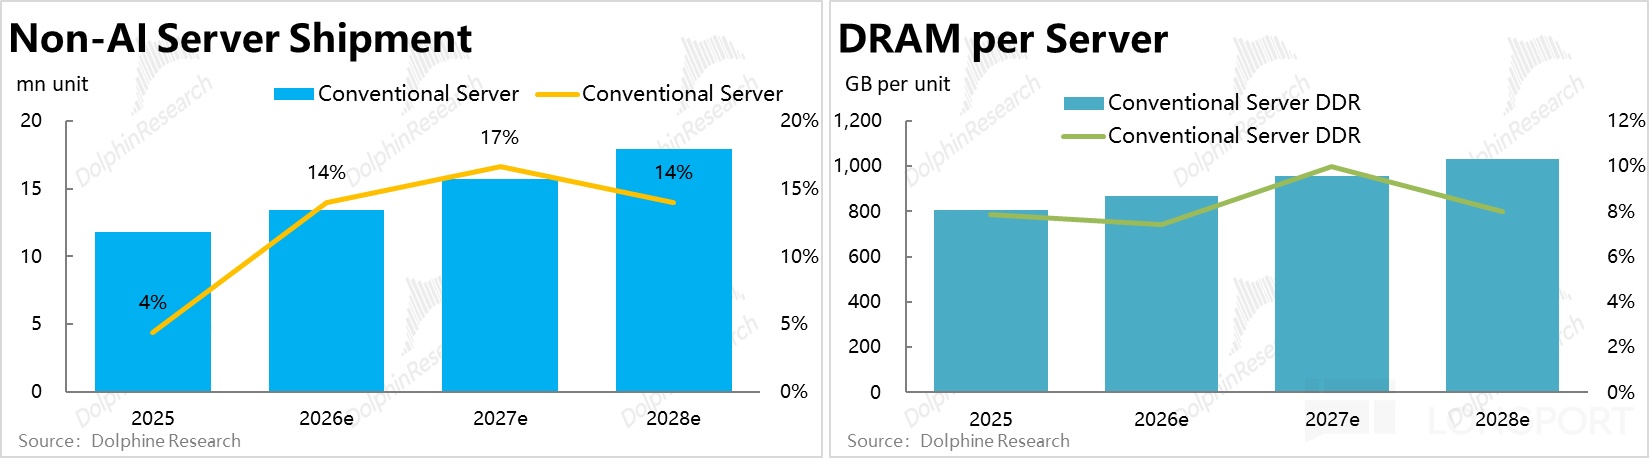
General-purpose servers are CPU-centric and use conventional DDR, and were the main shipment base pre-AI. We estimate their DDR demand rises from ~76 bn Gb to ~148 bn Gb in three years, ~25% CAGR — an often overlooked but material source of incremental demand.
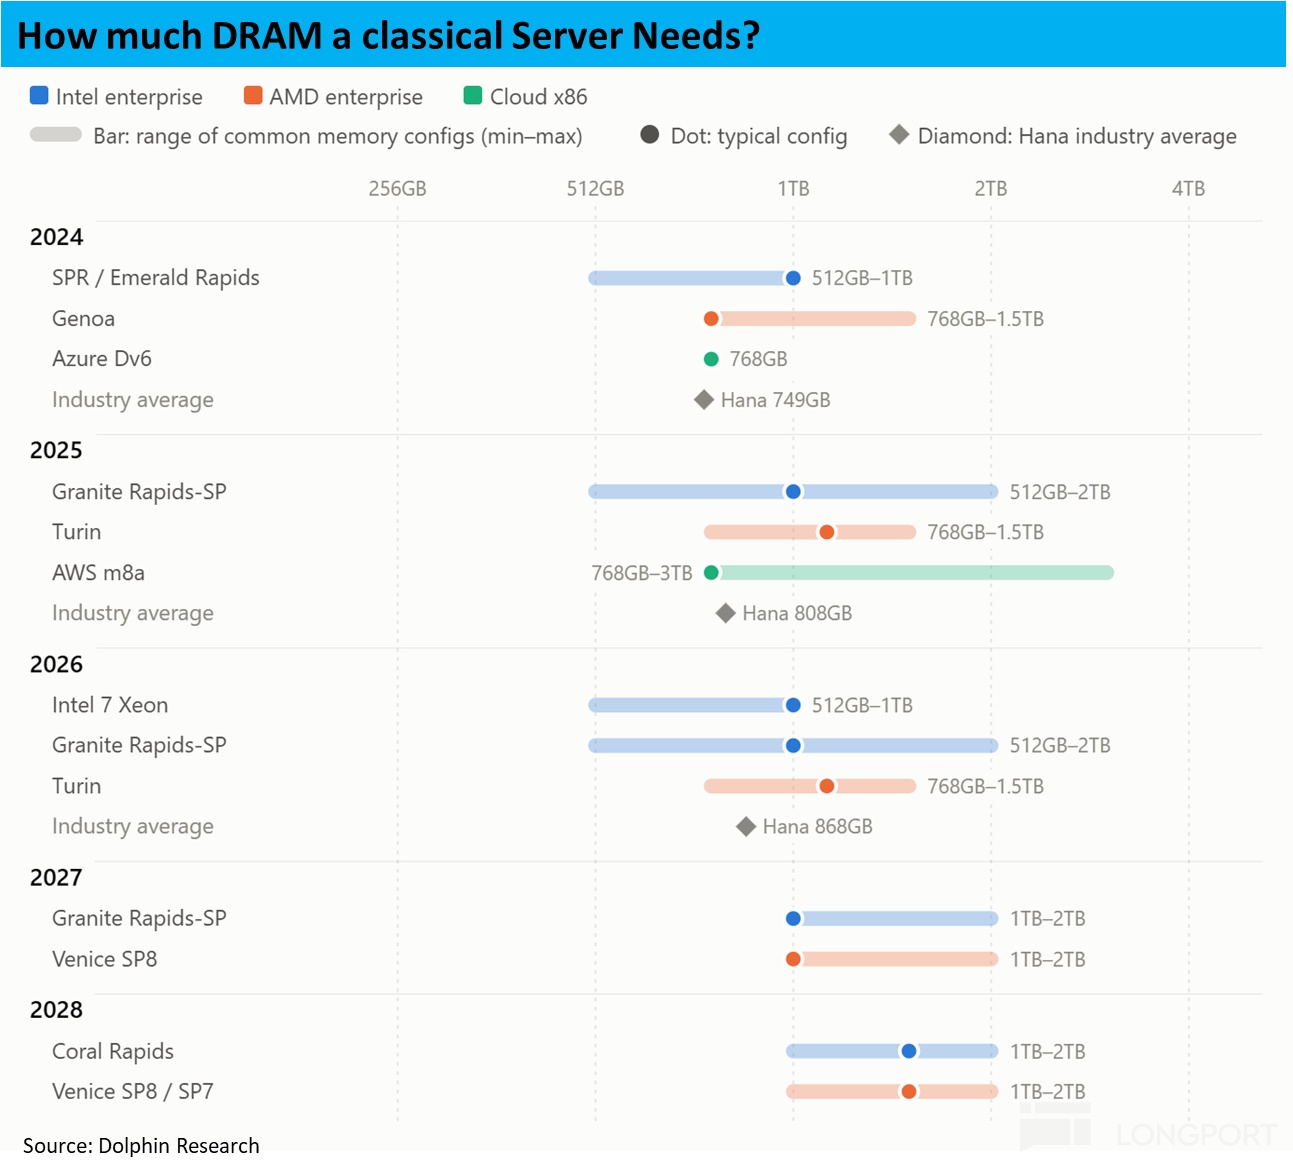
Drivers are price and volume. On volume, servers bought during the pandemic are entering refresh, and Agent-driven general compute needs lift shipments to ~15% growth in 2026–28. On price, industry expects DDR per box to rise ~7–10% p.a. from ~800 GB to >1 TB in 2025–28.
Historical server configs support this: per-box DRAM climbs from several hundred GB in 2024–25 to a 1 TB baseline in 2027–28.
c. AI servers: the biggest swing factor
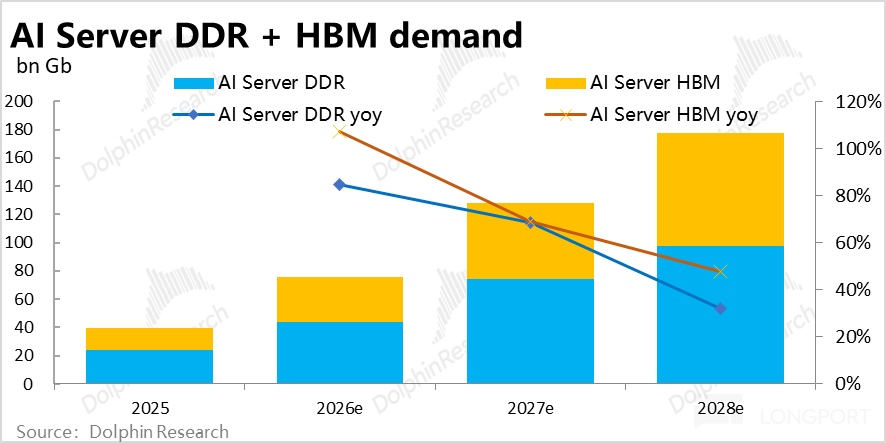
AI servers are the largest incremental driver, with total DRAM (HBM+DDR) rising from ~39 bn Gb in 2025 to ~176 bn Gb in 2028, contributing nearly two-thirds of total demand growth (ex-inventory).
Specifically, HBM rises from ~15.5 bn Gb to ~78 bn Gb, 71% CAGR in 2026–28. AI server DDR increases from ~24 bn Gb to ~98 bn Gb, with incremental increases from DDR and HBM broadly similar in magnitude.
① Shipments: almost triple in three years, ASIC becomes the main driver.
(Note: shipment lens here is XPU units, previously we used system units.)
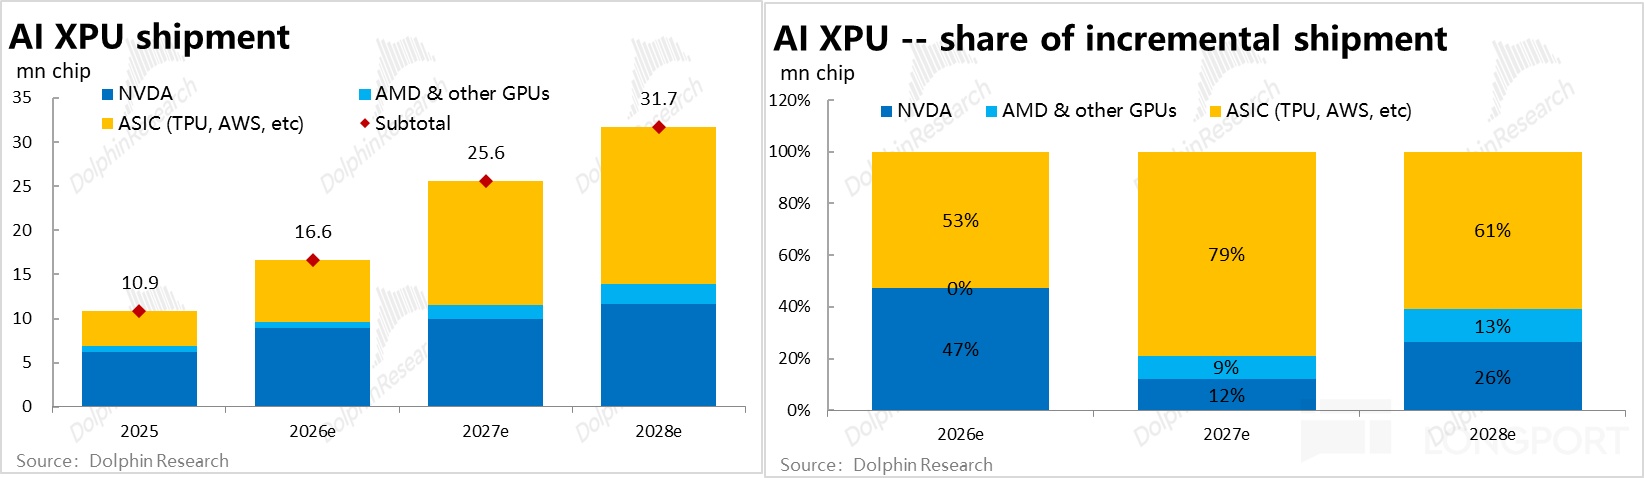
Constrained by TSMC CoWoS, we estimate global AI accelerators rise from ~10.9 mn units in 2025 to ~31.7 mn in 2028, ~43% CAGR. Nvidia grows relatively steadily, while ASIC accelerators rise from ~4.0 mn to ~17.8 mn units, surpassing Nvidia from 2027, becoming the key growth engine.
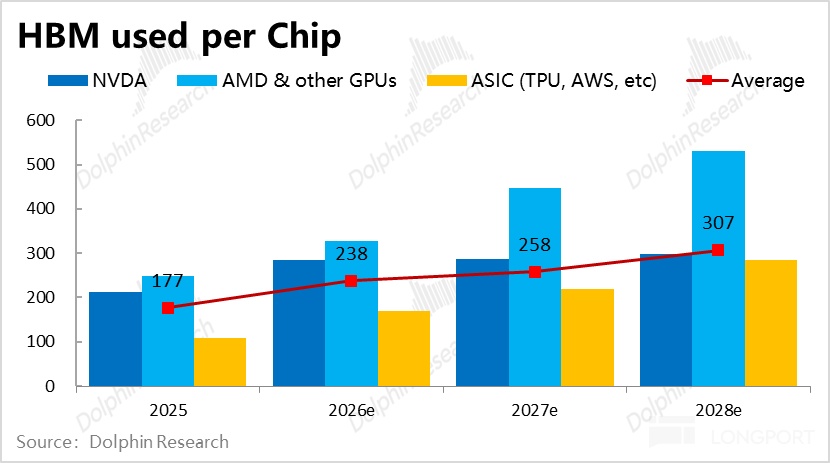
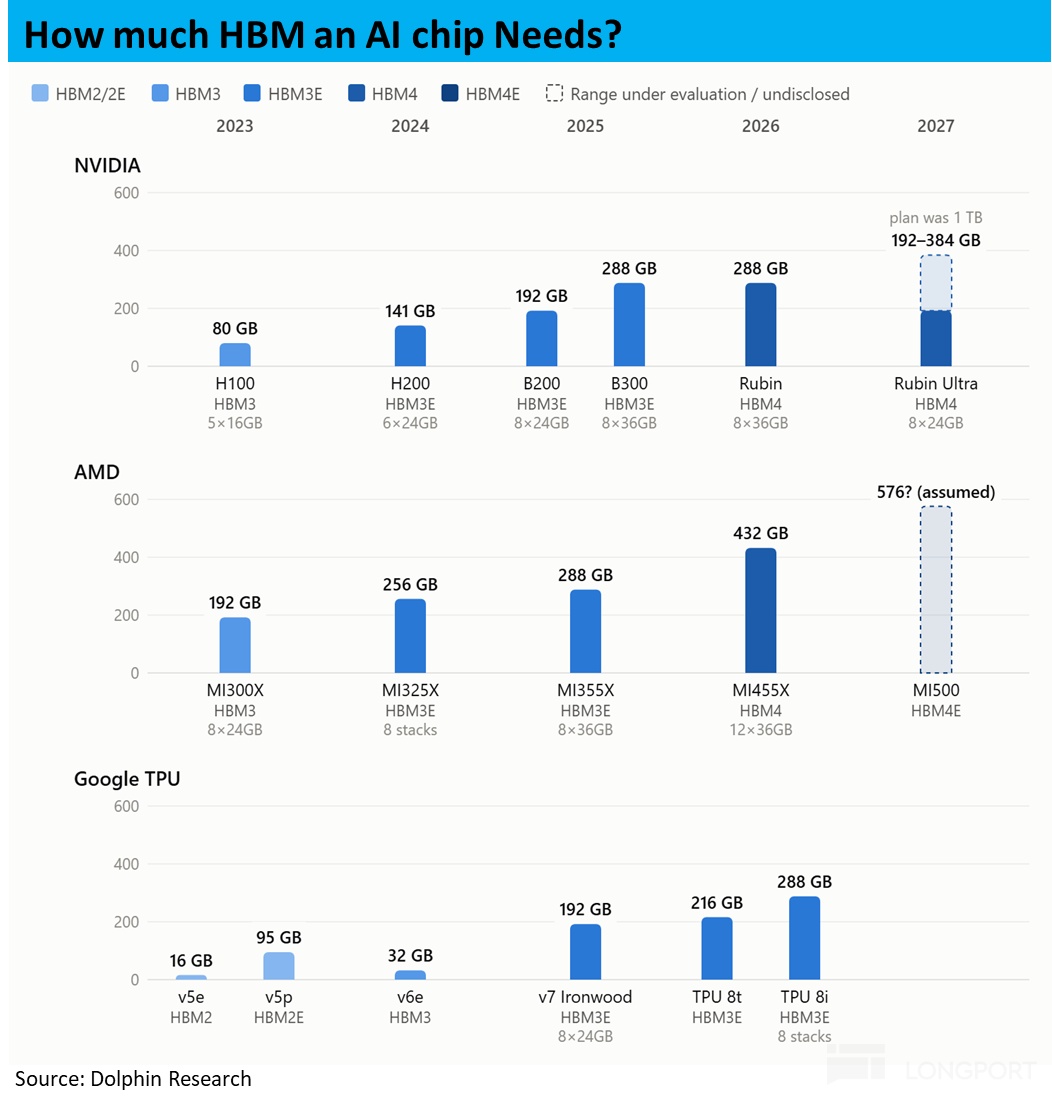
② HBM per XPU: capacity per die is capped, but mix-led lift continues. Adding more stacks raises process complexity and wafer loss, so HBM per die capacity is no longer climbing.
Nvidia’s Rubin keeps per-die capacity similar to GB300, and Rubin Ultra may even step down from 288 GB to 192 GB. However, ASICs historically had lower HBM per die and are trending up toward Nvidia GPUs (from 192 GB to 288 GB), while AMD competes with more HBM per package (MI455X at 432 GB per module). As their shipment shares rise, Avg. HBM per XPU can still grow ~14% p.a. in 2026–28.
③ DDR per XPU: AI servers also consume substantial DDR.
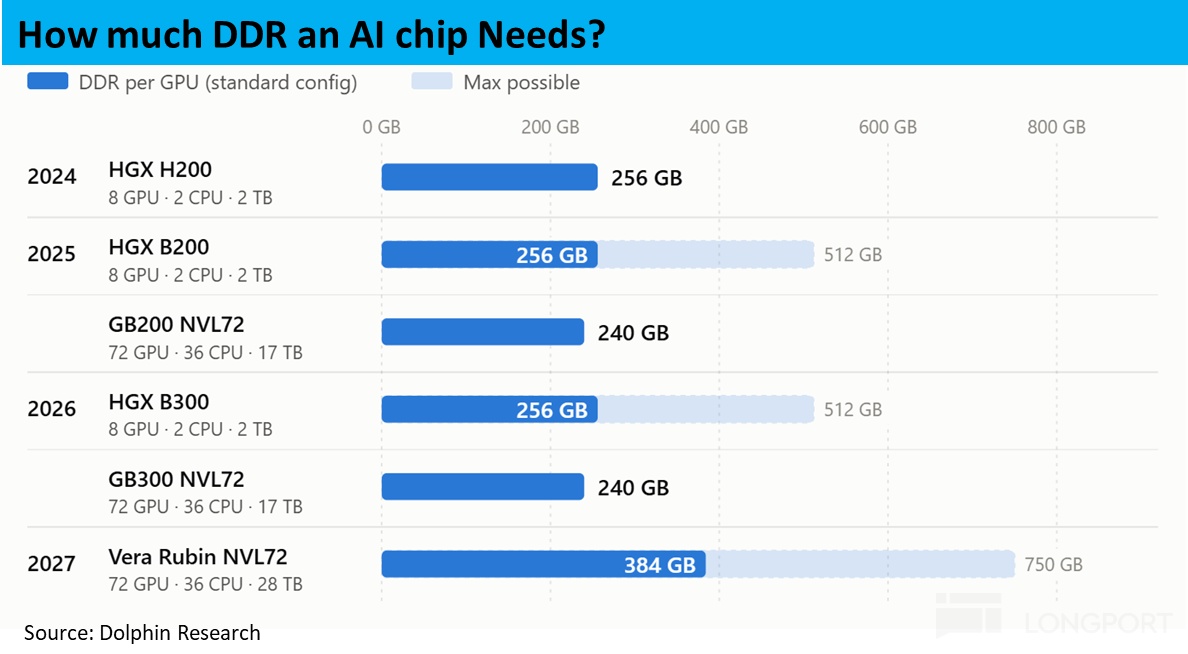
AI XPUs do not use DDR directly, but CPUs in AI servers do. For Nvidia B200, eight GPUs pair with two x86 CPUs and 2 TB of memory, implying ~256 GB DDR per GPU.
As CPU:GPU ratios in AI servers rise (B200 at 1:4, VR series already at 1:2), per-system memory demand keeps increasing. Weighted by shipments, we estimate host memory per XPU rises from ~220 GB in 2025 to ~290 GB in 2028.
AI clusters also include inference servers without HBM, CPU compute nodes, and storage nodes, all consuming DDR. These are hard to forecast by product, so we add ~25–33% extra DDR for this category.
d. Demand summary: servers take center stage
Server (incl. AI) demand share rises from ~34% in 2025 to ~59% in 2028. From 2025–28, general-purpose servers, AI DDR and HBM each contribute ~30% of demand growth; conventional products contribute less than 10%.
Implication: the pricing anchor shifts from consumer electronics to cloud capex — buyers are more capitalized and price hikes transmit more easily, but demand concentration raises cyclical risk if AI spend cools. Also, tightness is not only HBM: incremental DDR for servers (~145 bn Gb) is over 2x HBM’s (~62 bn Gb), so conventional DRAM is also tight.
2.2 Industry supply: 2026 is a lull, 2028 sees concentrated release
Supply is more visible than demand. In short, DRAM output depends on two drivers: wafer capacity and bit output per wafer.
Wafer additions are constrained by cleanroom build timing, typically 2–3 years from ground-breaking to volume, making 2–3 year capacity fairly set today. Bit per wafer depends on node, HBM yield, and wafer allocation between DDR vs. HBM.
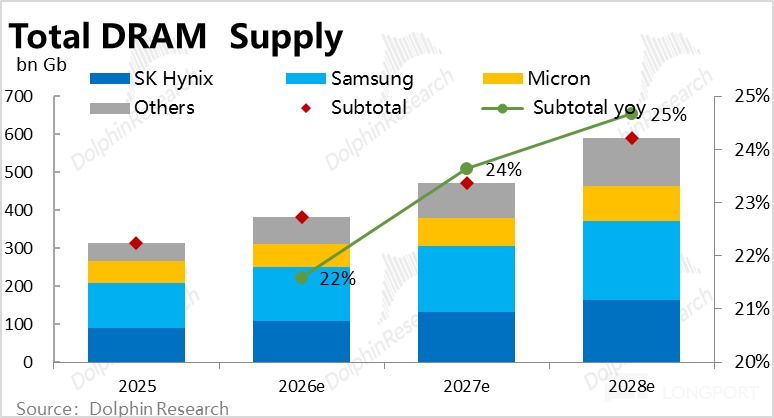
We estimate industry DRAM bit supply (incl. HBM, adjusted for CoWoS losses) rises from ~314 bn Gb in 2025 to ~589 bn Gb in 2028, growing ~22–25% p.a. in 2026–28.
a. Wafer capacity — three majors expand in parallel, HBM prioritized
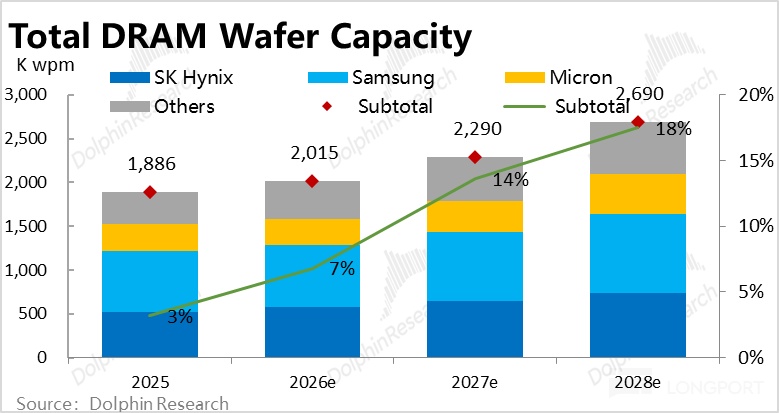
At the wafer base, industry DRAM wafer capacity (monthly) rises from ~1.89 mn to ~2.69 mn, up ~40%, back-end loaded with new capacity releasing meaningfully from 2027.
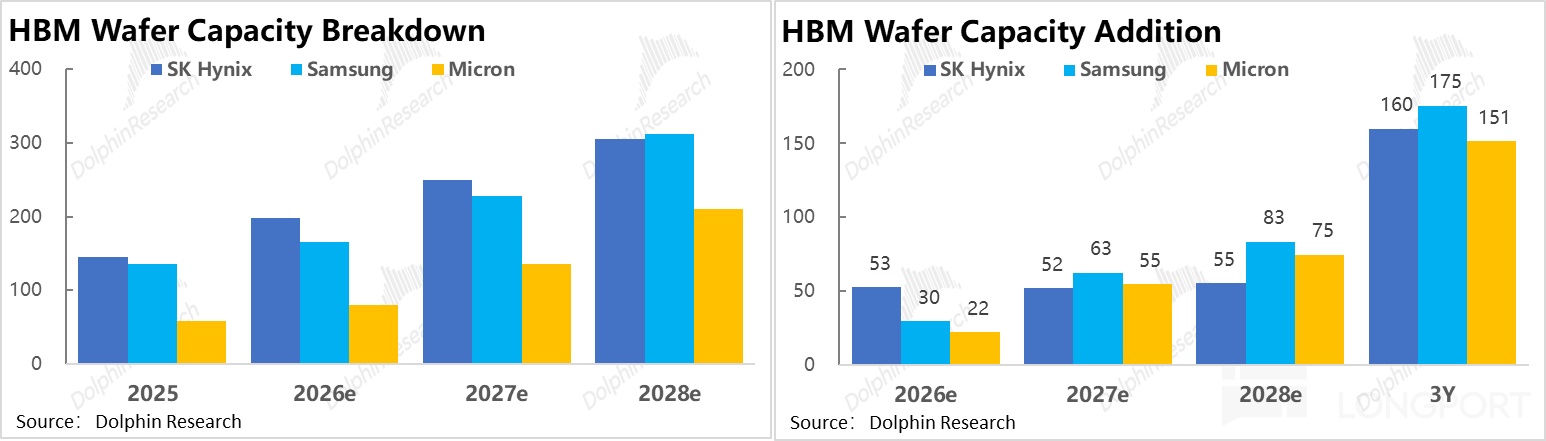
Among the big three, hynix’s gross additions roughly match Samsung, adding just over 200 kpwm in 2025–28. Micron adds ~140 kpwm, less in absolute but largest in relative terms (+46%). HBM wafer additions are similar among the three.
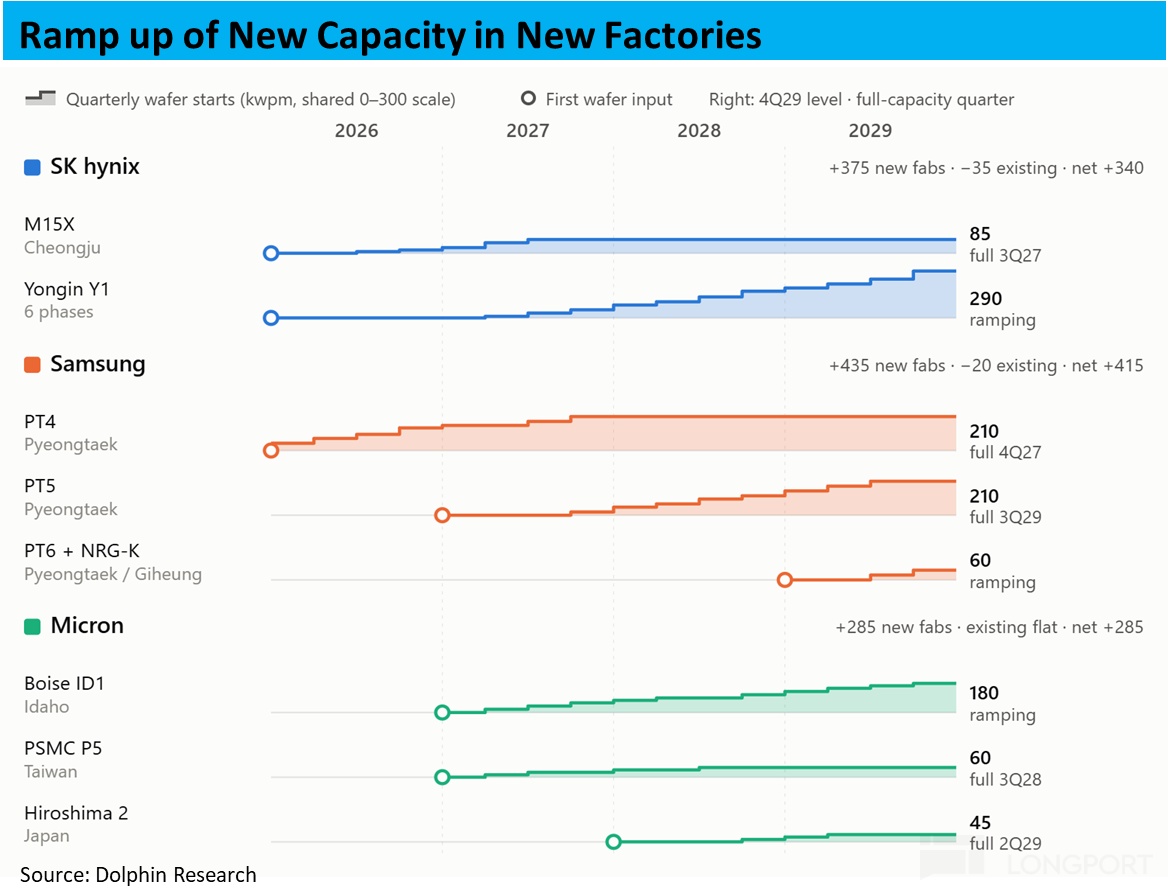
① New fabs come online post-2027; 2026 is a 'lull'
Tight supply partly reflects late-start expansions: in the 2023 downturn, capex was cut and fab timelines delayed. Thus, only a few projects add capacity in 2026, e.g., hynix Cheongju M15X and Samsung Pyeongtaek P4. From 2027–28, hynix Yongin Phase 1, Samsung P5, and Micron’s new Idaho fab ramp, lifting capacity growth.
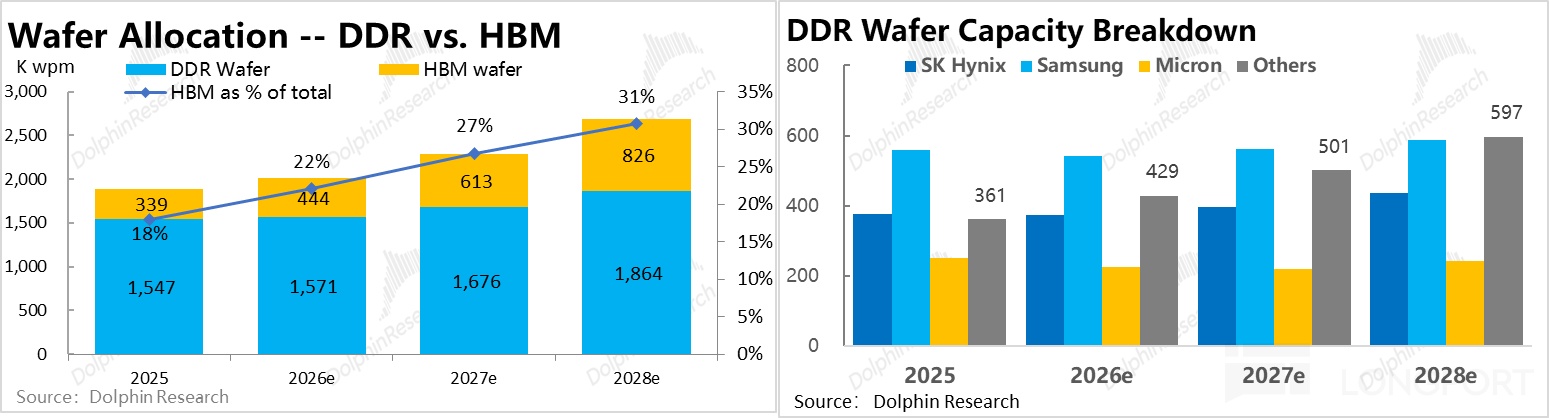
② HBM absorbs most incremental wafers. HBM-usable wafers rise from ~340 kpwm to ~830 kpwm in 2025–28, lifting share from ~18% to ~31%. Meanwhile, DDR-usable wafers at the big three rise only ~7% over three years.
With new wafer additions prioritized for HBM, DDR wafer capacity is effectively flat, underpinning tightness in conventional DDR.
③ China players drive DDR wafer additions
As the big three largely hold DDR capacity steady, DDR wafer growth comes mainly from China players like CXMT, whose share rises from ~23% to ~32%.
Since conventional DDR has limited tech barriers, if domestic capacity keeps rising and AI demand peaks, conventional DDR tightness could reverse materially.
b. Capex broadly maps to new capacity
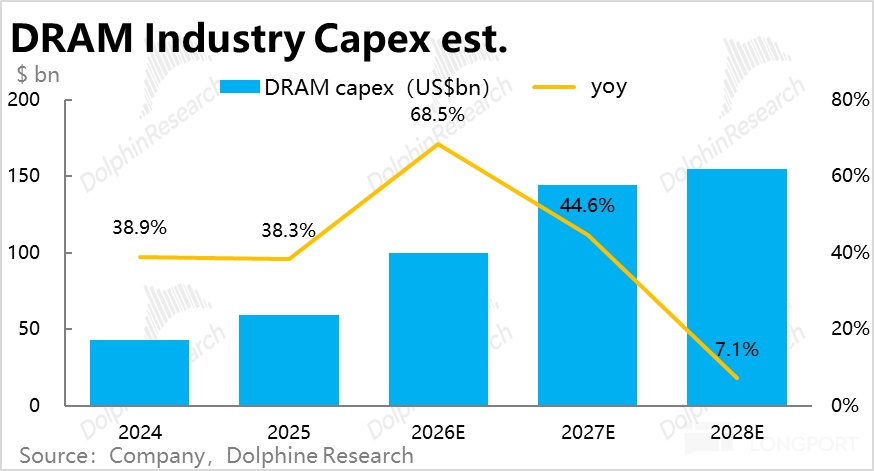
Wafer capacity forecasts can be cross-checked with capex. Industry DRAM capex rises from ~$43 bn in 2024 to ~$100 bn in 2026, peaking in 2026 (~+69%).
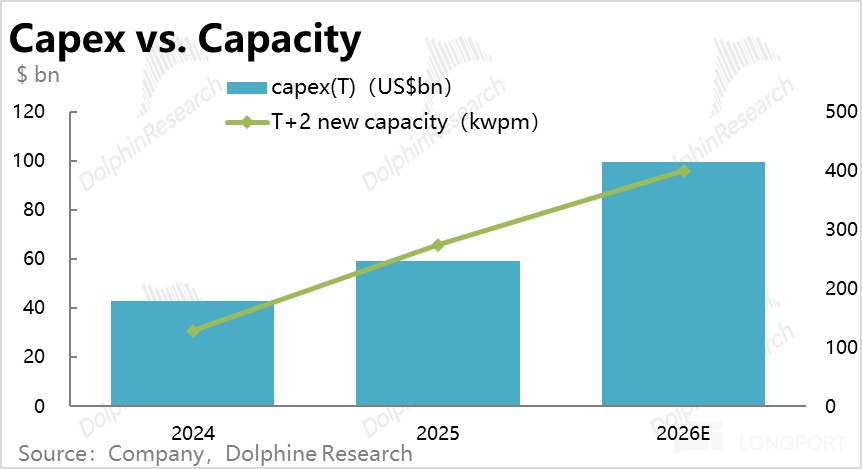
Market then expects capex growth to slow, falling to ~7% in 2028 (implying 2029–30 capacity growth slows, though forecasts can be off). With capex leading capacity by ~2 years, 2024–26 spend largely sets 2026–28 capacity. Historically, ~$2.2–3.3 bn capex per 10 kpwm maps to 2026–28 additions, broadly stable.
c. Bits per wafer: DDR via node migration, HBM via more wafers
① DDR leverages node migration:
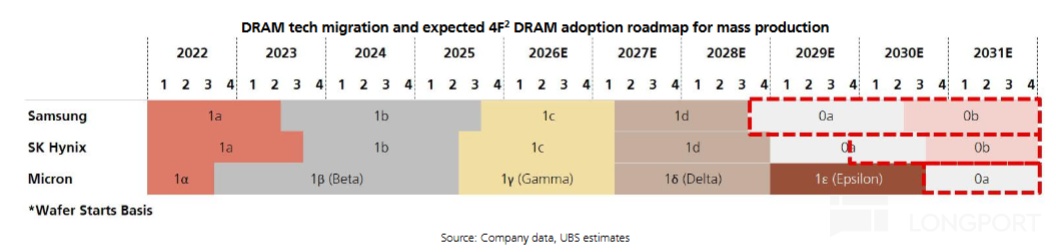
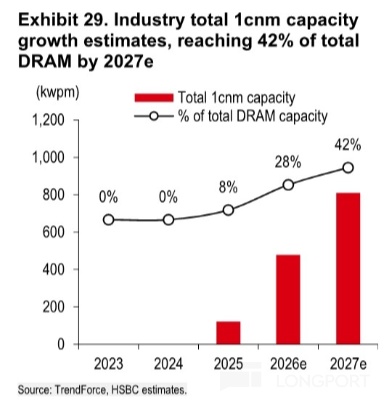
Since DDR-usable wafers grow little by 2028, DDR bit growth relies on node advances lifting bits/wafer. Starting in 2026, the big three ramp 1c nodes, then trial 1d in 2027–28, with 1c reaching ~50% share around 2027.
We assume DDR bits/wafer up ~18% in 2026, then ~14–10% in 2027–28, based on multi-source references.
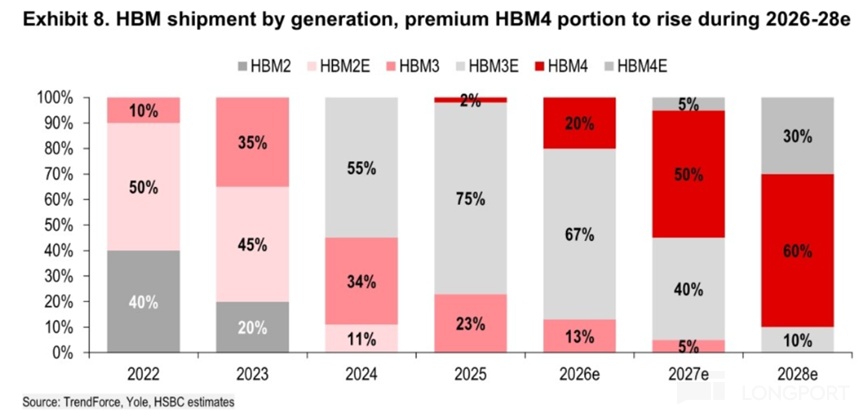
② HBM bits/wafer rise more slowly: node gains are offset by generational shifts. From 2026, output moves from HBM3E toward HBM4/4E, with higher stack counts and tougher processes increasing losses.
We estimate hynix HBM bits/wafer up only ~2–6% p.a., with bit growth relying on more wafers. Samsung and Micron, lagging previously in output, close the gap as Samsung’s utilization/yield improves post certification with Nvidia and Google, unlocking previously 'idle' HBM capacity.
③ Net bit output: HBM is the 'pump' drawing from DDR supply
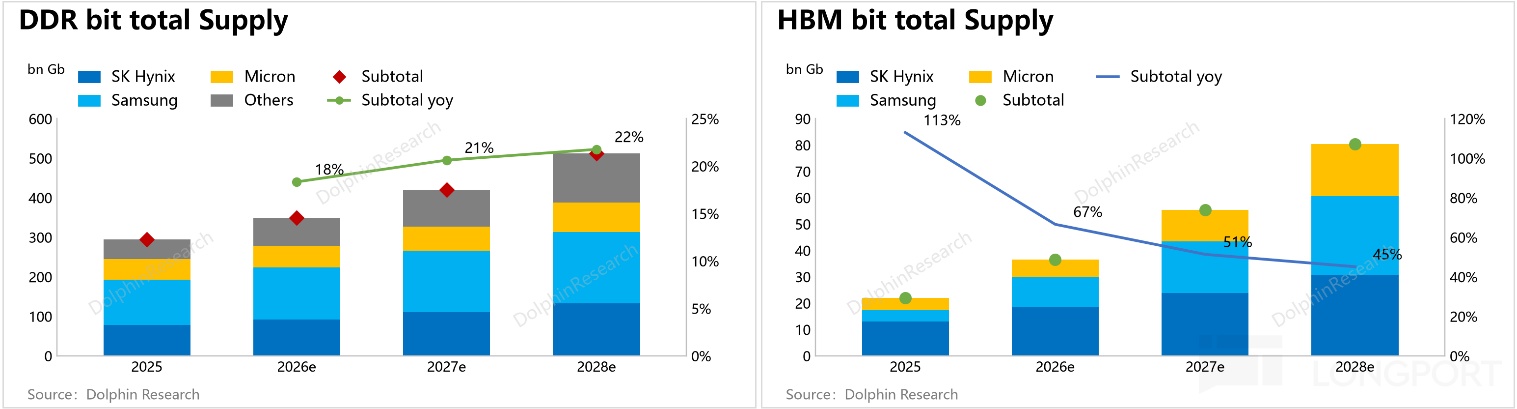
HBM growth rate far outpaces DDR, but DDR adds more absolute bits. From 2025–28, DDR bit supply rises from ~295 bn Gb to ~512 bn Gb, ~20% CAGR accelerating each year. HBM (pre-packaging) rises from ~22 bn Gb to ~80 bn Gb, ~54% CAGR decelerating.
By vendor, total bit supply grows ~18–22% p.a. across the big three, with different mixes: hynix’s HBM grows slowest (~33%), DDR fastest (~20%); Samsung’s HBM output rises ~7x with over half from bits/wafer catch-up; Micron channels most new wafers to HBM, with growth concentrated after its 2028 fab launch.
④ HBM shifts from 'one dominant' to 'three-way', with hynix’s HBM share falling from ~59% to ~38%, roughly tied with Samsung. Since new HBM wafers added are similar (~150–180 kpwm) among the three, Samsung yield ramp is the key variable for hynix’s share.
d. Capacity adjusted for CoWoS
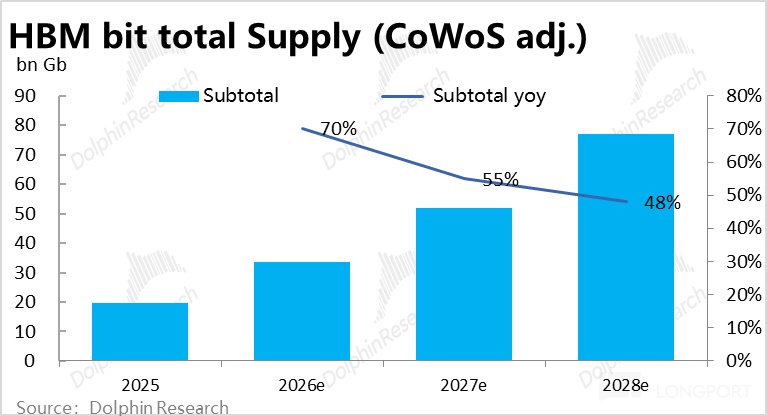
HBM is co-packaged with GPUs/ASICs via CoWoS. Assuming CoWoS yield rises from ~90% in 2025 to ~96% in 2028, net HBM supply rises from ~19.7 bn Gb to ~77 bn Gb. As noted earlier, advanced packaging also constrains AI chip output, not just memory.
2.3 Supply–demand gaps: peak in 2026, DDR and HBM diverge
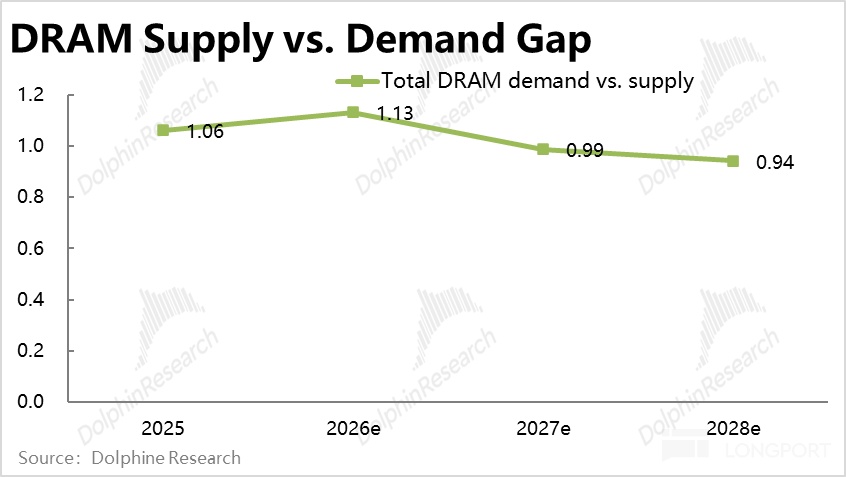
Combining the above demand and supply, we expect industry DRAM (incl. HBM) supply–demand tightness to peak in 2026 (demand ~13% above supply), balance in 2027, and tip slightly into surplus in 2028.
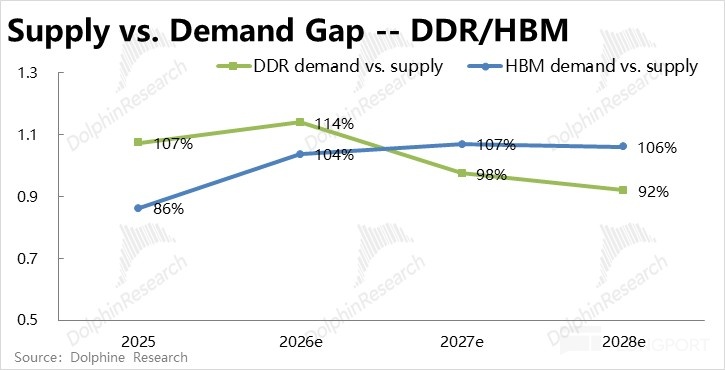
Structurally, DDR vs. HBM diverge: DDR is tightest in 2026 and loosens in 2027–28, while HBM tightens. Pricing-wise, conventional DRAM sees the sharpest price hikes in 2026, slower increases in 2027, then more pressure to decline in 2028; HBM retains pricing support in 2027–28.
a. Conventional DRAM: loosens in 2027
We estimate DDR supply–demand ratio (supply/demand) moves from 1.07 in 2025 to 1.14 in 2026, then down to 0.98 and 0.92 in 2027–28 (2026 shortfall ~49 bn Gb, 2028 surplus ~41 bn Gb).
Even if DDR loosens overall, falling prices could trigger demand rebound in traditional endpoints, and could also push vendors to reallocate wafers faster from DDR toward HBM. This would make DDR a bit tighter and HBM a bit looser at the margin.
b. HBM: tightness rises from 2027, supporting higher prices
HBM supply–demand (incl. customer stock) moves from ~1.04 in 2026 to ~1.06–1.07 in 2027–28, gradually lifting scarcity. This supports consensus that HBM pricing rises materially (per-GB ASP from ~$15 to $20–30).
Note, however, HBM is most sensitive to AI XPU shipments. In 2027, a 10% swing in XPU shipments shifts HBM S/D ratio by ~0.1 — a 10% drop could flip HBM to ~4% surplus, and a 10% rise could widen the shortfall to ~17%.
c. Inventory: 2026 tightness is inflated; watch for destock in 2027
Inventories amplify supply–demand swings: downstream customers pre-buy and sometimes double-order in price-up cycles. UBS estimates ~40 bn Gb of customer restocking in 2026 (~10% of DDR demand). If accurate, ~80% of the 2026 DDR shortfall is restocking-driven.
Thus, a key 2027 risk is whether customers destock, hinging on their view of future tightness. Since DDR S/D is roughly balanced in 2027 on our numbers, inventory release could swing to surplus sooner, pulling forward price pressure from 2028 into 2027.
At this point, we have finished our full analysis of the DRAM industry supply‑demand landscape. 2026 will be a supply gap window where DDR tightness peaks. DDR supply will ease in 2027‑2028, while HBM takes over as the bottleneck.
Supply and demand lay the foundation for memory chip earnings. Yet industry trends alone tell only part of the story. SK Hynix’s client partnerships and long‑term agreements will define its actual gains and downside risks amid this cycle.
Industry upcycle does not guarantee easy profits at the company level. This note stays on SK hynix, examining its partnerships with NVIDIA, major ASIC customers, the three vendors’ LTA playbooks, and our forward estimates and valuation.
In the AI era, incremental memory demand concentrates with a handful of XPU and cloud players, and products are increasingly customized. Becoming a primary supplier to top customers is therefore critical. In this pricing round, LTAs have also become the main tool for both sides to lock in supply and demand. We first review customer share (bit basis unless noted), then LTAs.
3.1 Main customers: SK hynix’s moat shifts from exclusive to leading
1) Static view of the industry: NVIDIA is the dominant buyer
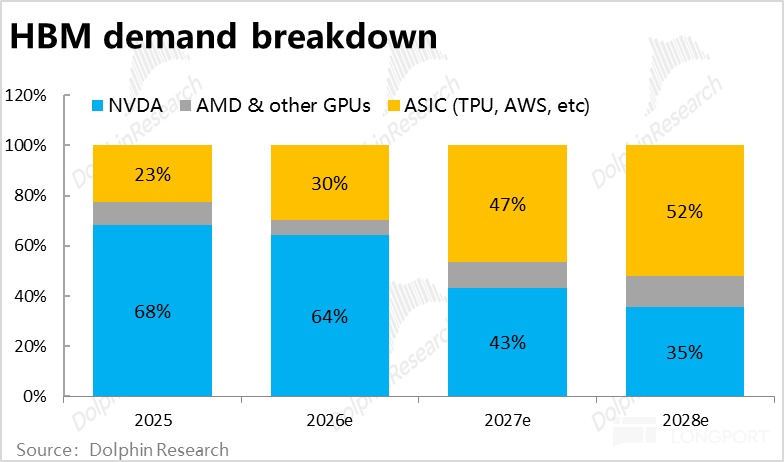
HBM demand is highly concentrated. By our estimates, in 2025–26 NVIDIA alone consumes roughly two-thirds of industry HBM, AMD about 6%–9%, and ASICs such as Google TPU and Amazon Trainium together about 23%–30%. In other words, whoever secures NVIDIA’s primary share locks in the largest and most visible block of the market.
2) Who supplies whom?
By NVIDIA, AMD, and ASIC categories, which memory vendor is the key supplier to each top customer? In short:
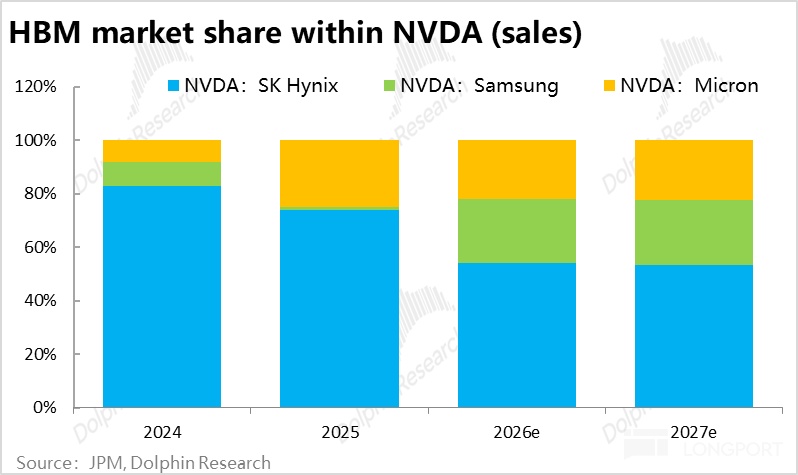
NVIDIA: SK hynix has long been the main supplier. On a purchase value basis, SK hynix supplied about 70%–90% of NVIDIA’s HBM through 2025 (revenue recognition basis). As Samsung and Micron gain share thereafter, SK hynix’s share is expected to slip to just above 50%.
AMD: Samsung is the primary, Micron the secondary supplier. We have not seen evidence of SK hynix supplying AMD, but AMD’s share is small so the impact is limited.
ASIC is the fastest-growing segment, mainly supplied by Samsung and SK hynix with similar shares. Microsoft Maia 200 is reportedly sole-sourced to SK hynix, Amazon Trainium 3 mainly to SK hynix, OpenAI’s Jalapeño reportedly to Samsung, while Google TPU and Meta MTIA are co-supplied with differing views on who leads (table below from UBS and JPM for reference).
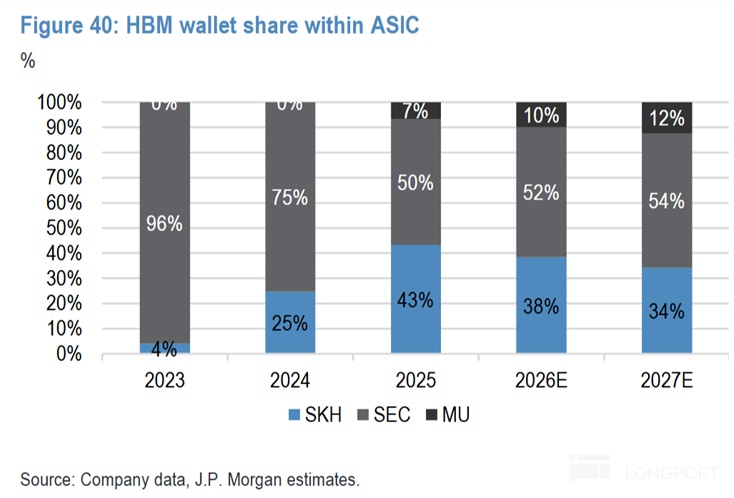
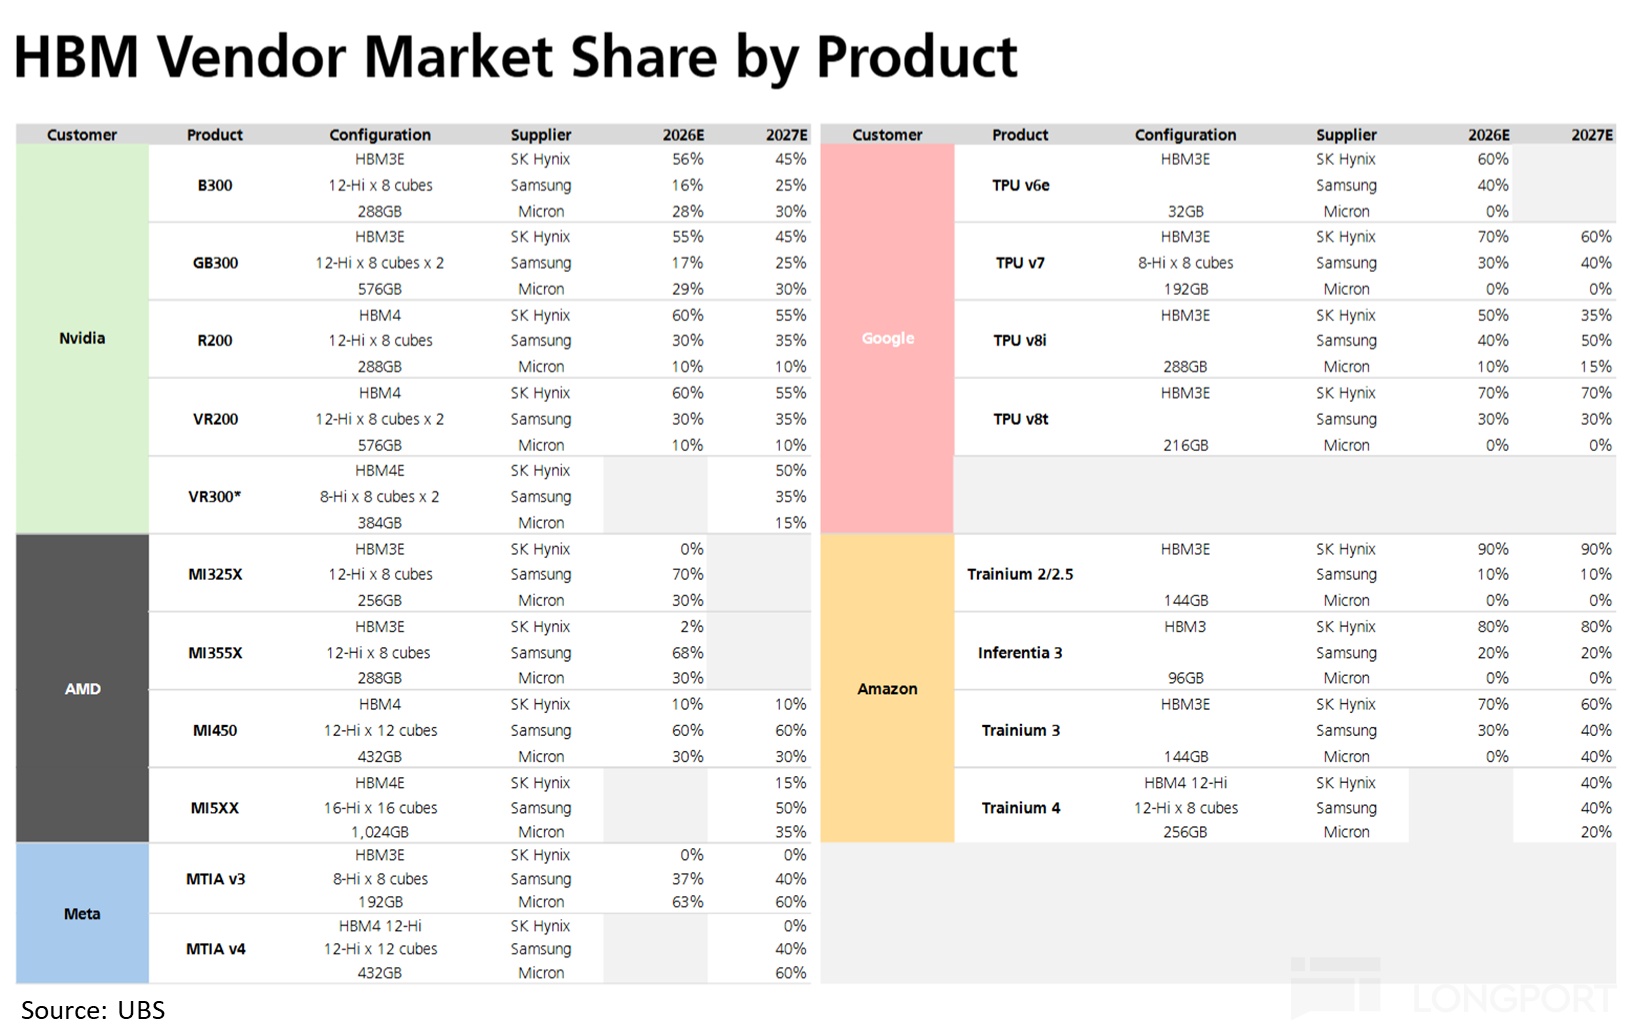
3) SK hynix’s customer mix: NVIDIA is No.1 but getting diluted
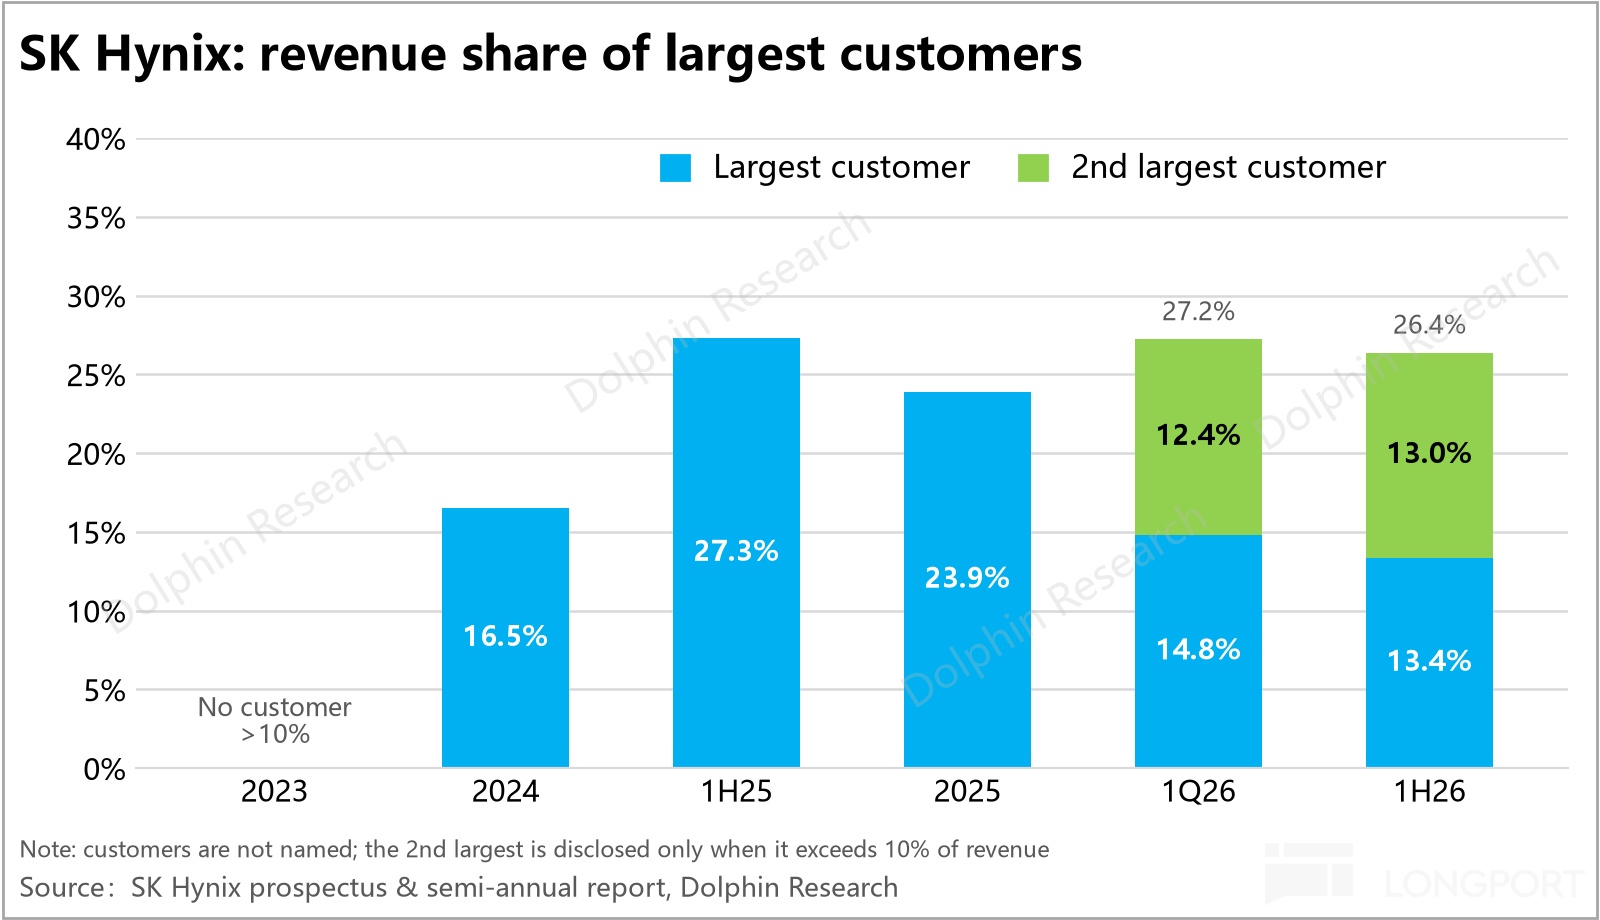
Per company disclosure, the largest customer in 2025 (very likely NVIDIA) contributed roughly one-quarter of total revenue. By 1H26, the top two customers each accounted for just over 12%. NVIDIA’s share fell mainly because DDR price hikes diluted HBM revenue, yet the top two still exceed one-quarter combined, so dependence on top customers remains high.
4) Dynamic view: diversification on both supply and customer sides
Supply side: from one dominant to three running neck and neck. As Samsung and Micron gained certifications from NVIDIA and major ASIC customers, all three can now deliver at scale, and capacity and share are converging quickly (see 2.2c). Customer side: large buyers are shifting from single primary to multi-sourcing. In 2023, ~90% of NVIDIA’s HBM came from SK hynix, and ~96% of ASIC from Samsung.
By 2027, the top supplier on both sides falls to just above 50%, and Micron enters both pools. Exclusive supply has largely disappeared among major customers.
A concern is that within fast-growing ASIC customers, SK hynix currently lacks a clear share or recognition advantage. This is where it needs to push harder.
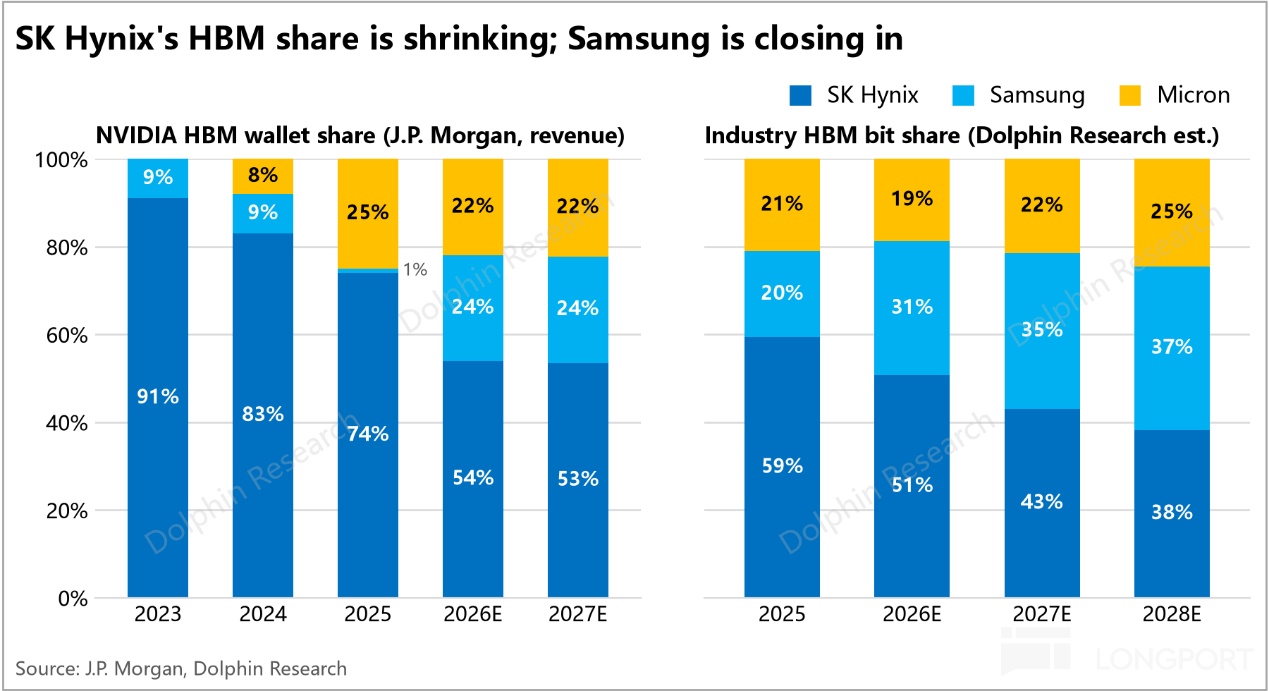
What does layered diversification on both supply and demand mean for SK hynix and the industry? In our view:
First, competition will intensify. Once all three qualify, share will be reallocated quickly with each generation’s certification, yield, and delivery (HBM4/HBM4E). Customer trust becomes even more important at this stage.
As large customers broadly add second and third sources, capacity gaps among the Big 3 will also narrow. With more alternatives, NVIDIA and others are likely to be tougher and more selective in negotiations.
Second, dispersion does not mean weaker earnings. While more diversified supply increases competition and buyer power, the decisive driver over the next 2–3 years remains industry supply-demand. The shifting competitive pattern is secondary in comparison.
In shortage, all vendors run full and sell out. Only when supply loosens and vendors must fight for demand will issues surface.
Third, dispersion lowers single-customer risk but amplifies LTA-strategy risk. NVIDIA’s product cadence and config changes will have less impact on SK hynix. But SK hynix’s ‘low lock-in, no cap’ LTA approach is built on a leadership position; as its edge moves from exclusive to leading, downside risk in a downturn rises.
3.2 New LTA wave: raises the floor, does not erase the cycle
Memory is highly commoditized, with prices swinging with supply-demand. Downstream buyers have traditionally purchased as needed at spot or short-tenor prices, making memory stocks highly cyclical with low LT visibility. In this imbalance, LTAs have been widely adopted. Some investors believe they shift cycle dynamics, improving earnings stability and potentially lifting valuation multiples.
Historically, old-style LTAs protected buyers more. They loosely specified volumes, giving buyers allocation priority in upcycles, but allowing cuts in downcycles with low penalties. Sellers expanding on that risked inventory build and idle capacity. This round differs mainly in three ways:
1) Penalties are pulled forward. Buyers previously paid little to no prepayments; now deposits, prepayments, or third-party guarantees are common. If buyers cut, sellers can seize deposits, making volumes more binding. Micron even said LTA visibility supports raising FY27 capex.
That said, prepayments usually cover only a fraction of contract value (Micron’s is ~16%–21% of the contract floor value). They do not fully eliminate downside risk.
2) From floating with market to price bands. Previously, contract prices were reset monthly or quarterly; now many LTAs set a floor and a cap. Micron says three-quarters of its LTAs use a floor-plus-cap model. However, per Bernstein, Micron’s floors are roughly 50% below current prices, leaving vendors exposed to sizable price downside.
3) Counterparties shifted from OEMs/channels to cloud players. Earlier LTA buyers were PC OEMs, module makers, and distributors with weaker balance sheets. This round’s anchors are NVIDIA and hyperscalers with strong finances, making non-performance much less likely.
Risks have not vanished, they pivot to whether cloud capex turns down. If AI ROI lags, LTAs may protect volume and floors, but repricing pressure can still flow back to vendors.
In short, LTAs can lock in some volume plus a price band, lifting the earnings floor but not removing cyclicality. Protection depends on coverage and the floor/ceiling width.
3.3 SK hynix’s LTA stance: low volume lock, floor-only, no cap
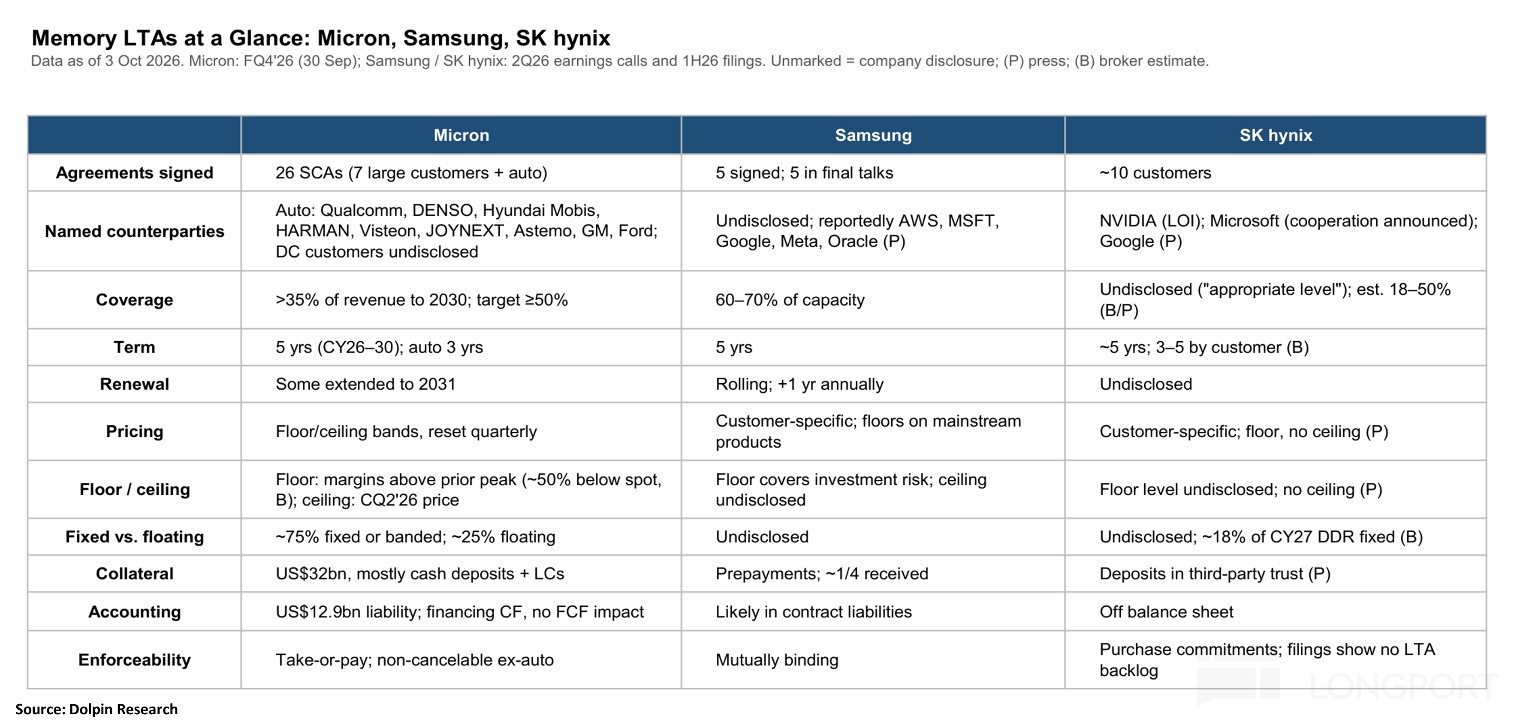
All three vendors sign LTAs, but with different leanings. Micron is the most willing and transparent, locking volume, setting price bands, taking cash deposits, and disclosing metrics. SK hynix is relatively lukewarm, with three key traits:
1) Lower coverage. While not officially disclosed, UBS estimates that less than 20% of SK hynix’s 2027 DDR shipments are on fixed-price terms. Management also says LTA share will stay ‘appropriate’ to leave room to capture upside when market conditions favor sellers.
Given repeated emphasis on flexibility, coverage is likely indeed low. 2) Floors only, no caps. Unlike Micron’s many floor-plus-cap LTAs (with caps reportedly set at 2Q26 market prices), SK hynix generally sets only floors. Upside passes through, and HBM still runs on annual deals rather than 5-year LTAs.
But no caps come with a cost. Customers are less willing to pre-commit, likely one reason for lower coverage.
3) Deposits do not add cash immediately. Micron’s prepayments are largely cash, going straight onto its balance sheet as usable funds. By Korean media reports, SK hynix’s deposits are escrowed with a third-party trustee and only accessible upon buyer default, offering no immediate cash-flow benefit.
Takeaway: SK hynix prioritizes offense over downside protection. The approach is ‘low lock-in, floor-only, no cap’ — maximizing upside elasticity with lighter protection on the way down. If tightness and price gains persist, its earnings torque could exceed peers; if the cycle turns, downside protection is weaker.
The divergence reflects positioning. SK hynix leads HBM with better yields and feels less need for downside insurance. Micron, the smallest scale and building big in the US, seeks LTAs for funding and expansion visibility; Samsung, having trailed in HBM, is using LTAs and prepayments to secure customers.
IV. Earnings and valuation: torque hinges on pricing; valuation near the cycle top
4.1 DRAM: pricing drives elasticity
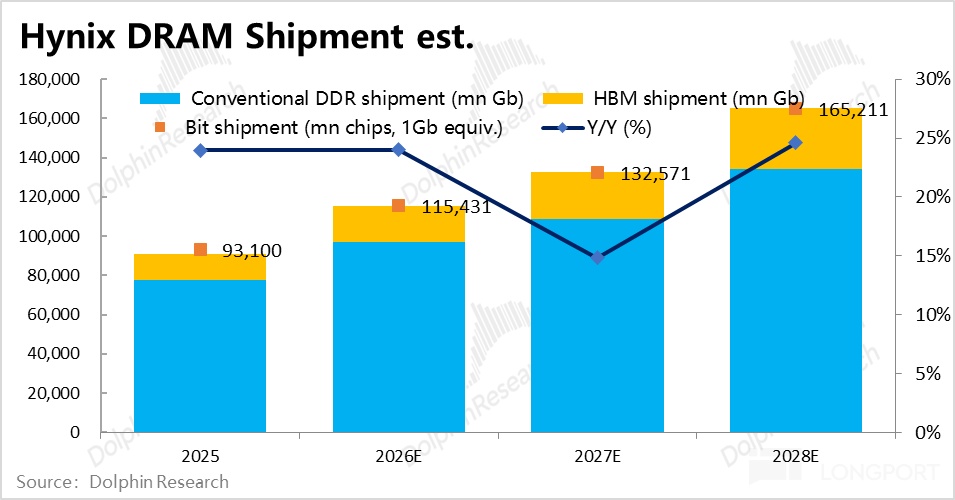
a) Shipments: HBM grows faster, DDR remains the bulk. We estimate SK hynix DRAM wafer capacity rises from ~520k to ~740k wpm in 2025–28. HBM shipments go from ~13 bn Gb to ~31 bn Gb (+~30%–40% CAGR); DDR from ~78 bn Gb to ~135 bn Gb, with 2027 new capacity prioritized to HBM and DDR up only ~12%.
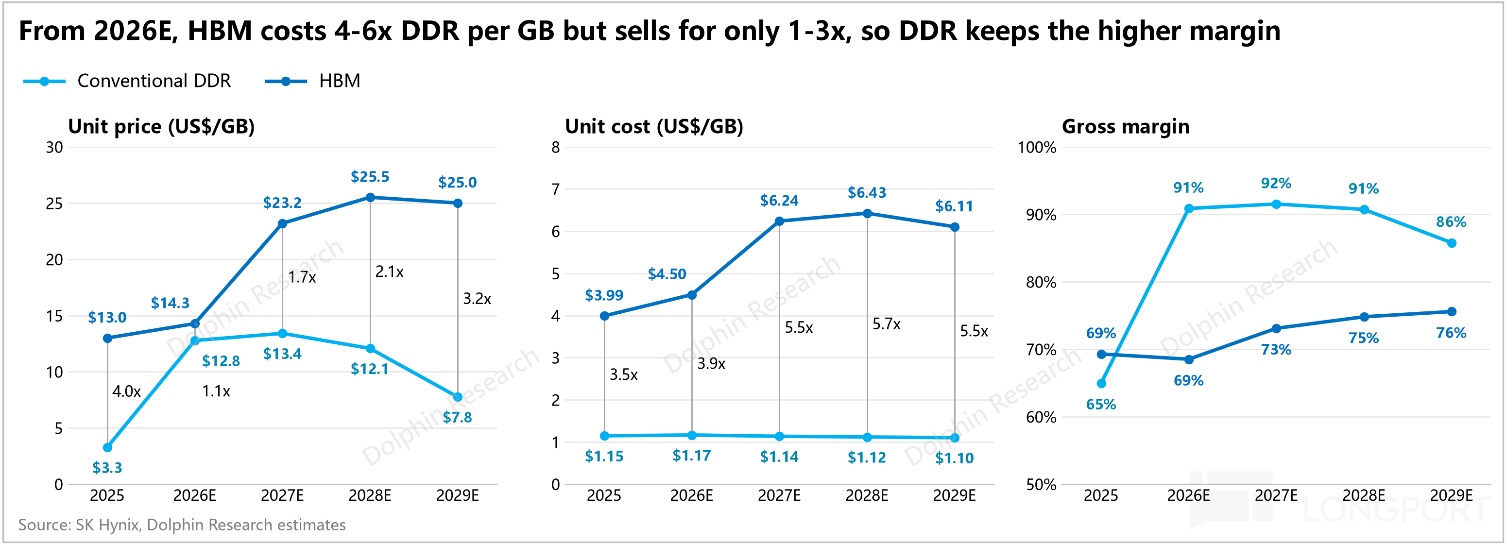
b) Pricing: DDR up then down, HBM takes the baton. With capacity largely set, torque depends on price. Based on our supply-demand view, we take a cautious stance: mainstream DDR ASP up ~290% YoY in 2026, up ~5% in 2027, then down ~10% in 2028.
The 2026 shortage peaks and restocking compounds the spike. In 2027, supply-demand balances, prices peak and start easing, but inertia keeps full-year slightly higher. From 2028, new fabs ramp, supply turns surplus, and prices trend down.
HBM: up ~10% in 2026, up ~62% in 2027, and up ~10% in 2028. HBM is priced annually; 2026 prices were set in a loose 2025. In 2027, repricing meets tighter supply and higher HBM4 mix, taking per-GB from ~$14 to ~$23. Even then, HBM revenue per wafer is only ~60% of DDR, and supply remains tight, leaving further upside potential.
c) Gross profit: DDR still carries the profit load. On costs, DDR and HBM diverge. DDR unit cost falls as nodes mature, but node transitions and depreciation limit the decline to ~2% annually from 2027, holding GPM at ~91%.
HBM costs rise into HBM4 with higher stacks and harder process, then fall. Unit cost up ~13% and ~39% in 2026–27, then down ~5% as processes mature by 2029. Pricing rises more, lifting HBM GPM from ~69% to ~75%.
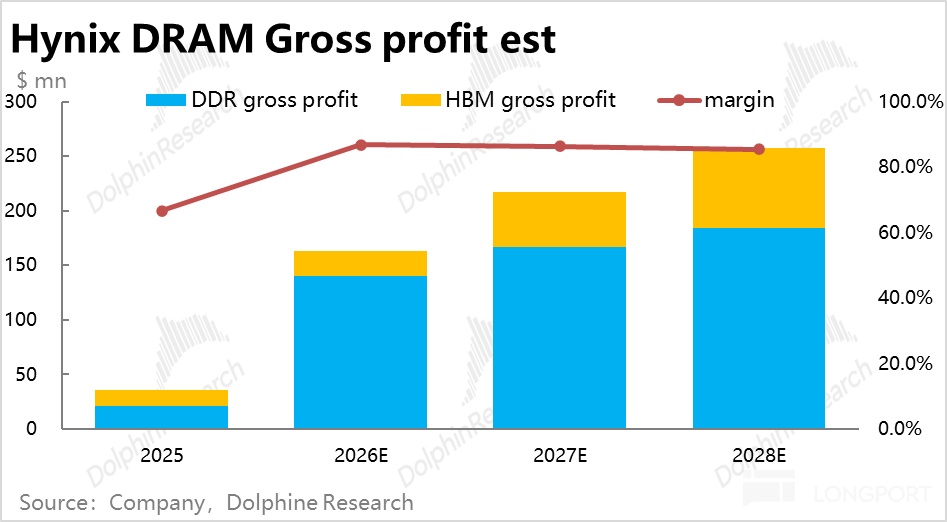
Total DRAM GP rises from $163.0 bn in 2026 to $257.5 bn with GPM ~86%–87%, over 70% contributed by DDR.
4.2 Group earnings forecast
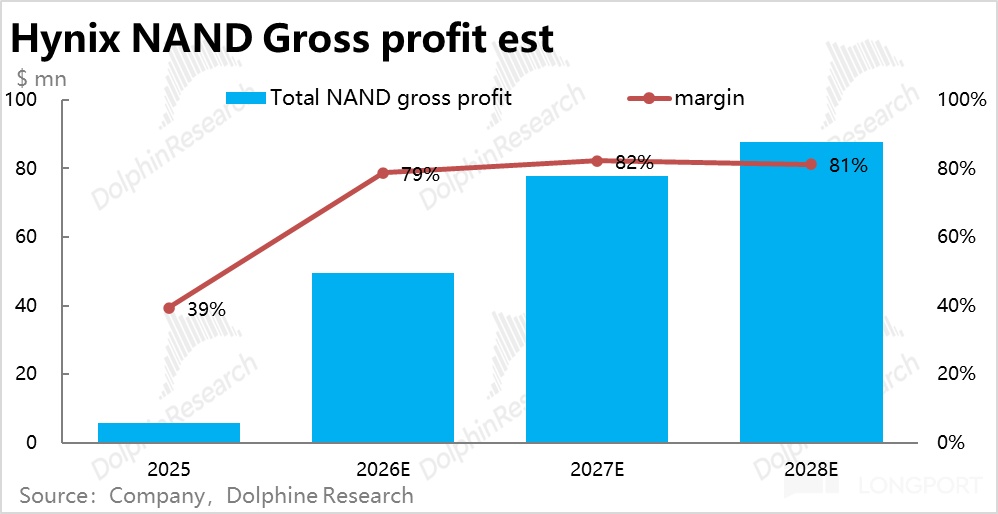
a) NAND: peak in 2027, ease in 2028. As this note focuses on DRAM and SK hynix’s NAND is about one-quarter of total, we go straight to results. Shipments grow ~16%–20% annually; ASP up ~270% in 2026, up ~30% in 2027, then down ~5% in 2028.
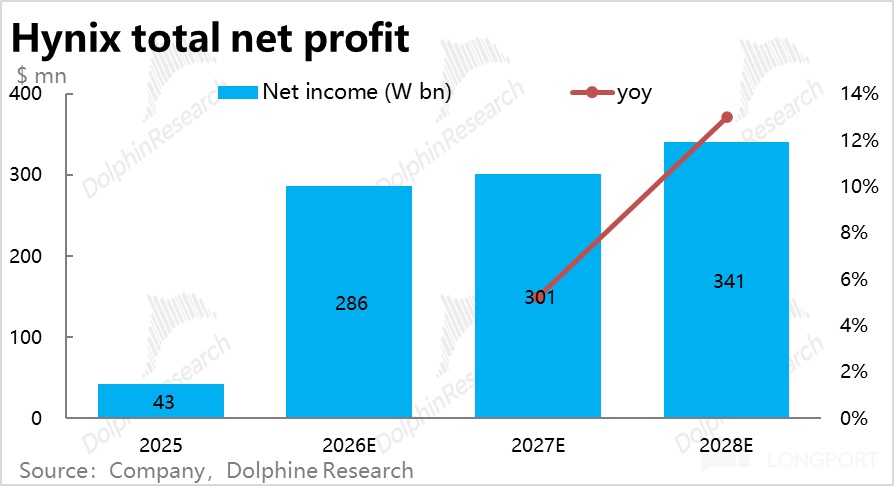
That implies NAND GP from $49.4 bn in 2026 to $87.8 bn in 2028. Summed with DRAM, group profit reaches about KRW 350 tn by 2028 (below market’s KRW 390 tn), or roughly $259.0 bn.
4.3 Valuation framework
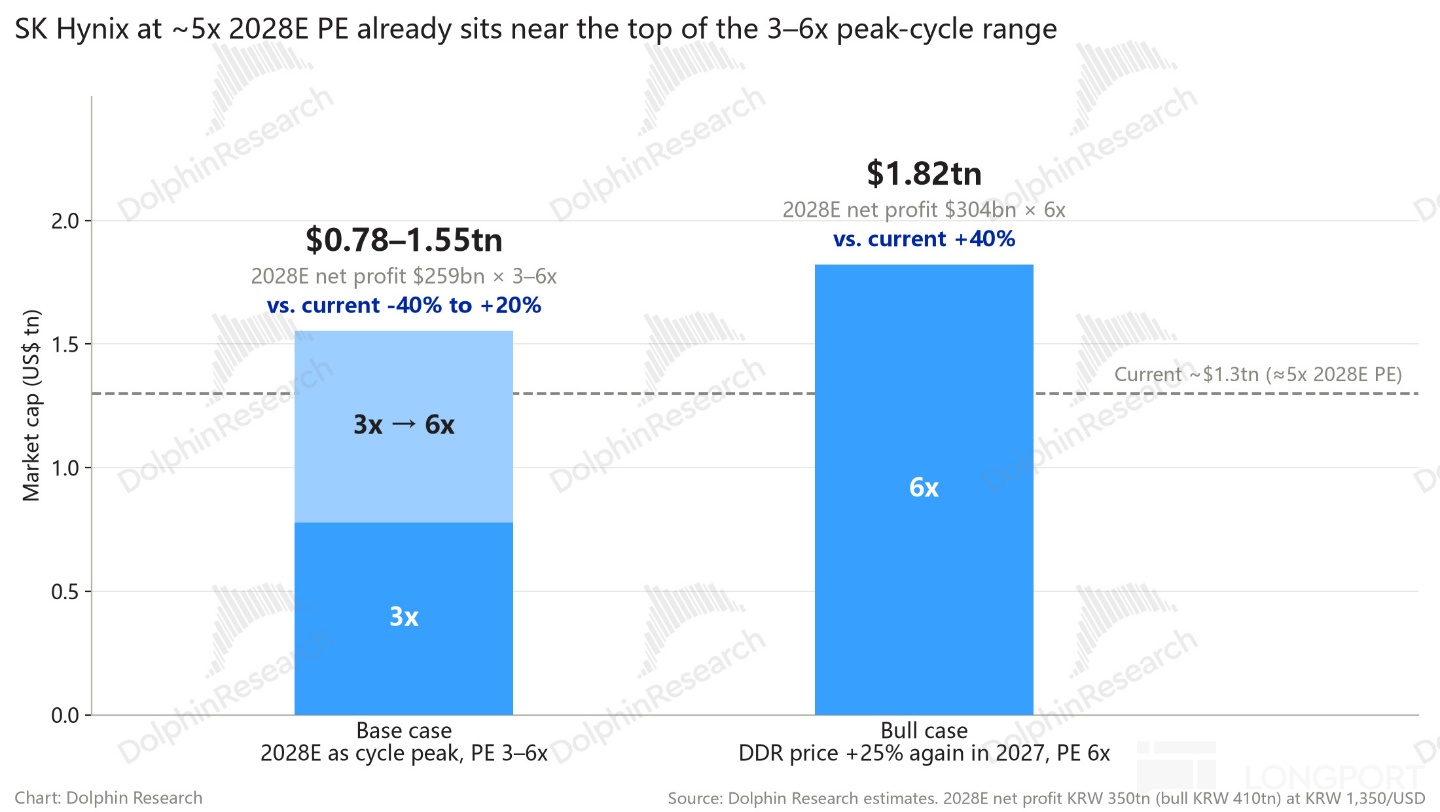
Given memory’s cyclical nature and that visibility on capacity and supply-demand runs through 2028, we take 2028 as the peak of this cycle in our base case, with no view beyond. On that basis, we forecast 2028 net profit of about $259.0 bn.
The key driver is that we expect DDR price gains to largely stall from 2027. We prefer opportunities with decent upside even under conservative assumptions. The remaining question: what peak-cycle PE should apply?
SK hynix’s current US market cap is about $1.3 tn, implying ~5x PE on our profit estimate. Historically, at memory price/earnings peaks, PE is typically ~3x–6x. That puts SK hynix near the upper end of the range today.
On this view, given current demand visibility, SK hynix’s valuation looks reasonably neutral.
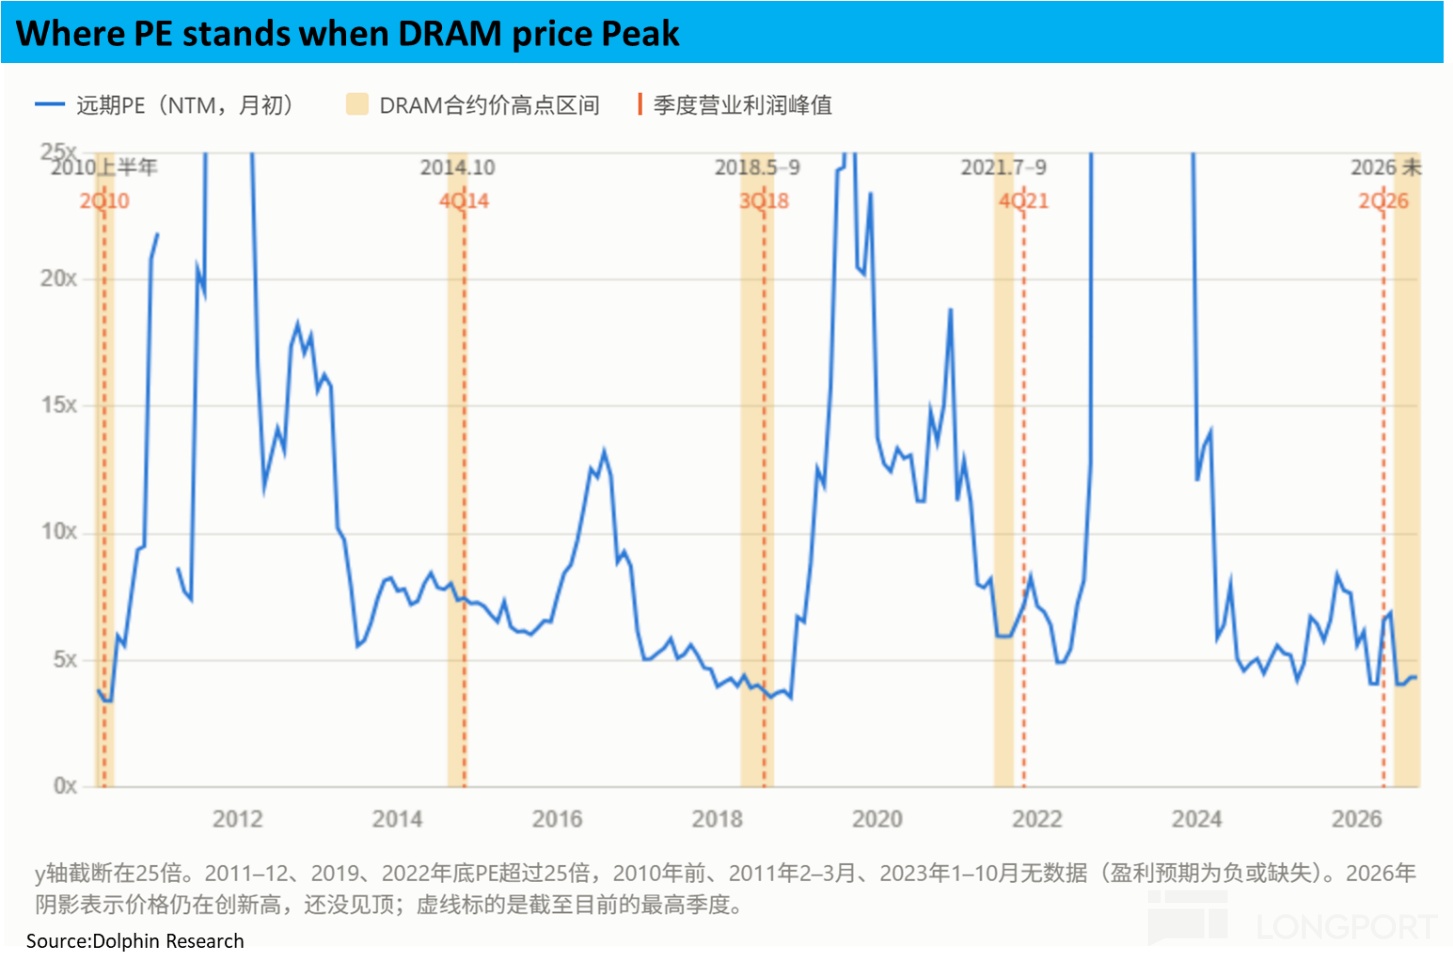
Importantly, memory capacity is broadly known and capped, so ‘surprise capacity’ is unlikely. Demand, however, is highly uncertain, and unexpected upside is not rare. The ultimate question is whether AI memory demand will undershoot sharply, or whether upside surprises emerge.
Which is more likely? Our instinct is that downside vs. current expectations is less likely, and upside surprises are more plausible.
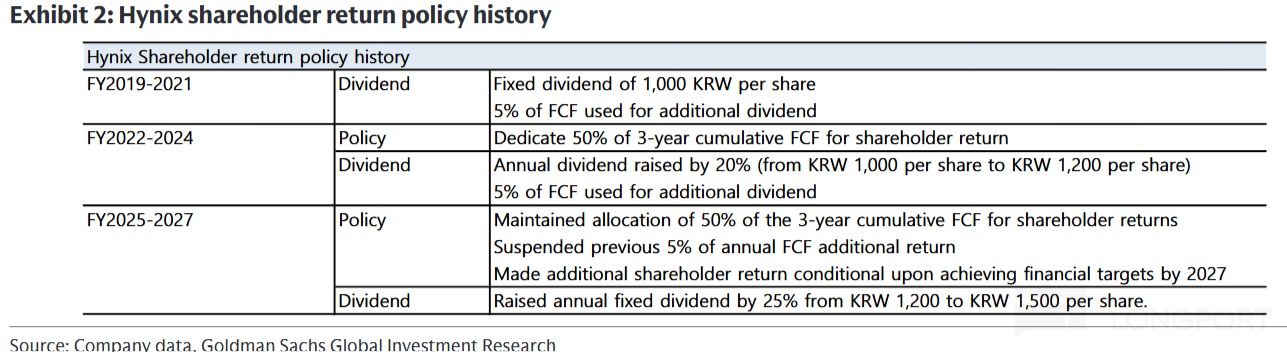
How much do dividends/buybacks matter? SK hynix has announced a generous plan to return at least 50% of 2025–27 FCF to shareholders. Under this framework, actions announced include:
a) A fixed DPS of KRW 1,500 per share each year for 2025–27, with about KRW 2.1 tn executed to date. b) A buyback and cancellation of KRW 12.2 tn in Jan, ~2.1% of then share count.
c) A KRW 40 tn buyback announced on Aug 19, ~3.3% of total shares. This is largely completed and the support to the stock is broadly realized.
On our math, paying out 55% of 2025–27 cumulative FCF returns roughly KRW 260 tn. After deducting amounts already paid, the remaining is ~KRW 206 tn, or ~12% of the current ~KRW 1,740 tn market cap. Even if the share price stays flat, by around early 2028 (once the program completes), shareholder returns could add ~12%.
From that angle, one can back into a more attractive entry. For example, if one targets ~18% return over the next 1.5 years even with a flat stock, a reasonable entry market cap would be about $0.85 tn.
Our stance: holders can stay put, with shareholder returns providing a base yield. Watch for new killer AI apps to scale, such as consumer agents or on-device AI. For non-holders, consider on a pullback toward $0.85 tn; without that, near- to mid-term upside torque looks limited and there may be better setups elsewhere.
In an optimistic case, how much upside is there? If memory stays tight — especially DDR — and we lift DDR pricing to +25% in 2027 and only mild trimming in 2028 (-3%), 2028 profit would reach KRW 410 tn. At the high end of the 6x PE peak range, that implies a $1.82 tn market cap, ~40% above today.
<End of full text>
Historical Dolphin Research on SK hynix:
‘Memory Power Takes the Baton from Compute Power: Why Did HBM Stand Out?’
‘From HBM Height Limits to NAND Spec Bumps: Nvidia vs. Memory Power — Who Holds the Leverage?’
I. Dolphin Research AI Memory series
SanDisk (Part 1): ‘AI Inference Boom: Can 'Unlucky' SanDisk Rise Like a Phoenix?’
SanDisk (Part 2): ‘NAND’s 'Prolific' Nature: How Can SanDisk Hold 80% GPM?’
SanDisk (Part 3): ‘From Supporting Role to Center Stage: How AI Inference Can Flip the Script for NAND?’
II. Dolphin Research AI DC Interconnect series
CPO sector
‘AI Hyper-Connectivity: Racing Toward Light?’ ‘The 'Copper' Lady Won’t Leave! CPO: Real Opportunity or Mirage?’
Networking architectures
Nvidia networking: ‘AI Era DC Interconnect: Beyond Single Chips, Win by 'Net' — Is There a China Angle?’
DC networking — AMD vs. Nvidia: ‘AMD Arm-Wrestles Nvidia: Is Helios Ready?’
Google networking: ‘Challenging Nvidia’s Hegemony: What Powers Google’s 'Optical Network'?’
Single names
Lumentum (Part 1): ‘From Optical Interconnect Veteran to 'Universal Arms Dealer': What Makes Lumentum Tick?’
Lumentum (Part 2): ‘Lumentum: Capacity Crunch — What Else Is in the Toolkit of the 'Universal Arms Dealer'?’
III. Dolphin Research AI XPU series
Agents and CPUs: ‘Muse Goes Viral: Is This CPU’s ChatGPT Moment?’
…For more, visit Longbridge Dolphin Research.
Risk disclosure and statements: Dolphin Research Disclaimer and General Disclosures
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.