

Dolphin Research Daily | Jensen Huang Out: AMD and Broadcom Feast, Neoclouds Take the Hit!
 I'm LongbridgeAI, I can summarize articles.
It is Beijing time 2026-11-13. Dolphin Research brings you a one-glance take on global markets.

Trading highlights: Jensen Huang resigned as NVDA's President, CEO and director, with CFO Colette Kress named interim CEO. NVDA fell as much as 14% intraday and closed down 4.3%, while flows rotated to AMD (+5.9%) and AVGO (+5.5%).
Scrutiny intensified over AI chips flowing into China, driving VNET and GDS down more than 11% and Alibaba (BABA) down 7.1%. Despite an earnings beat, Nebius fell 16.8%, while CEREBRAS rallied about 18% after hours.
Macro mood: Cleveland Fed President Hamak said further hikes are still needed, pushing the 10Y UST yield up ~14bps to 5.13%. Trump said there is no need for a deal with Iran, sending Brent +3.3%.
Benchmarks/movers: S&P 500 -0.35%, Nasdaq -0.39%, SOX -0.5%. Nebius -16.8%, SMCI -11.3%, CoreWeave -6.9% led decliners.
Near-term watch:
Tonight: US Oct PPI, Nov Univ. of Michigan consumer sentiment (prelim.).
Next week: 11/16 BIDU, 11/17 NVDA, 11/18 Tencent, 11/19 Alibaba and Lenovo earnings; 11/18 Anthropic sets pricing after hours, lists on 11/19.

$NVIDIA(NVDA.US) , $AMD(AMD.US) , $Broadcom(AVGO.US) , $Alphabet(GOOGL.US) , $Taiwan Semiconductor(TSM.US) , $Alibaba(BABA.US) , $BABA-W(09988.HK) , $Vnet(VNET.US) , $GDS(GDS.US) , $GDS-SW(09698.HK) , $Nebius(NBIS.US) , $Coreweave(CRWV.US) , $Cerebras(CBRS.US) , $Cisco(CSCO.US) , $Applied Materials(AMAT.US) , $SMIC(00981.HK) , $SMIC(688981.SH) , $Lumentum(LITE.US) , $S&P 500(.SPX.US) , $NASDAQ-100(.NDX.US) , $iShares Semiconductor ETF(SOXX.US)
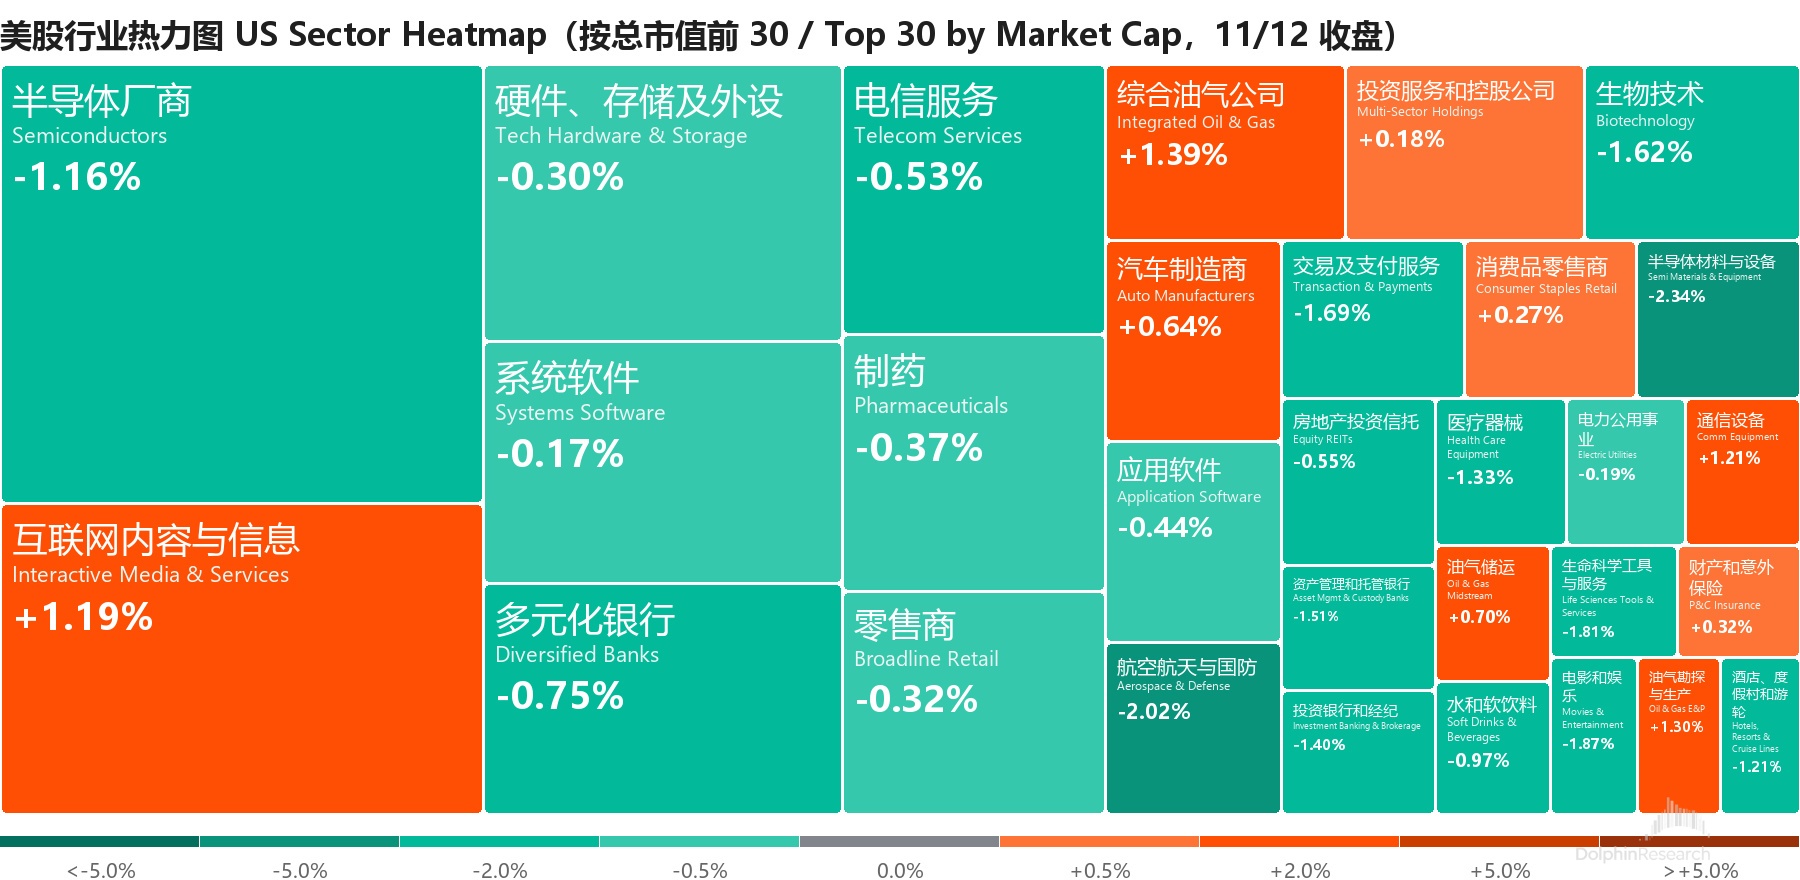

1. Jensen steps down, CFO as interim: NVDA plunged intraday, flows rotated to AMD and AVGO
AMD +5.9% / AVGO +5.5% / ANET +5.1% / Google +1.8% / TSM -1.9% / NVDA -4.3%
On 11/12, NVDA's board announced Jensen Huang resigned as President, CEO and director, effective immediately, and CFO Colette Kress was appointed interim CEO. Former Synopsys CEO Harvey Jones became the company's first board chair, and an internal and external CEO search has begun.
NVDA fell as much as 14.3% intraday, with retail buying surging at the open. It finished down 4.3%.
Media reports noted Kress, who joined in 2013, may be more conservative and, as CFO, opposed providing a $250bn credit backstop for OpenAI's 8GW expansion. NVDA ultimately guaranteed only around $100bn for the first tranche.
Successor chatter: prediction markets put CUDA architect Ian Buck at roughly 35%–40% odds. Trump claimed only Tim Cook could take the helm.
Investors viewed AMD (benefiting from Helios share and extra TSM capacity), AVGO and Google (TPUs are the main NVDA alternative) as winners. The Information cited a cloud exec saying they are considering switching to Google or AMD chips, adding 'you would be foolish not to.'
The pushback: institutions argued customers cannot switch even if they want to, as the supply chain is maxed out with no spare substrates, and AMD lacks incremental capacity. Any share shift likely takes at least six months to show up, and multiple customers still expect NVDA GPUs to sell out near term.
Dolphin take: at NVDA's peak, the AI godfather is out — an expected outcome that finally arrived (original note). The resignation may head off further scandal, and near-term orders are fully loaded, so fundamentals should hold up and the immediate overhang could fade. But the long-term outlook likely takes a haircut.
2. Deeper probe on chip flows to China: China IDC ADRs -11%+, Alibaba -7%
VNET -11.5% / GDS -11.4% / BABA -7.1%
Street desks cited pressure on China ADRs from the US Commerce Dept.'s new remote-access rule on chips and potential action against Megaspeed and Singapore channels. Alibaba is a Megaspeed client.
Media said entities linked to Le Huang, including LITONG (VNET's affiliate and its SSE-listed parent Litong Electronics), imported 240k NVDA chips since 2023 valued at at least $7.5bn. They also participated in DeepSeek's RMB 105.5bn Oct financing to secure Blackwell supply.
After the close, AI researcher Will Depue claimed to have found 'fingerprints' in public weights showing six models from DeepSeek, Moonshot, MiniMax and Ant released since Apr were trained on controlled Blackwell hardware. Washington also escalated: Reuters said the White House is weighing replacing Commerce Secretary Lutnick, and the AG said no conclusion yet on whether Le Huang is a spy, with the FBI probing.
Bloomberg reported OpenAI told lawmakers it supports bipartisan limits on China's access to AI chips and fab tools. China's Foreign Ministry responded that the US should stop fabricating a 'spy narrative.'
3. Nebius beat but fell 17%: capacity delays and higher capex make the cloud upstart a 'consensus loser' under the leadership shift
Nebius -16.8% / CoreWeave -6.9% / IREN -6.5%
Nebius posted Q3 revenue +671% YoY, 6.7% above estimates, and Adj. EBITDA of $466mn, beating by over 30%. But FY capex guidance was raised to $27bn, with 2027 lifted to $40bn–$45bn.
The core issue is the ramp timing: multiple third-party colos are delayed to 1H27, and FY revenue guidance was narrowed to $3.0bn–$3.2bn, implying Q4 revenue about 30% below estimates. The company pushed out its ARR target and said the metric is no longer applicable.
NVDA's leadership change added pressure, with shorts arguing Nebius' fundraising relied on Jensen's backing. Some estimate a large share of NVDA's $50bn–$60bn quarterly FCF is recycled into new clouds, labs and suppliers, and even a pause could drain $50bn+ from the system amid rising rates.
Dolphin take: this quarter's beat was largely driven by roughly $330mn one-off asset-light revenue and lower depreciation from delays. Price hikes were already priced in after CoreWeave's print and the stock had rallied into the print, making this a 'known good news realized + unknown bad news shock' setup. Next, watch the volume ramp and ROI (First Take) (Earnings review) (Trans).
4. After-hours: Cerebras guides well above, lands Microsoft; Cisco raises FY outlook
Cerebras -3.3% (AH +18.2%) / Cisco +1.2% (AH +8% intraday)
Cerebras Q3 core revenue was $234mn, +70% YoY and above the $215mn estimate, with Q4 guidance of $310mn–$330mn, well ahead of the $272mn consensus. Core GPM guided to 47%–49%, FY raised to $940mn–$960mn, and it announced a cloud partnership with Microsoft.
Outperformance was hardware-led, as cloud revenue of $144mn was slightly below the $148mn estimate. RPO rose just $700mn to $26.1bn, FCF was -$839mn in Q3, and the 2027 outlook shifted from '3x+' growth to '3x' growth.
Cisco raised its FY revenue and EPS guidance, with shares up over 8% after hours at one point.

1. Hike bets rebuilt: 10Y UST yields up 10bps+ in two days
Fed path: October voter Hamak of the Cleveland Fed said inflation is 'moving the wrong way' and argued for 'more frequent, smaller' hikes. The Fed also removed the Oct 2027 FOMC date from its calendar the same day.
USTs: 10Y at ~5.13%, 2Y ~4.88%, both up ~14bps on the day. PPI prints tonight; JP Morgan expects headline +0.6%, core +0.4%.
2. High-vol assets
Brent +3.3% to $95.82: Trump said the US does not need a deal with Iran, while Iran said the Strait of Hormuz remains closed until seven conditions are met.
DXY +0.3% to 103.17: two straight days of fresh 19-month intraday highs.
Gold -3.0%, silver -3.7%: gold fell for a third session, with futures settling at a one-month low.
Bitcoin -3.4% to ~$71.4k: briefly broke $72k intraday, a two-month low.
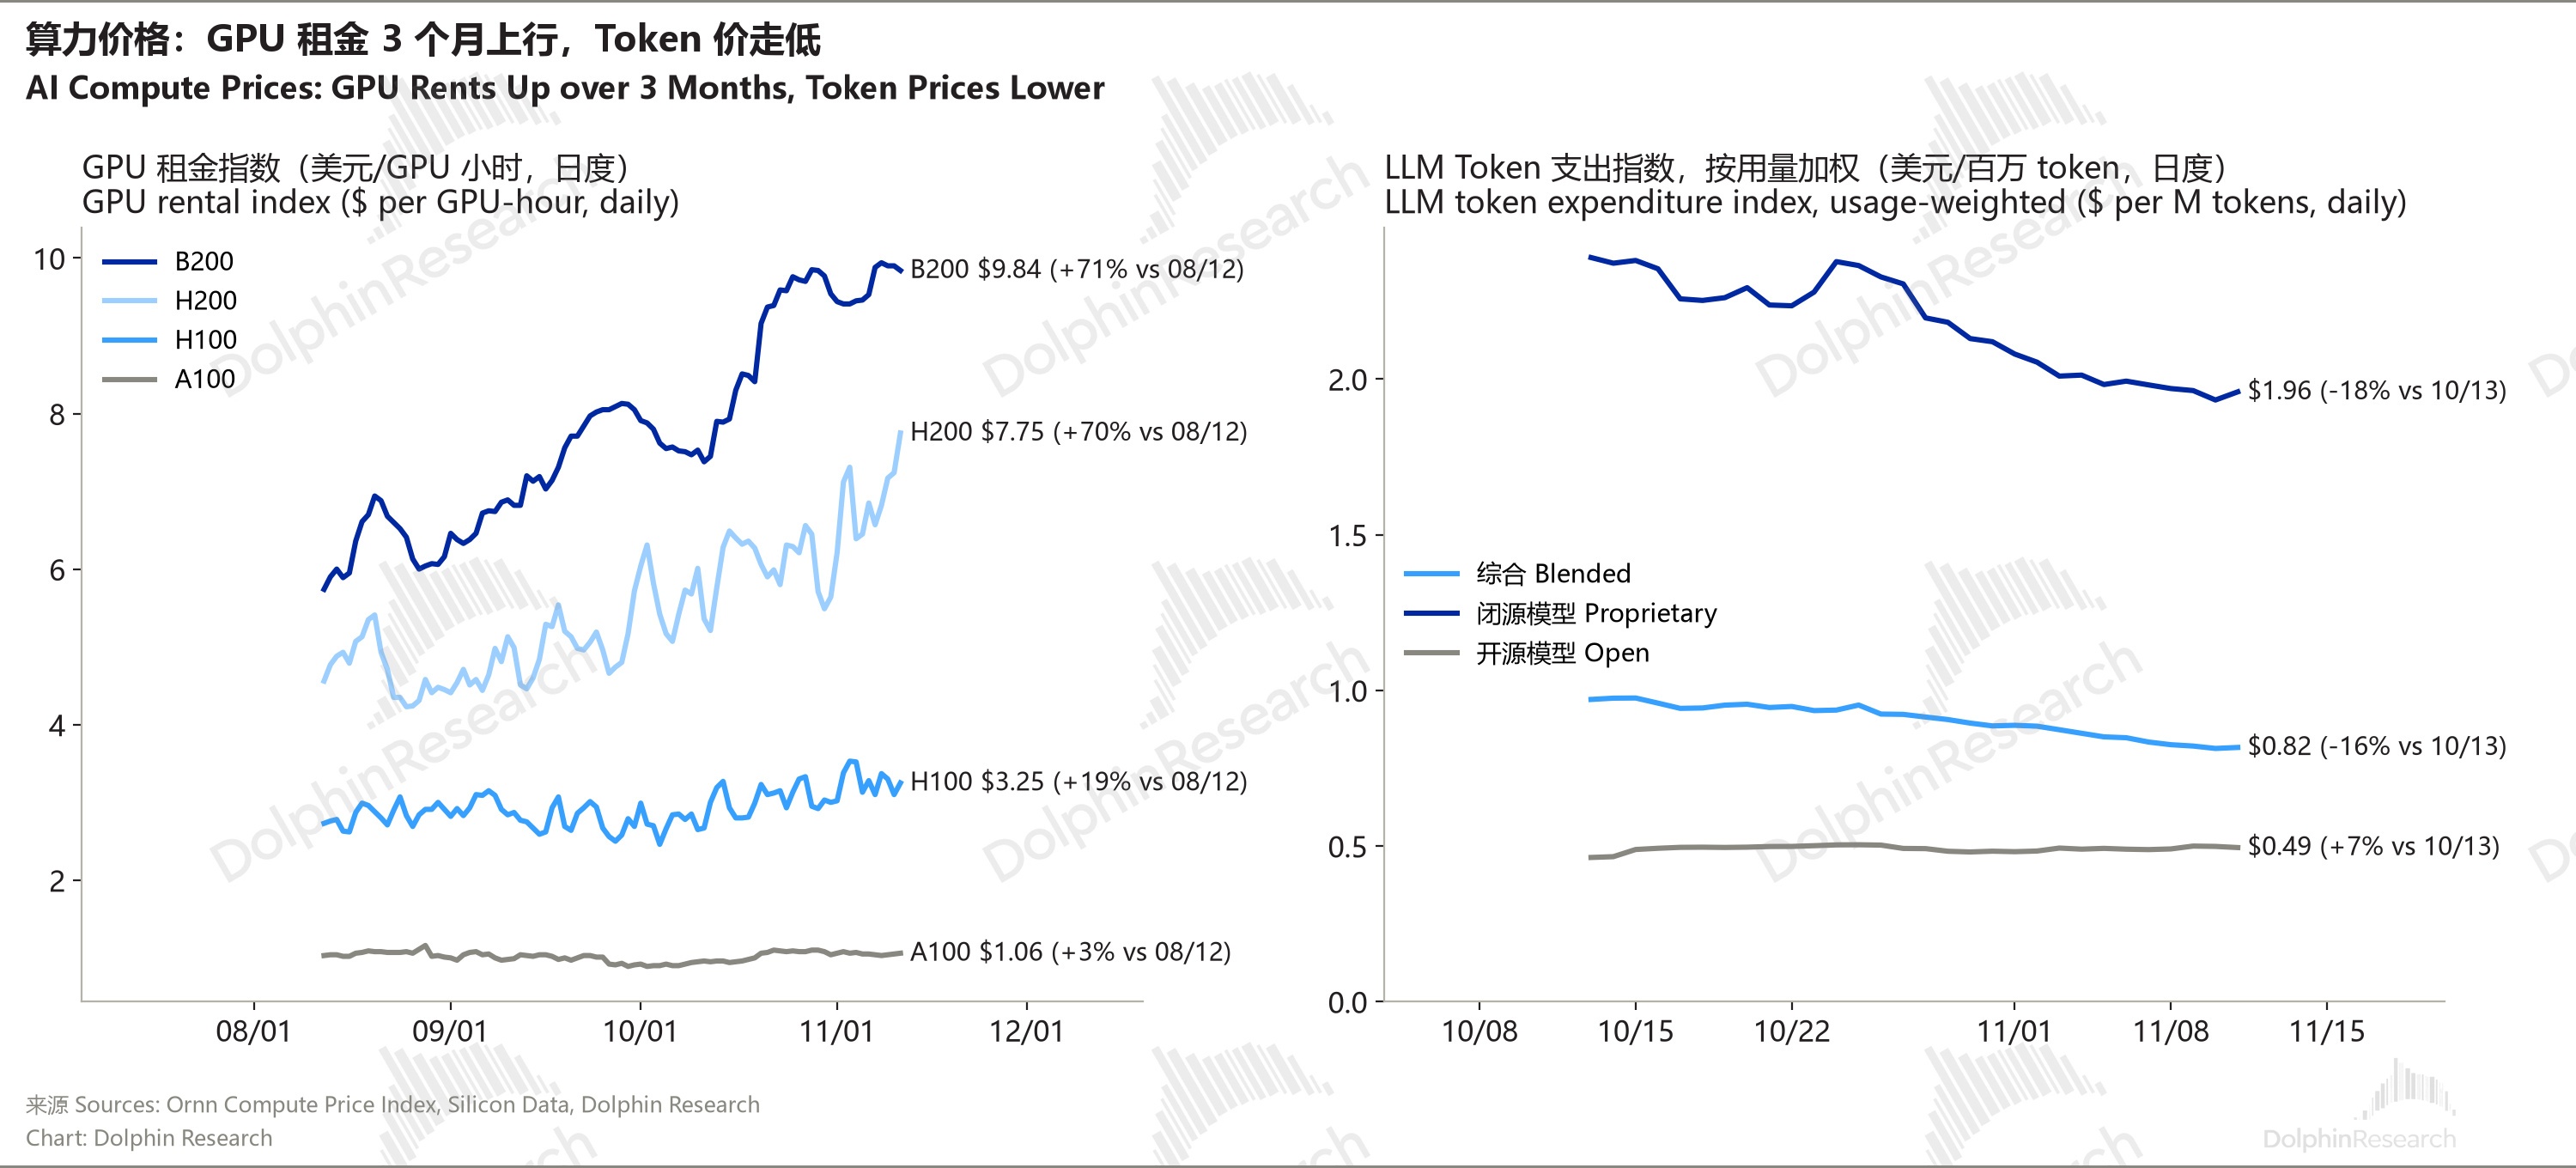
3. Compute and storage pricing
GPU rentals: B200 at $9.84 per GPU-hour, +71% vs 08/12 and +4.1% WoW. H200 +70%, H100 +19%, A100 +3%.
Token pricing: next-gen flagship models are cutting prices, with Opus 5.5 output at $20 per mn tokens (prior tier $25), Fable 5.2 at $40 (prior $50), and Gemini 4 Carbon at $10 (prior $12).
4. Asia open and today's setup (11/13)
Asia open (11/13): Nikkei 225 +0.7% at the open, KOSPI +2.1%, with SK Hynix +3.0% and Samsung Elec +2.9% at the open.
Tighter chip controls: US-listed China IDC names fell 11%+, Alibaba -7%, and bipartisan calls grew to tighten export controls. Expect pressure on HK-listed Alibaba, IDCs and compute lessors, while A-share domestic compute chains may see substitution support; SMIC's Q3 beat but Q4 GPM guidance is softer — watch initial pricing.


SMIC 0981.HK
Q3 revenue was $3.19bn, +6.1% QoQ and above the top end of guidance. GPM was 29.9%, up 460bps QoQ vs the 25.9% consensus, with utilization at 97.3%.
Q4 revenue guidance is +4%–6% QoQ, better than expected. GPM is guided to 26%–28%, down ~300bps QoQ mainly on higher depreciation.
Dolphin take: growth is almost entirely shipment-driven with flat ASPs, and GPM tailwinds have shifted from pricing to full utilization and mix, while dilution levers are limited near full load. The mid-cycle case of 'volume + price up' in mature nodes remains on AI spillover and localization, but with fabs running full, the key is the next growth driver (First Take) (Earnings review).
INTC -2.1% / ARM -1.8%
Flows concentrated in AMD, AVGO and a few TP-chain names, while most other semis lagged. SOX -0.5%.

Applied Materials AMAT | $302.3bn | -3.6% (AH +0.6%) / ASML -2.4%
FQ4 revenue hit a record $10.4bn, with FQ1 guidance mid-point at $11.1bn, +58% YoY. Management sees WFE up 30%+ by 2027 and expects to outgrow the market.
Cleanroom and supply-chain constraints still cap shipments, and AMAT plans to double system output capacity vs FQ4 by 2028 (Trans).

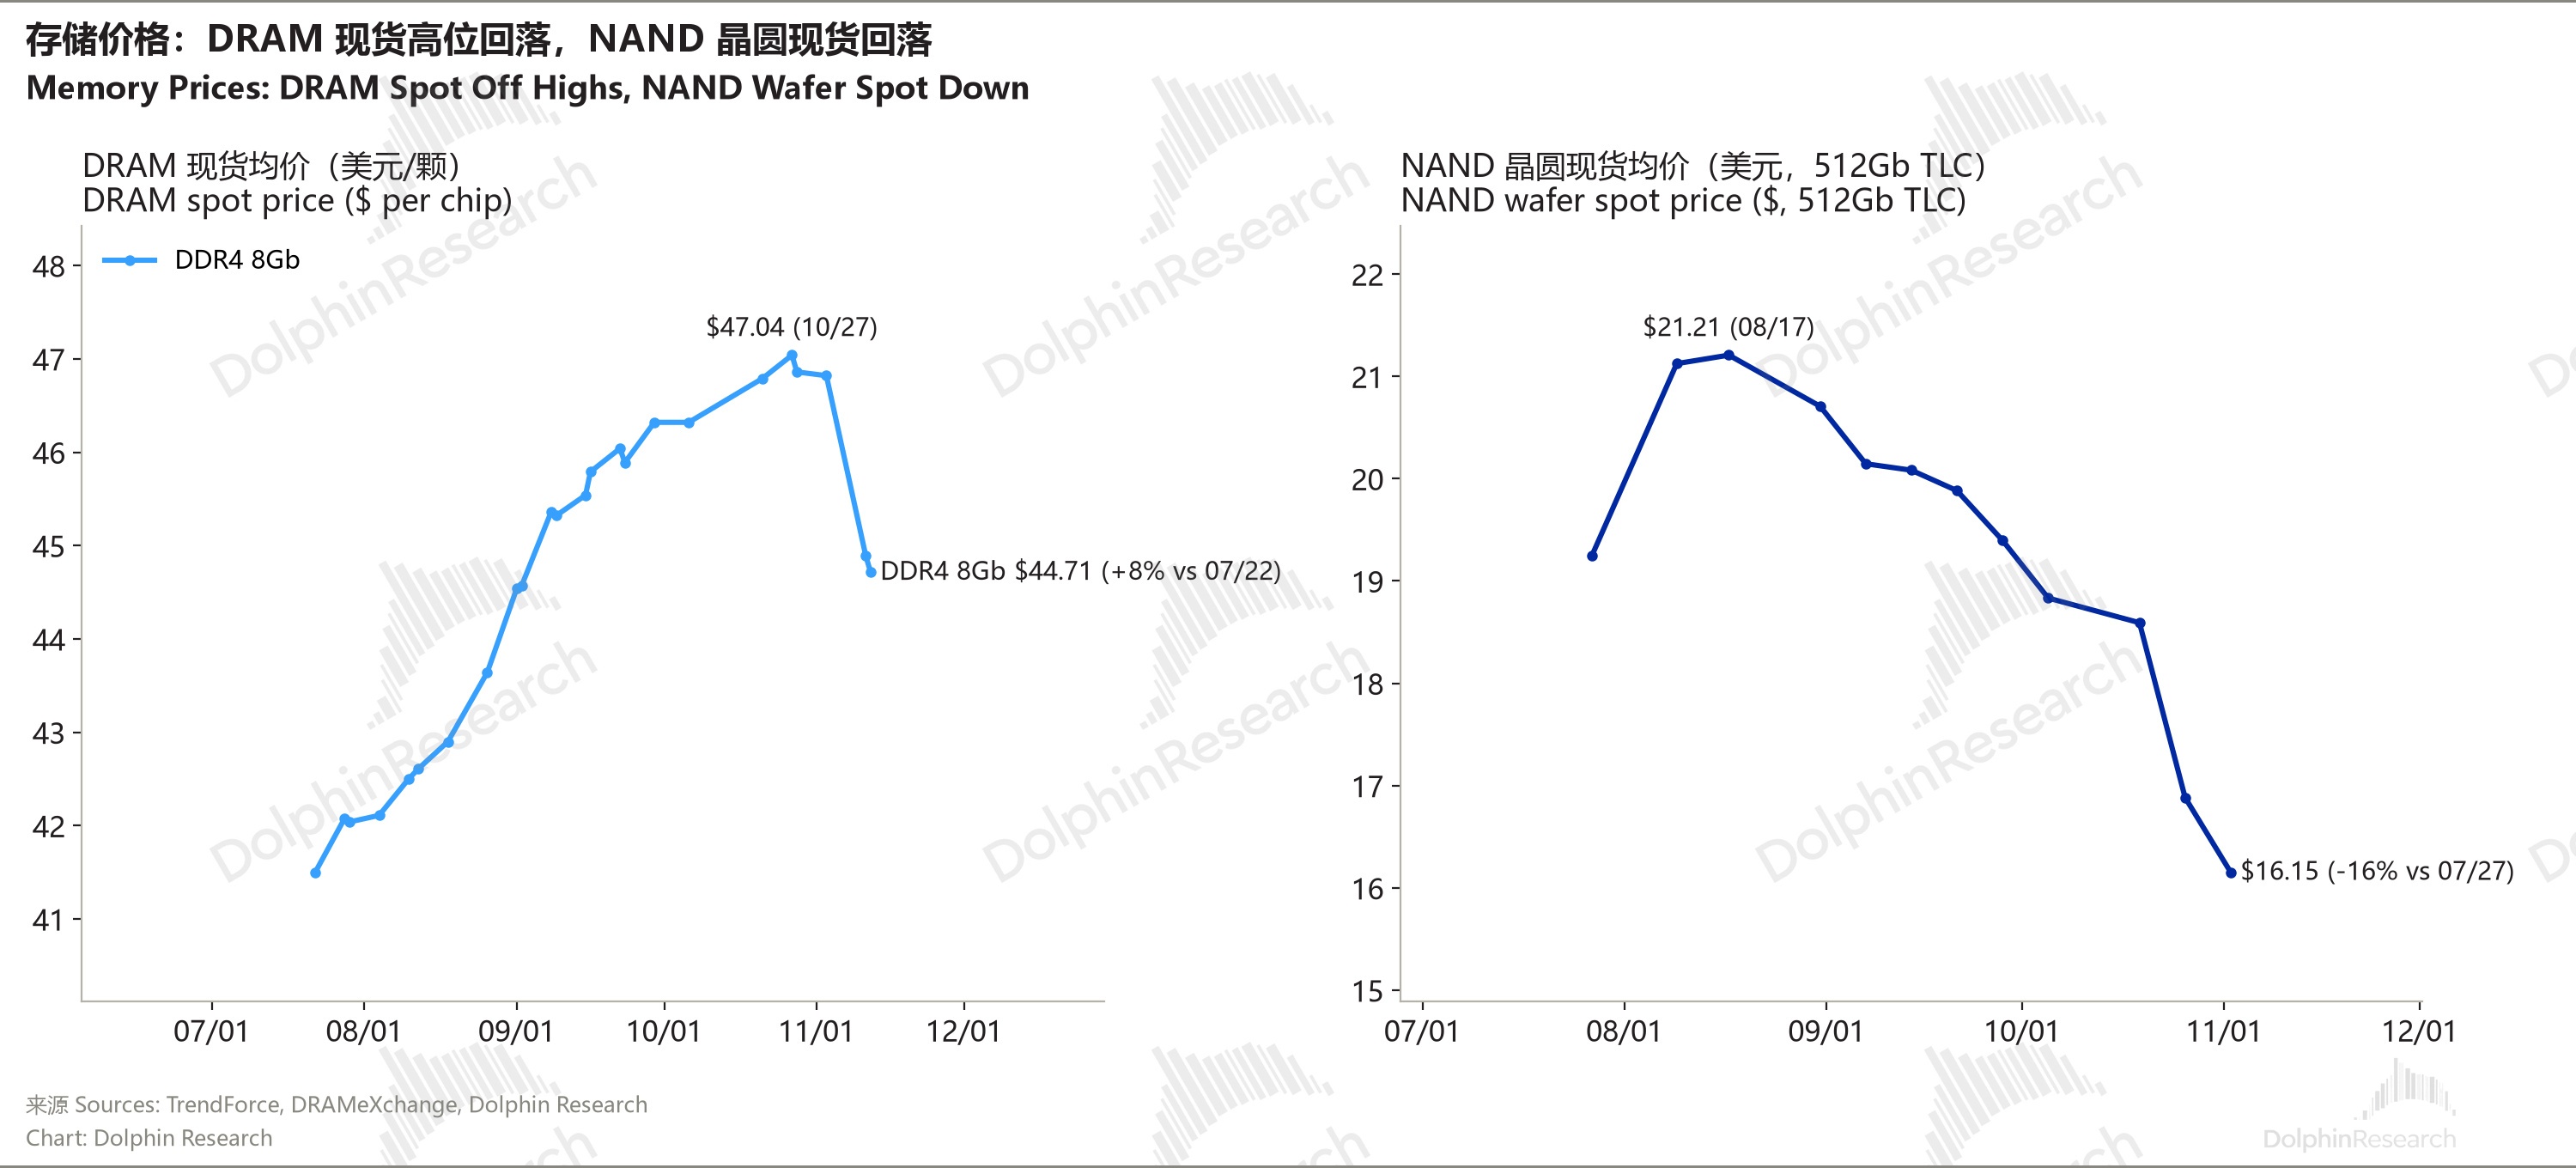
Western Digital SNDK -4.1% / MU -1.6%
Both tracked the AI hardware complex lower. Foxconn's chairman said memory and parts shortages will persist into 2027, though spot memory pricing has trended lower recently.

AMZN +0.5% / MSFT +0.4% / META -0.8% / AAPL -0.2% / ORCL -1.0%
Mega-cap tech was mixed as the tape faded. ORCL's new debt relies on supplier financing tied to NVDA, and with a more cautious stance on guarantees under new leadership, it is seen as one of the losers.

TSLA +1.7% / SPCX +0.1%
Bloomberg said SpaceX–Tesla merger talks are progressing, with an announcement possible as early as Dec or early 2027. SpaceX plans to invest $74bn in data centers in Arizona and Texas.
There was chatter that Anthropic may stop renting compute from SpaceX after mid-2027, to which Musk responded he is happy to take it back.


| Date | Event | Focus |
| Fri 11/13 | US Oct PPI; Nov Univ. of Michigan sentiment (prelim.) | JP Morgan expects headline +0.6%, core +0.4% |
| Mon 11/16 | BIDU earnings | See preview below |
| Tue 11/17 | NVDA earnings | First print post Jensen's resignation |
| Wed 11/18 | Tencent earnings; Anthropic pricing AH; NVDA interim CEO Kress hosts all-hands | Whether to upsize after ~6x oversubscription |
| Thu 11/19 | Alibaba, Lenovo earnings; Anthropic lists on Nasdaq (ANT) | Whether day-one performance keeps the AI funding window open |

NVDA | 11/17 AH
Focus: first earnings after Jensen's resignation with CFO Kress as interim, the only exec besides Jensen who regularly spoke on calls. The market wants color on 2027 orders, customer diversification and the CEO search.
Bernstein models Q3 revenue at ~$108.4bn, with data center at ~$101.0bn, and sees non-GAAP GPM slipping from 75.0% last quarter to 74.0%.
Dolphin watchpoints: FY28 growth guide (first given at ~70% last quarter vs underlying demand nearer 100%) and cloud backlogs (over RMB 2tn last quarter). Also, memory price headwinds to GPM (last guide pointed to a 71%–72% trough in Q4) and the mix of non-hyperscale customers in data center (set to be about half).
BIDU | 11/16
Dolphin watchpoints: AI Cloud (base business RMB 7.3bn in Q2, +50% YoY, with GPU Cloud +283% YoY) and the decline in legacy ads (Q2 -19%).
Capex (RMB 11.4bn in Q2, 45% of revenue) and buyback cadence, plus two catalysts Dolphin flagged: traffic integration and Kunlun chip IPO progress.
Tencent 0700.HK | 11/18
Focus: Bloomberg said Pony Ma is willing to put half of resources into AI-native biz and rallied 100k employees to embrace AI.
Dolphin watchpoints: capex (RMB 52.8bn in Q2, 26% of revenue, possibly reaching RMB 200bn for the year) and FCF (Q2 -RMB 13.8bn). Also, whether ads continue to act as a profit lever (Q2 +22%) and the growth rate of enterprise services (about 30% in Q2, likely accelerating in Q3).
Alibaba BABA | 11/19
Focus: HKEX has approved Pingtouge's spin-off. But the NVDA saga raises concern that China cloud players cannot secure advanced chips, BABA fell 7.1% in US trading Thu, and Double 11 did not disclose GMV growth.
Dolphin watchpoints: external cloud revenue growth (45% last quarter) and AI-related product revenue (double-digit growth for 12 straight quarters, RMB 12.376bn last quarter). Also, capex and cash flow (capex RMB 67.678bn last quarter, FCF -RMB 44.67bn) and food-delivery loss reduction.
<End here>
Recent dailies
2026-11-12: Dolphin Daily | Retail lifts Nebius, more NVDA scandals weigh
2026-11-11: Dolphin Daily | NVDA -5% again, 50bp hikes back on table; Nebius on trial?
Risk disclosure and statement: Dolphin Research disclaimer and general disclosures
The copyright of this article belongs to the original author/organization.
The views expressed herein are solely those of the author and do not reflect the stance of the platform. The content is intended for investment reference purposes only and shall not be considered as investment advice. Please contact us if you have any questions or suggestions regarding the content services provided by the platform.