
2026.11.10 (EST) Pre-Market

Posts

R
ReidMarlow
Featured

Sea Limited's Q3 2026 earnings release shows how segment investment masked solid core operating growth behind the headline Adjusted EBITDA miss.

Consolidated GAAP revenue rose 43.4% YoY to $8,582.3M, gross profit grew 51.4% to $3,935.4M, and net income reached $502.5M (+34.0% YoY). Total Adjusted EBITDA climbed 28.9% YoY to $931.3M, with every operating segment expanding profits: Shopee reached $269.2M (+44.7% YoY on $39.7B GMV and $6,070.2M GAAP revenue), Monee posted $298.3M (+15.5% YoY on $1,621.9M GAAP revenue), and Garena delivered $458.2M (+45.9% YoY on $890.0M bookings).

Two lines explain why consolidated EBITDA growth lagged top-line momentum. Sales and marketing expenses jumped 60.0% YoY at Shopee to $1,431.6M and 111.8% YoY at Monee to $334.6M as the group pushed user acquisition and lending growth. At the same time, Other Services Adjusted EBITDA widened 233.9% YoY to -$83.9M from -$25.1M a year earlier as Sea funded early-stage Sea Cloud initiatives.

On the balance sheet and credit side, Monee's consumer and SME loans principal outstanding expanded 60.0% YoY to $12.6B with a 1.3% 90-day NPL ratio, while Sea completed $997.2M in share repurchases under its prior $1B program and authorized a new $1B buyback. Tracking whether Sea Cloud losses widen and whether Monee credit losses stay contained as off-book and on-book lending scales matters more for 2027 margins than one quarterly EBITDA miss.

Source: Sea Limited Q3 2026 Financial Results Release (Nov 10, 2026). Informational summary only, not investment advice.
F
Fattycat

$Sea(SE.US)

🛍️ Is Shopee Still Sea Limited’s Main Growth Driver?

For Singapore investors following this leading regional tech name, Sea Limited’s Q3 2026 results give us a very clear answer.

Shopee has delivered its most profitable quarter ever and it remains the core engine powering the group’s growth.☺️

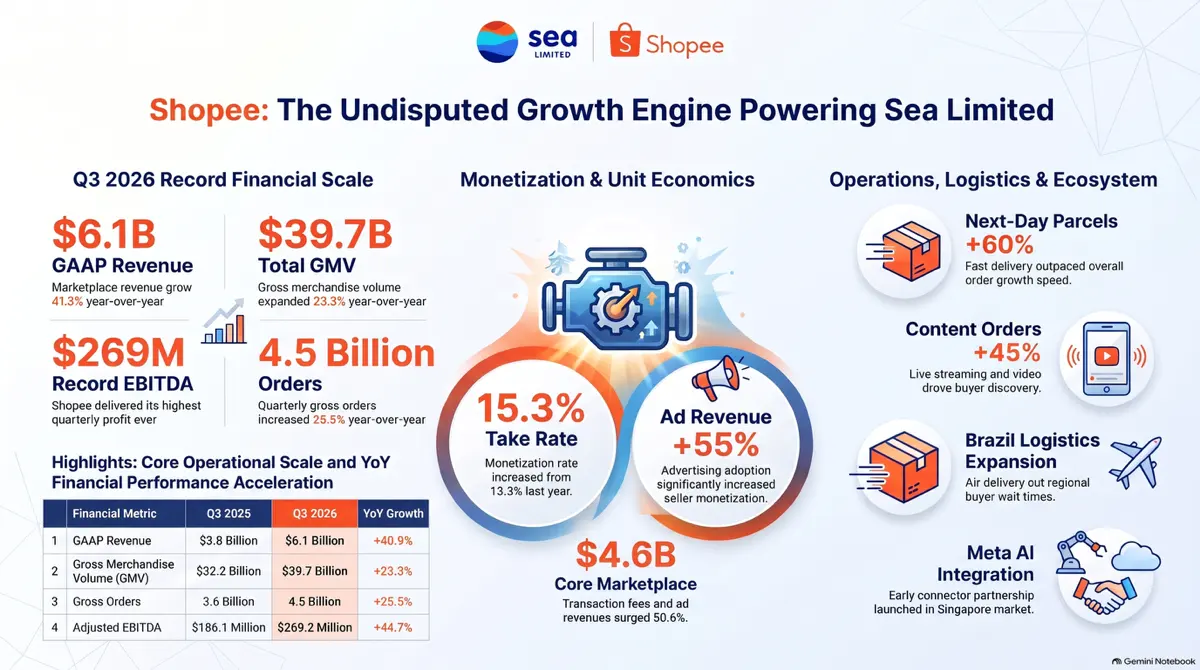
Here are the key extract numbers from the E‑Commerce Platform Growth Report in infographic:

✅ Record revenue 

Shopee’s GAAP revenue jumped 41.3 % year‑on‑year to US$6.1 billion. Core marketplace revenue led the rise, climbing 50.6 %.

✅ Stronger sales activity 

GMV rose 23.3 % year‑on‑year to US$39.7 billion, on 4.5 billion gross orders, a 25.5 % increase from last year.

✅ Highest‑ever profitability 

 Adjusted EBITDA hit a fresh all‑time high of US$269.2 million, up 44.7 % year‑on‑year, showing improving per‑unit economics.

✅ Better monetisation 

Advertising revenue grew more than 55 % year‑on‑year, while the count of sellers paying for ads rose over 35 %.

✅ Funding long‑term plans 

The strong cash flow from Shopee gives Sea the resources needed to keep investing in AI and supporting infrastructure.

On the earnings call, management shared confidence Shopee can keep up its expansion pace. They are guiding for roughly 25 % year‑on‑year GMV growth and US$1 billion in adjusted EBITDA for the full FY 2026.

With the above assurance from management, I believe Shopee will continue to deliver both higher top‑line sales and wider profit margins. It will also continue to hold an important place in Sea Limited’s business.

Curious to hear everyone’s view. Will Shopee fall out of favour over the next five years?

⚠️ Disclaimer: For discussion only, not financial and investment advice.Do your own due diligence.

Source: SEA limited official website - September Quarter 2026 results

图片 1,共 1 张
P
Pingu
Featured

$Sea(SE.US)

Sea Limited $Sea(SE.US) reported strong Q3 2026 results on November 10. Revenue reached $8.6 billion (+43.4%), while net income rose 34% to $502.5 million. Diluted EPS was $0.78, below expectations.

Growth in Shopee, Monee and Garena is encouraging, but the earnings miss creates short-term pressure.

$Tesla(TSLA.US)$Meta Platforms(META.US)$Alphabet(GOOGL.US)

图片 1,共 1 张
G
gedebe

$Sea(SE.US)

Sea Limited earnings does not meet market expectations for Q3 2026. But what is more worrying is its CEO Forrest Li intention to offer cloud services, he might have taken Amazon and Alibaba which started as an ecommerce platform and then expanded to Cloud services as inspiration. Being a new entrant into a now crowded cloud service providers will bleed more cash from the company for the initial setup and profiting from it will need another masterful execution.$NVIDIA(NVDA.US)$Intel(INTC.US)$Netflix(NFLX.US)

图片 1,共 1 张
N
NewUser_oPJWOU

$Sea(SE.US)

Context: Sea Ltd. on Tuesday reported higher profit in its third quarter with increased revenues. Further, the firm said its board of directors on Monday approved an additional $1.0 billion to its share repurchase authorization, without expiration. In the previous $1 billion program, the company so far has repurchased 11.1 million shares for an aggregate amount of $997.2 million. In its third quarter, the company's net earnings totalled $502.46 million, 34 percent higher than $374.99 million last year. Earnings per share grew 32.2 percent to $0.78 from prior year's $0.59. Adjusted EBITDA increased by 28.9 percent year-on-year to reach $931.3 million with strong growth in all segments. Shopee Adjusted EBITDA1 was US$269.2 million, up 44.7 percent year-on-year. The company's revenue for the period rose 43.4 percent to $8.582 billion from $5.986 billion last year. Shopee revenue was $6.1 billion, up 41.3 percent year-on-year. Gross orders totaled 4.5 billion for the quarter, increasing by 25.5 percent year-on-year.

My Trade: Was actually aiming for nearer to $70 as it fell briefly during pre-marker but now the stock is up. Is ok, I will be patient.

Takeaway: Shopee's revenue increase is actually heartening, especially with intent competition from TikTok Shop in the past year as well. @Captain's Treasure

2025.10.10 ~ 2026.11.09 All orders
Cumulative P/L7.03 (USD)+1%
2025.10.102026.11.09
D
Dolphin Research

SE 3Q26 First Take: Results were mixed this quarter: top-line growth was solid with all three segments — e-commerce, fintech, and gaming — beating estimates. However, profitability was softer, with GAAP OPM below expectations and down QoQ, and adj. EBITDA also missing. The bigger focus, though, seems to be investment tied to a planned cloud push, which already appears in this quarter.

1) Overall: Revenue Beat, Margins Meh

Total revenue rose 43% YoY, about 6% above consensus. GAAP OPM was ~7.7%, roughly 50bps below expectations and lower QoQ, while adj. EBITDA came in about 6% below consensus.

All three segments beat on revenue growth, with stronger contributions from e-commerce and fintech and a softer print from gaming. On profitability, e-commerce held up, while gaming and fintech weakened. Notably, the 'Other' segment loss nearly doubled QoQ, becoming the key drag on group profit vs. expectations.

2) E-comm: Growth Decelerated as Expected; Lower AOV Drag; Margin Edged Up

GMV grew 23% YoY, in line with consensus and slower than last quarter’s 28.5%. Order volume rose ~25.5%, ahead of expectations, while AOV fell ~1.8% YoY vs. +1% last quarter, likely reflecting FX headwinds from weaker ASEAN currencies.

Take rate continued to climb, with 3P monetization up ~60bps QoQ, driving Shopee revenue to beat. On profitability, adj. EBITDA/GMV was ~0.68%, up slightly QoQ and in line with expectations, indicating a solid showing for this core segment.

3) Gaming: Billings Growth Slowed; User Metrics Soft; Margin Down QoQ

Billings were ~$890mn, up ~6% YoY, a clear slowdown from last quarter’s 15.5%. Both active users and paying users came in slightly below expectations, and adj. EBITDA/billings was ~51.5%, down ~200bps QoQ.

Management cited support from a Free Fire x Naruto Shippuden crossover and the 10th anniversary of Arena of Valor. However, last year’s tie-ins created a high base.

4) Fintech: Still Hypergrowth, but Credit Quality Worsened

Loan balances reached ~$12.6bn, up 60% YoY, driving fintech revenue up 64% YoY, both well ahead of estimates. That said, 90+ day NPLs rose to 1.3% from 1.0% last quarter, and adj. EBITDA margin fell to ~18.4%, below the ~20% expected and down for several consecutive quarters. Growth remains rapid, but markets will worry about rising credit risk.

5) Cloud: Investments Now Showing in CapEx and 'Other'

Q3 CapEx was ~$550mn, already exceeding full-year 2025 spend. The 'Other' segment loss also nearly doubled QoQ, and while management did not explicitly explain these shifts, the risk disclosures added 'AI, cloud and infrastructure initiatives'. These likely reflect compute and team investments related to Sea Cloud, pending confirmation on the call.$Sea(SE.US)

图片 1,共 1 张
K
koolgal

Grab Q3 Brings Good News to Investors

🌟🌟🌟For months, the stock market treated $Grab(GRAB.US)like a parking ticket. Down over 40% year to date, written off by critics, battered by macro noise, fuel scares and regulatory red tape. If you only look at the stock ticker, you would think the company is in freefall.

But out in the real world, 57 million people across South East Asia are using Grab Super App to move, eat and pay every single day.

Last night, the truth caught up with the price action.

Grab didn't just beat earnings, it shattered the narrative. For the first time ever, every single segment is printing cash. This includes Financial Services. Revenue is up 27% to over a billion dollars. Guidance lifted. A massive USD 400 milli on buyback, proving that management knows exactly how undervalued this company is.

To everyone who held Grab during the year's lows and who ignored the noise, your patience is finally being validated. The Giant has awakened.

Dear Fellow Investors, Do you think Grab is on an upward momentum?

@Captain Leo

FSM ★ × The past is your LESSON. The present is your GIFT The future is your MOTLong image
C
Captain's Watch
Featured☕️ [Task Coins Giveaway] Daily Market Talk — Apple Beats, but Memory Costs Bite

Apple beat forecasts but slid after hours as rising memory costs squeeze its margins, while chipmakers fell for a third straight day. At home, the STI is sliding again as the banks lead losses, though...