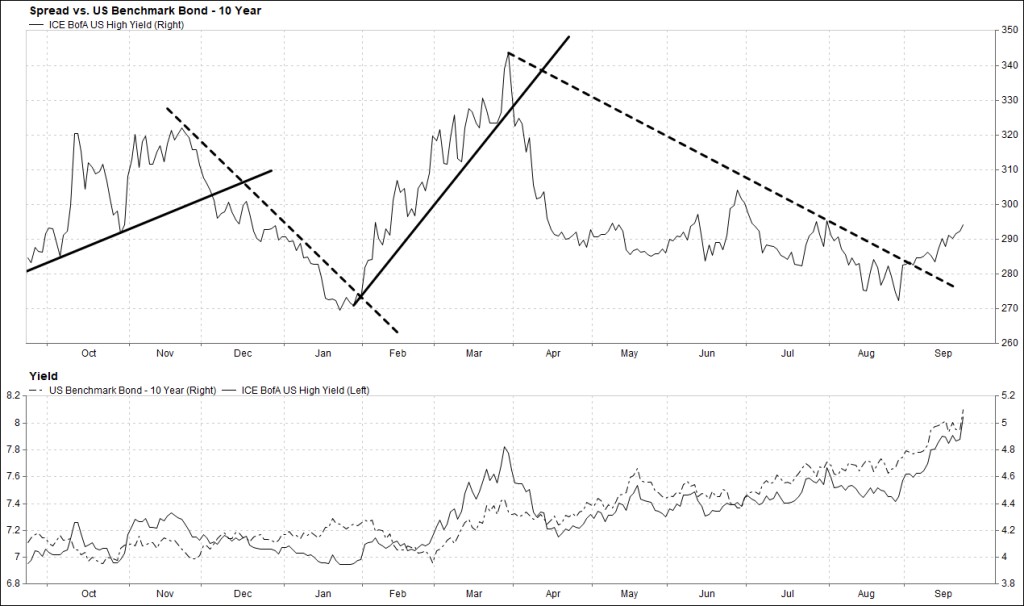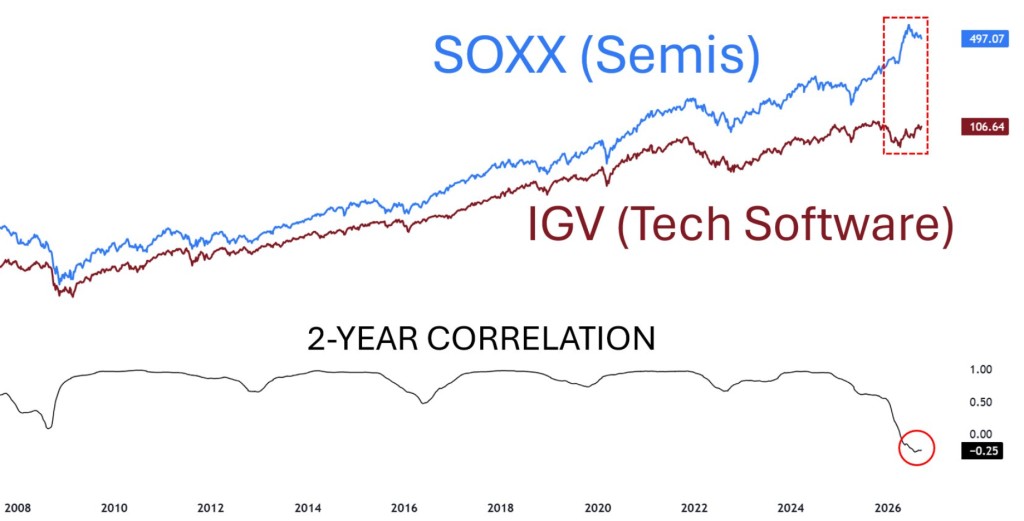
It looks more like a rotation within the AI trade than a clean hardware to software handoff. The 10-year yield recently crossed 5%, raising the discount rate and pressuring long-duration software valuations.
Meanwhile, AI infrastructure demand remains strong, with hyperscaler capex still accelerating and cloud demand absorbing capacity.
The key signal to watch would be whether AI software revenue and margins start accelerating faster than infrastructure spending. If that happens alongside sustained high yields, the hardware to software rotation thesis becomes much stronger.