
$SingPost(S08.SG)
SingPost: Parcel Growth Is the New Post
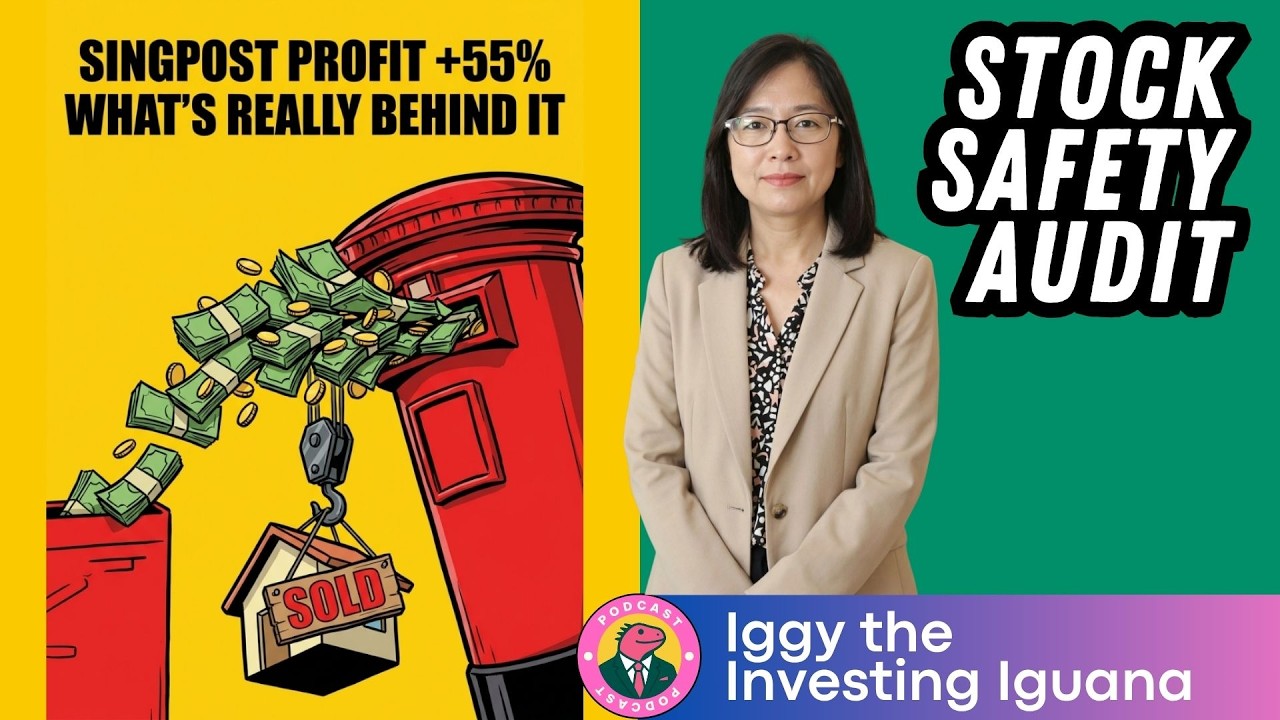
SingPost’s Q1 FY26/27 update shows encouraging operational progress, but the investment case remains one of execution rather than growth. The reported figures are validated: revenue fell 0.9% to S$93.4 million, while operating profit jumped 55.2% to S$4.1 million as operating expenses declined 2.4% to S$89.3 million. Operating margin consequently improved to 4.4%. (The Business Times)
The improvement is meaningful against FY2025/26, when revenue plunged 23.1% to S$376.1 million and operating profit fell 68.9% to S$11.8 million. Underlying net profit was only S$10.7 million, highlighting still-thin profitability. (SingPost)
Fundamentally, the structural decline in letters remains the problem: domestic letter volumes fell 13.5% in FY26. However, domestic eCommerce volumes rose 8.1%, while Q1 domestic parcels surged 36.5%. SingPost is clearly repositioning toward logistics, warehousing and value-added services, supported by S$30 million of investment in automated parcel sorting. (SingPost)
Technically, S08 at S$0.33 remains weak, sitting close to its S$0.31 52-week low and well below S$0.50. Valuation is not demanding at roughly S$780 million market capitalisation, but earnings quality remains the concern. (SingPost)
Position: HOLD. Parcel momentum and cost discipline are promising, but sustained earnings growth must first be proven. The transformation is interesting; the turnaround is not yet complete.
Not financial advice.