$Cisco(CSCO.US)
🚀 CSCO’s 5‑Month Slide: What Comes After the AI Boom?
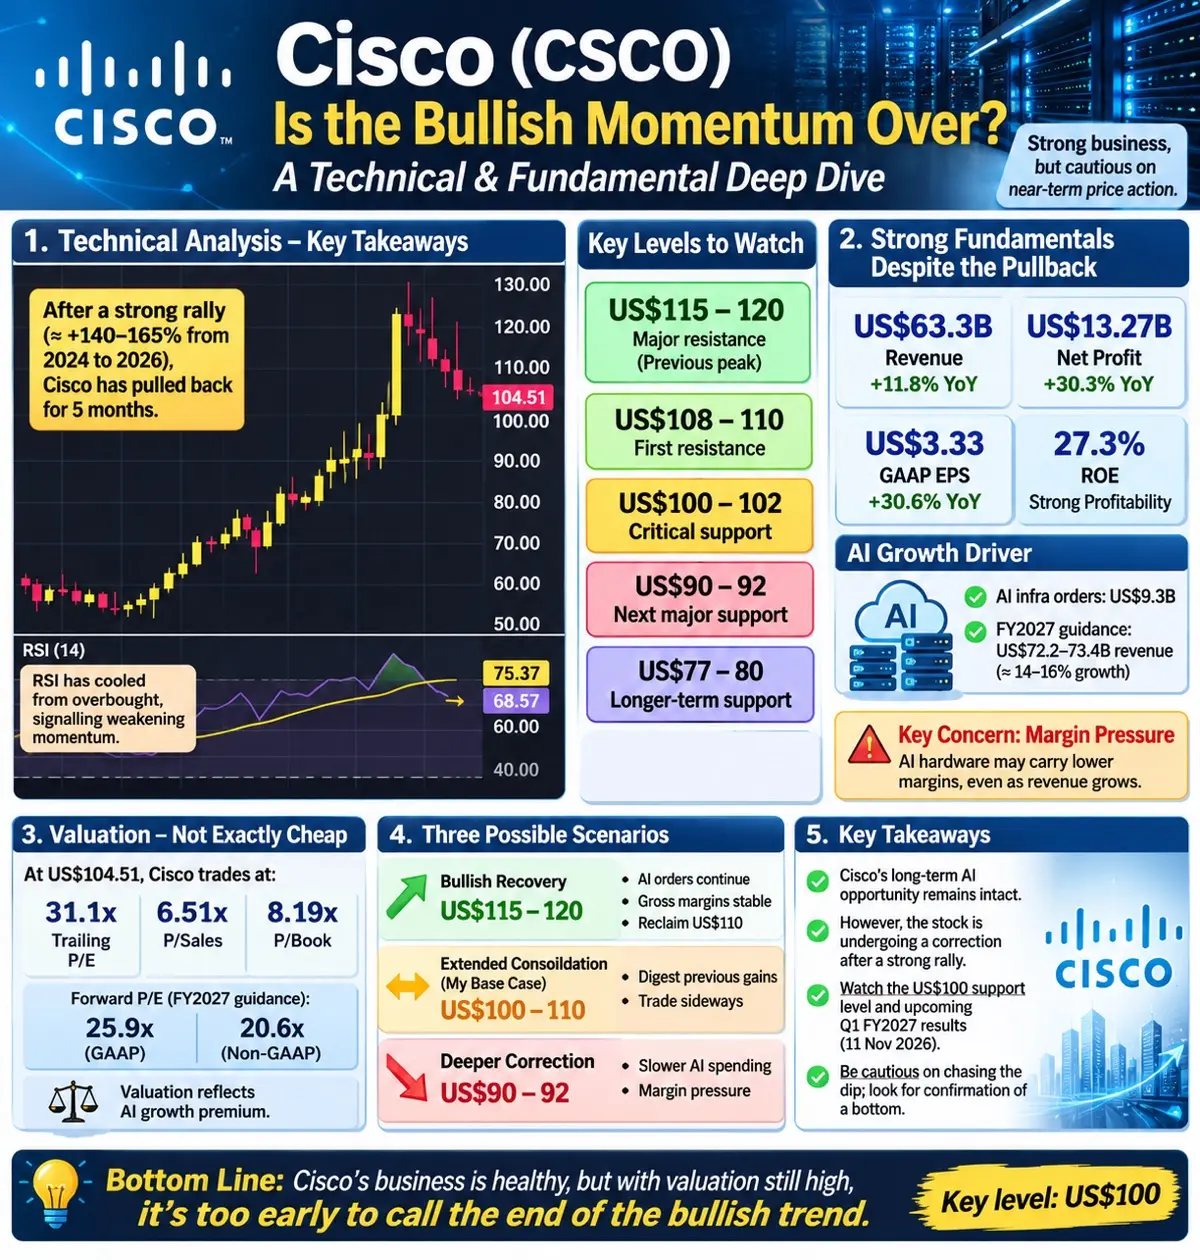
Cisco (CSCO) has enjoyed an impressive run. Its share price climbed from around US$45‑50 in 2024 to nearly US$120 in 2026.
Currently the upward momentum seems to fade. The stock has fallen for 5 months in a row and traded near US$104.51 as of 30 October, Friday.
So what is going on here?🙄
Cisco’s underlying business fundamentals remain strong. For FY2026, revenue hit US$63.3 billion, up 11.8% and net profit jumped 30.3% to US$13.27 billion.
AI is becoming an increasingly key growth driver for the firm. Cisco secured US$9.3 billion worth of orders for AI‑related infrastructure and management expects FY2027 revenue to land between US$72.2 billion and US$73.4 billion.
🔷 The areas of concern
Higher component costs and a growing share of hardware sales could put pressure on gross profit margins.
Furthermore, Cisco’s valuation stays relatively high, with a trailing P/E ratio of roughly 31 times earnings.
From a technical standpoint, the outlook looks less favourable. The RSI has moved down from overbought levels and price charts are showing lower highs plus weakening momentum.
The US$100‑102 range forms an important support zone, followed by US$90‑92 further down. On the upside, US$115‑120 remains a major resistance band.
⏰The big question:
Is this just a healthy pullback after a strong AI‑fueled rally or the start of a longer‑term trend reversal?
Cisco’s AI growth story is still intact but the markets want clearer proof that rising sales can turn into steady, sustainable margins and its profits.
Disclaimer: For information only. not financial and investment advice. Do your own due diligence.